Bitcoin
 Ethereum
 Tether
 BNB
 USDC
 XRP
 Solana
 TRON
 Lido Staked Ether
 Cardano
 Gram (prev. Toncoin)
 Avalanche
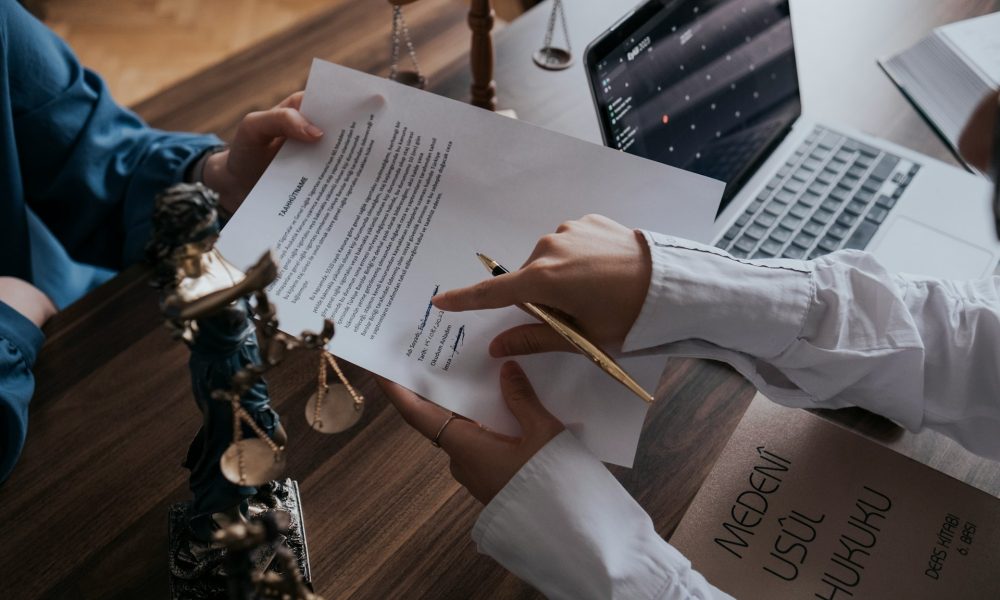
David Lutz, Minnesota Attorney – Lender Liability Defense: How Minnesota Banks Can Minimize Litigation Risk
In collaboration with David Lutz
Even in quiet conference rooms and behind well-polished teller counters, banks face growing exposure to legal claims they never intended to invite. That risk often surfaces not when a loan is issued, but when a borrower relationship begins to unravel. For community banks across Minnesota, David Lutz, Minnesota attorney, advises and helps institutions walk that legal tightrope—balancing enforcement with restraint, documentation with discretion, and most importantly, control with compliance.
Lender liability isn’t a fringe concern. It’s a recurring legal challenge that often takes seasoned banks by surprise. Disgruntled borrowers may allege that lenders interfered with operations, misrepresented terms, or applied pressure unfairly during workouts. David Lutz’s approach doesn’t just focus on fighting lawsuits once they’re filed—I emphasize spotting risks early and building in layers of legal insulation well before tensions flare.
At the heart of many claims is one surprisingly simple misstep: crossing the line between lending and managing. Courts have consistently penalized banks that exert too much influence over a borrower’s day-to-day decisions, even if intentions were good. Requiring detailed reporting is one thing; signing off on pricing strategies or inserting staff into operational roles is another. That gray zone, where oversight starts to look like interference, is where legal exposure quietly grows.
Clean documentation is critical to help avoid claims. Loan terms should be precise, commitments explicit, and all modifications formalized with signature-backed agreements. A verbal promise—no matter how brief or offhand—can later become the foundation for a borrower’s claim. Forbearance agreements, in particular, should do more than pause enforcement; they should reaffirm the bank’s rights and clearly disavow any implicit waivers.
That level of clarity doesn’t just protect against claims of oral modification. It bolsters defenses under the implied covenant of good faith—a concept Minnesota courts interpret seriously. Lenders have leeway, but they must exercise it for legitimate reasons. Whether it’s denying a collateral release or accelerating a note, the decision must be rooted in sound, documented rationale, not convenience or retaliation.
Training front-line staff is another pillar of prevention. Lutz often points out that lenders rarely intend to act improperly, but a lack of legal training makes even small errors meaningful. A misworded email, a missed record of a key phone call—these lapses can complicate even the most routine collections.
Beyond internal policies, there’s value in knowing when to shift strategy entirely. If a borrower is struggling but cooperative, a carefully structured workout—designed with legal counsel—might prevent future litigation and preserve both parties’ interests. Litigation may feel like the strongest hand, but in some cases, it’s the costliest.
As Lutz frequently advises, banks that take proactive steps—from reviewing standard loan documents to auditing enforcement practices—aren’t just protecting themselves legally. They’re protecting their time, their reputations, and their relationships with other customers watching closely from the sidelines.
The best-run banks aren’t those that never face litigation. They’re the ones that don’t flinch when the first complaint lands because they’ve already prepared, reviewed, and documented everything with precision. They’ve turned every loan file into a fortress—built not on legalese, but on clarity and care.
Ultimately, for Minnesota lenders navigating increasingly complex borrower dynamics, the defense isn’t just legal—it’s cultural. It’s about training, consistency, and a healthy respect for the boundaries that define lender and borrower. David Lutz’s message is clear: protect the paper, mind the line, and stay out of the boardroom.
This article is provided for informational purposes only and does not constitute legal advice. The information contained herein is general in nature and may not apply to your specific situation. No attorney-client relationship is created by reading this article or contacting the author in response to it. For legal advice regarding your particular circumstances, please consult with a qualified attorney.