
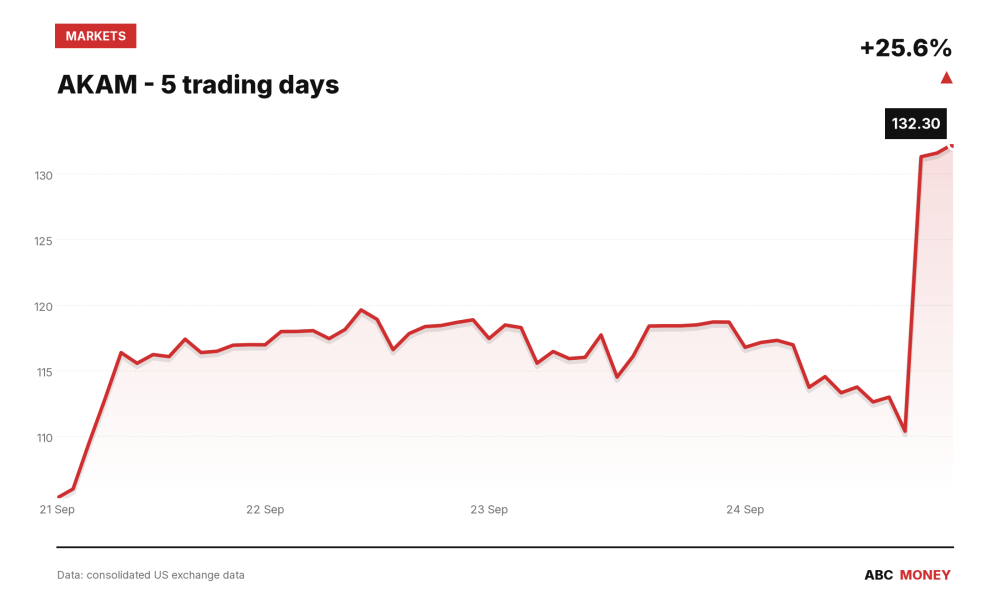
Akamai Technologies (NASDAQ: AKAM) shares jumped 16.39% to $131.90 on Thursday after the company announced an $11.6bn, seven-year computing agreement with Anthropic, the artificial-intelligence lab behind the Claude chatbot. Trading volume ran at 2.48 times its 20-day average as investors digested a contract that dwarfs anything Akamai has previously disclosed. The move was confirmed by Reuters, which reported the same figures independently of Akamai’s own announcement.
The Akamai Anthropic deal covers Anthropic’s growing demand for CPU-based computing capacity, delivered through Akamai’s distributed cloud network – the sprawling web of servers the company built over two decades to speed up internet content delivery, now being repurposed for AI workloads. It adds to more than $2.8bn in multi-year cloud infrastructure commitments Akamai had already disclosed this year, as Benzinga noted in its coverage of the announcement.
The fine print: an option worth another $9bn
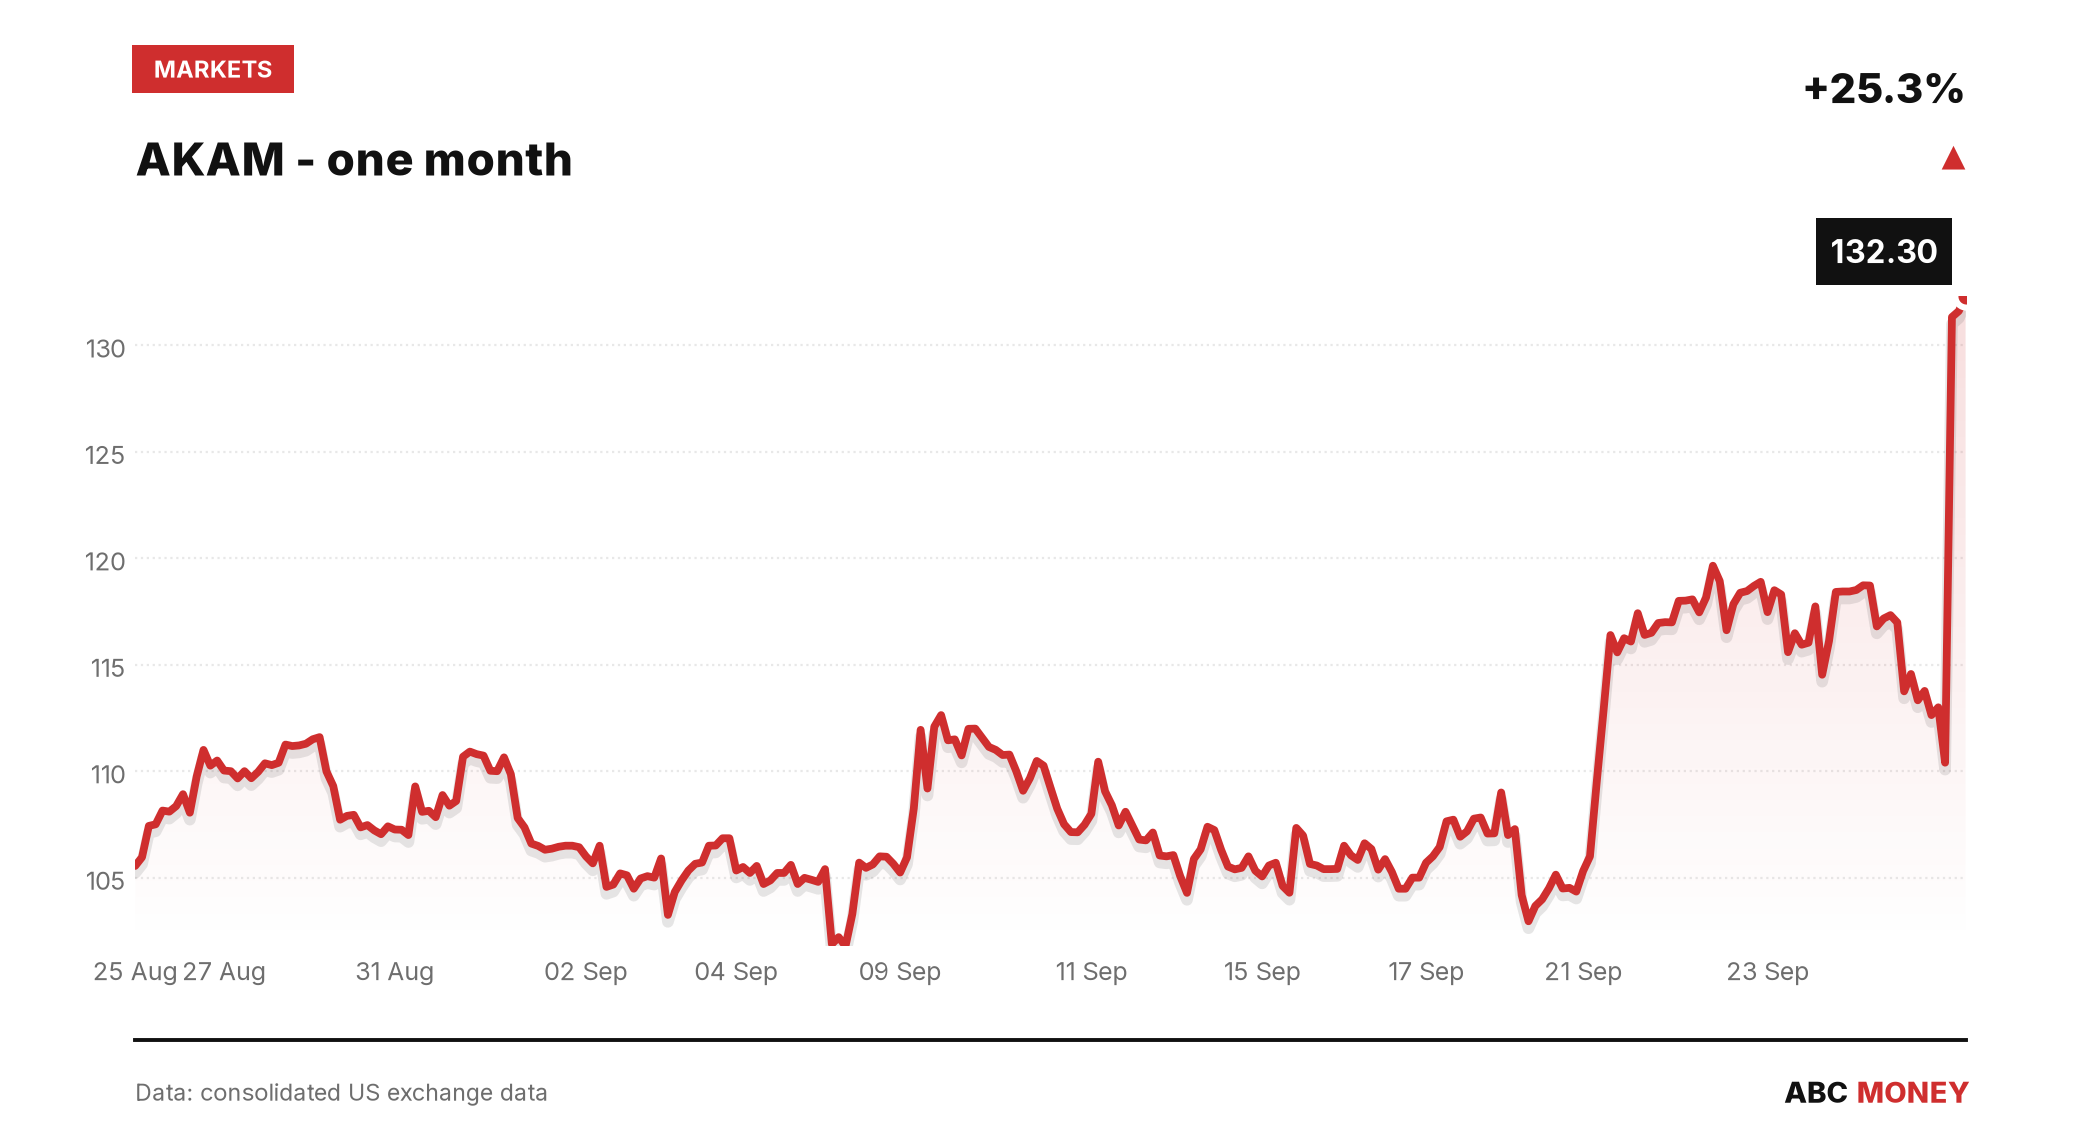
The headline number understates the deal’s potential scale. The agreement includes provisions letting Anthropic expand its commitment by up to a further $9bn, which would take the total contract value to roughly $20bn if fully exercised. That structure – a base commitment plus a large, optional top-up – has become a recurring feature of the mega-deals AI labs have been signing with infrastructure providers, locking in capacity years ahead of when they will actually need it.
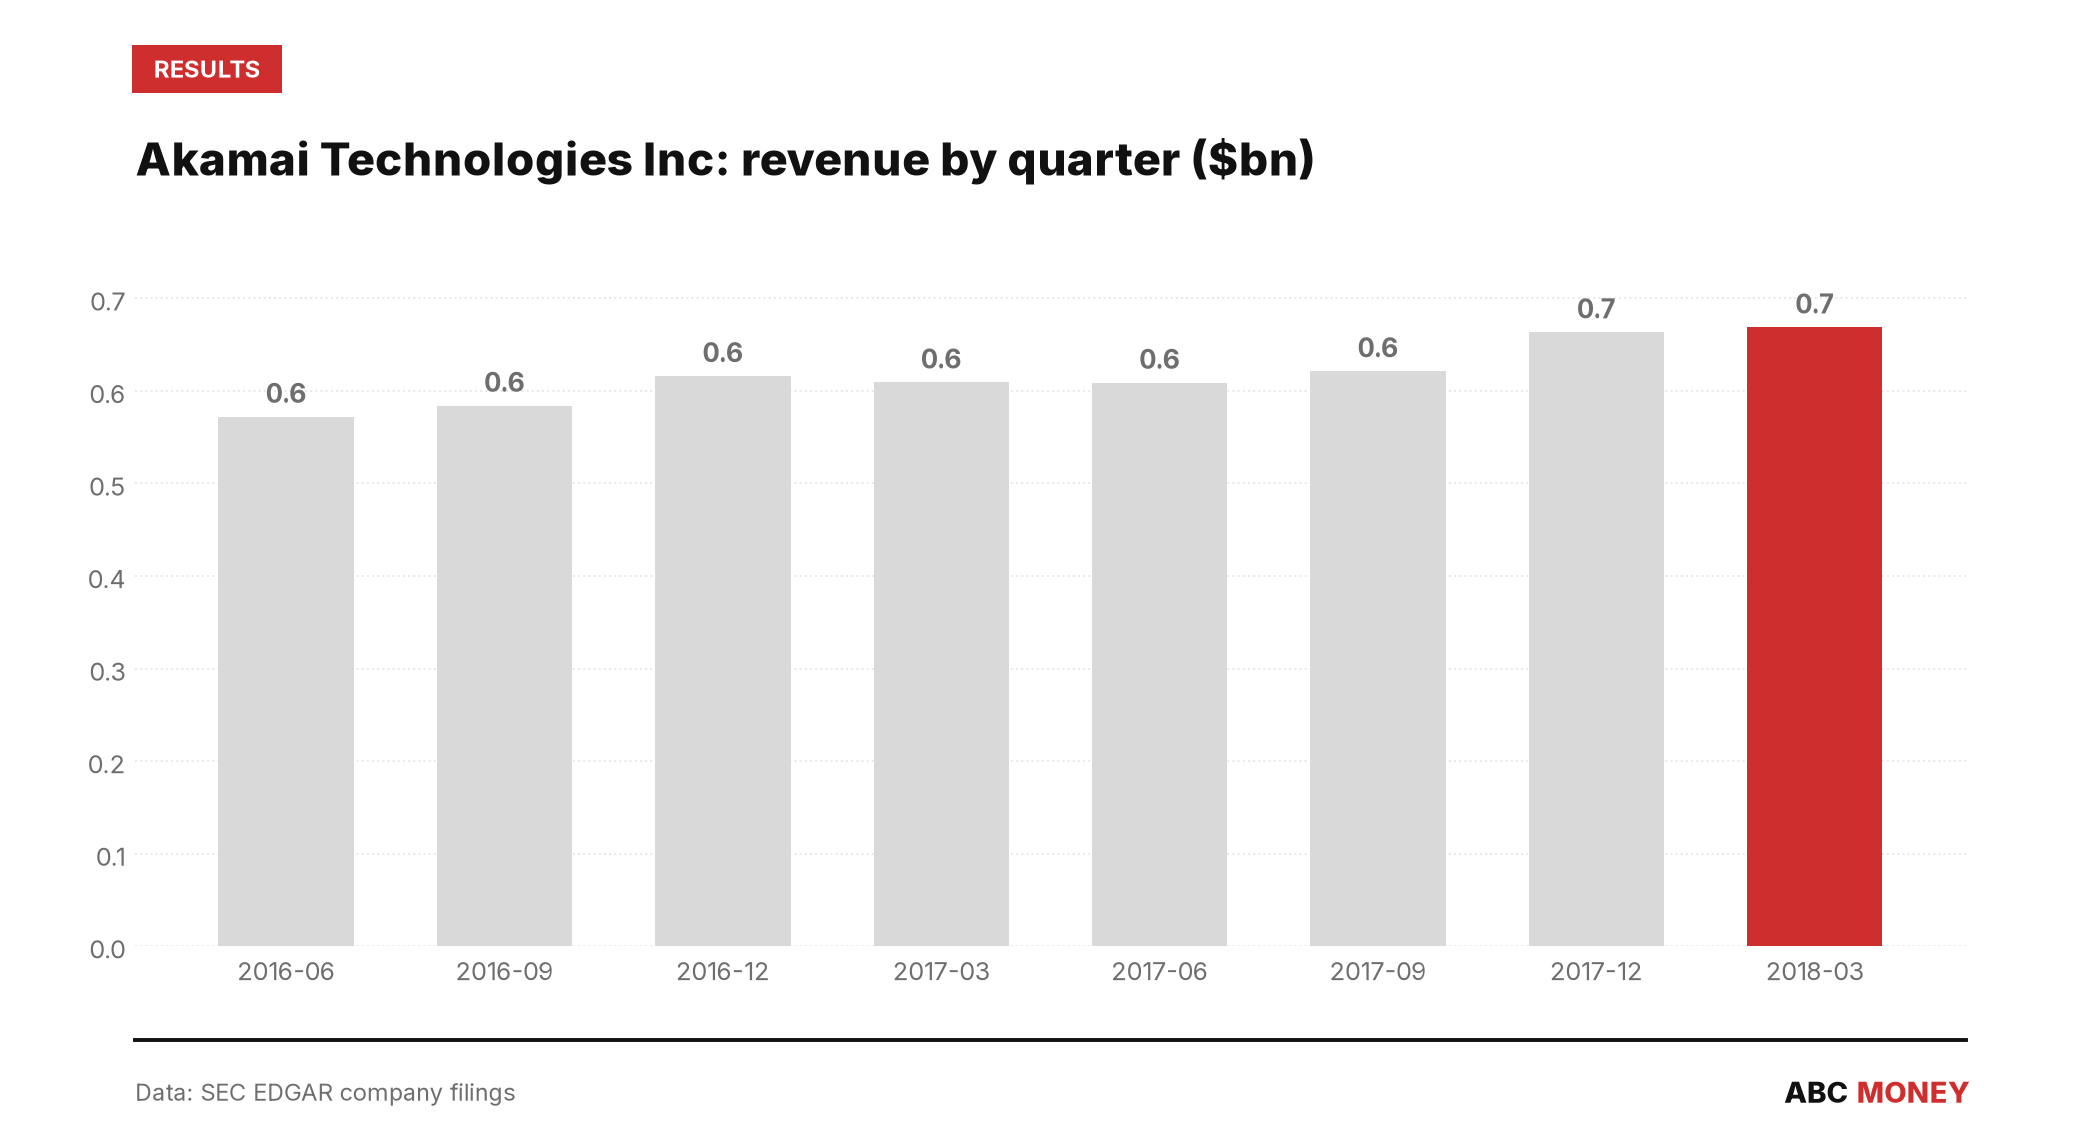
For Akamai, a company whose full-year 2024 revenue was $3.991bn, a seven-year commitment of this size – even before any expansion – represents a multiple of a single year’s top line. That gap between contracted capacity and current run-rate revenue is precisely why the market reacted as sharply as it did: this is less about next quarter’s numbers and more about a multi-year demand floor for a business that has spent years fending off questions about growth in its legacy content-delivery operations.
A warrant that pays Anthropic for showing up
Alongside the contract, Akamai issued Anthropic a warrant – the right, but not the obligation, to buy shares at a fixed price in future – for non-voting convertible Series B Preferred Stock. On an as-converted basis that equates to about 7.7 million common shares, or up to roughly 5% of Akamai’s shares outstanding, at an exercise price of $111.33. Anthropic would need to pay around $857m to exercise the warrant in full, and any exercise would ultimately dilute existing shareholders – meaning their proportional ownership shrinks as new shares are created.
Crucially, that 5% is not handed over unconditionally. Only about 2% is expected to vest against the base $11.6bn commitment; the remaining roughly 3% vests solely if Anthropic actually exercises the expansion option, in increments tied to each additional $3bn of spend. In effect, Akamai has built an equity incentive that only pays out as Anthropic consumes more compute – tying the AI lab’s potential upside directly to how much capacity it actually uses, rather than granting it upfront.
No sign of a short squeeze behind the move
Some sharp single-day rallies are amplified by short-covering, where traders who had bet against a stock rush to buy it back as the price rises. That does not appear to be the story here. FINRA’s daily short-sale data shows Akamai’s short-volume ratio – the share of daily trading volume attributable to short sales – ranging between roughly 0.37 and 0.62 in the fortnight before the announcement, with no unusual spike that would suggest positioning was already anticipating the news. The rally looks like a straightforward repricing on fresh information rather than a mechanical unwind of bearish bets.
Earnings have been lumpy – this deal won’t smooth that out immediately
Investors judging the deal’s near-term earnings impact should note that Akamai’s quarterly profitability has swung considerably even before this announcement. Net income fell from $175.4m in the first quarter of 2024 to $79.4m in the second quarter of 2026, according to filings with the Securities and Exchange Commission. A seven-year contractual commitment gets recognised in revenue over time as the capacity is delivered and consumed, not booked in one go – so the Anthropic agreement is a signal about future demand rather than an immediate lift to the numbers due later this year.
What happens next largely depends on Anthropic’s own trajectory. If the AI lab’s compute needs keep growing at the pace that has driven its recent infrastructure deals, exercising some or all of the $9bn expansion option would both extend Akamai’s revenue visibility and hand Anthropic a larger equity stake – vesting mechanics that markets are likely to track closely as Akamai reports progress against the contract in future quarters.
This article is for information only and is not investment advice or a recommendation to buy or sell any asset. Markets move quickly; figures are correct as sourced at the time of writing. Always do your own research before making financial decisions.
 Bitcoin
 Ethereum
 Tether
 BNB
 USDC
 XRP
 Solana
 TRON
 Lido Staked Ether
 Cardano
 Gram (prev. Toncoin)
 Avalanche