
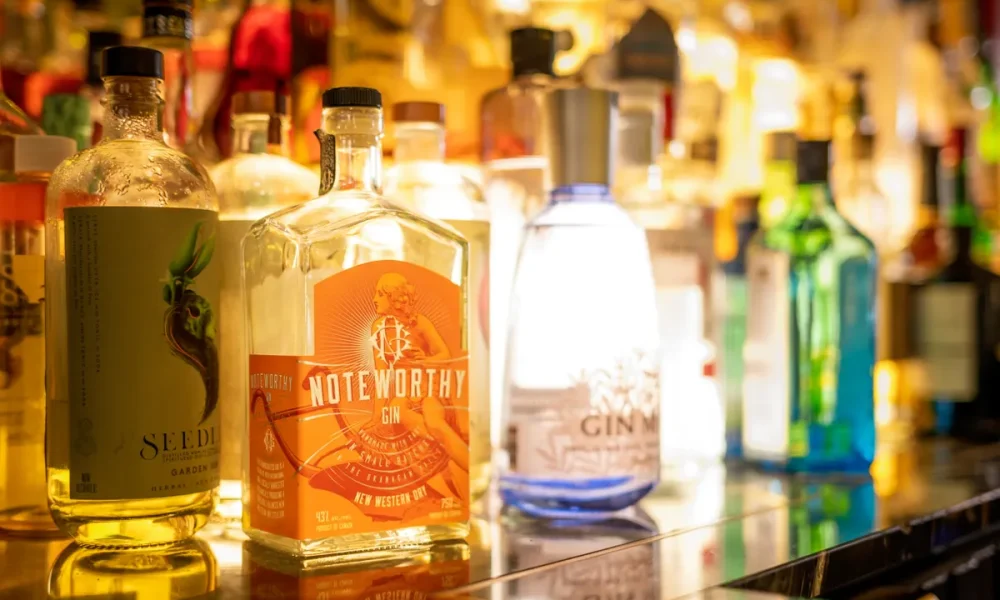
The Diageo vs BT shares debate has sharpened considerably in 2026, with both FTSE 100 stalwarts nursing multi-year underperformance and new management teams asking investors to stay patient. The question is whether either stock is cheap enough to justify the wait.
Two Turnarounds, Two Very Different Problems
Diageo (DGE) has been the harder ride. Shares have fallen 50% over five years and are down a further 15% in the past twelve months, a trajectory that accelerated in February when Reuters reported that incoming CEO Sir Dave Lewis cut the annual sales forecast and halved the dividend on 25 February 2026. The shares dropped 9.68% that day, the largest single-session decline since November 2023.
Lewis, who took the role in January 2026 following the abrupt departure of Debra Crew, guided for 2026 organic sales to fall 2%-3%. US sales were particularly weak, declining 9.3% in the reported period, with Don Julio tequila volumes off by almost a quarter. The ripple extended across the sector: peers including Pernod Ricard, Remy Cointreau, and Campari Group each fell more than 6% on the same day.
BT (BT.A), by contrast, is up 20% over five years, though it has slipped 5% in the past year. Its problems are more structural than acute: a £20bn debt load, heavy capital requirements to fund the Openreach full-fibre rollout, and a revenue line that remains stubbornly flat. First-quarter revenue held at £4.3bn while adjusted EBITDA fell 1% to £2bn.
Diageo vs BT Shares: What the Valuation Says
| Metric | Diageo (DGE) | BT (BT.A) |
|---|---|---|
| Price/earnings ratio | 14.3x | 11.2x |
| Trailing dividend yield | 2.1% | 4.1% |
| Net debt | $20.5bn | £20bn |
| 5-year share performance | -50% | +20% |
On straightforward multiples, BT looks the cheaper of the two at 11.2 times earnings against Diageo’s 14.3 times, which itself sits fractionally below the FTSE 100 average of around 15. BT also offers the more attractive income: a 4.1% trailing yield against Diageo’s 2.1%, which reflects the damage done by the dividend cut.
That cut deserves closer attention. Lewis reduced the interim dividend to 20 cents per share, down from 40.5 cents a year earlier, describing the decision as ‘not easy’ but one that would ‘create more financial flexibility’ to invest in the business. Diageo has been a Dividend Aristocrat since its formation in 1997, consistently growing payouts through previous cycles. Breaking that streak carries a reputational cost that goes beyond the immediate yield compression, as The Drinks Business noted when reporting on Lewis’s strategic reset.
Cash Flow Visibility and the Openreach Factor
BT’s investment case rests heavily on Openreach. The network now accounts for more than half of broadband revenue, and Openreach added 574,000 full-fibre customers in the latest quarter, taking total connections to 9.4 million. BT is targeting cash flow of around £2bn this year and £3bn by the end of the decade. Those are ambitious figures given the capital intensity of the build, but the direction of travel is at least legible.
BT’s 2024 annual report, filed with the FCA, shows reported earnings per share of 8.7p for that year, and aggregated FY2025 figures show EPS recovering to £0.11 with net income up 23% to £1.05bn, though revenue dipped 2.1% to £20.4bn. The earnings trajectory is moving in the right direction even if the top line is not.
Diageo’s equivalent signpost arrives on 6 August 2026, when FY26 preliminary results and a Capital Markets Day are both scheduled. Lewis has already signalled the broad shape of his plan: cost cuts and, as The Guardian reported, a move to nearly double Guinness production. Diageo’s brands, listed across its Form 20-F, remain among the most recognised in global spirits. The question is whether Lewis can rekindle volume growth in North America, where consumers have been pulling back from premium spirits.
Where Does the Better Opportunity Lie?
BT offers the more predictable near-term setup: a visible cash-generation roadmap, a higher yield, and a cheaper multiple. For income-oriented investors, it is the more straightforward hold while the infrastructure story matures.
Diageo carries more uncertainty but also more recovery optionality. A 50% share-price decline in five years means the bar for positive surprise is considerably lower than it was. If Lewis stabilises North American volumes, the brand equity in names like Johnnie Walker, Guinness, and Don Julio could do the rest of the work. The interim results on 6 August 2026 will be the first proper test of whether that thesis has legs.
 Bitcoin
 Ethereum
 Tether
 BNB
 USDC
 XRP
 Solana
 TRON
 Lido Staked Ether
 Cardano
 Gram (prev. Toncoin)
 Avalanche