
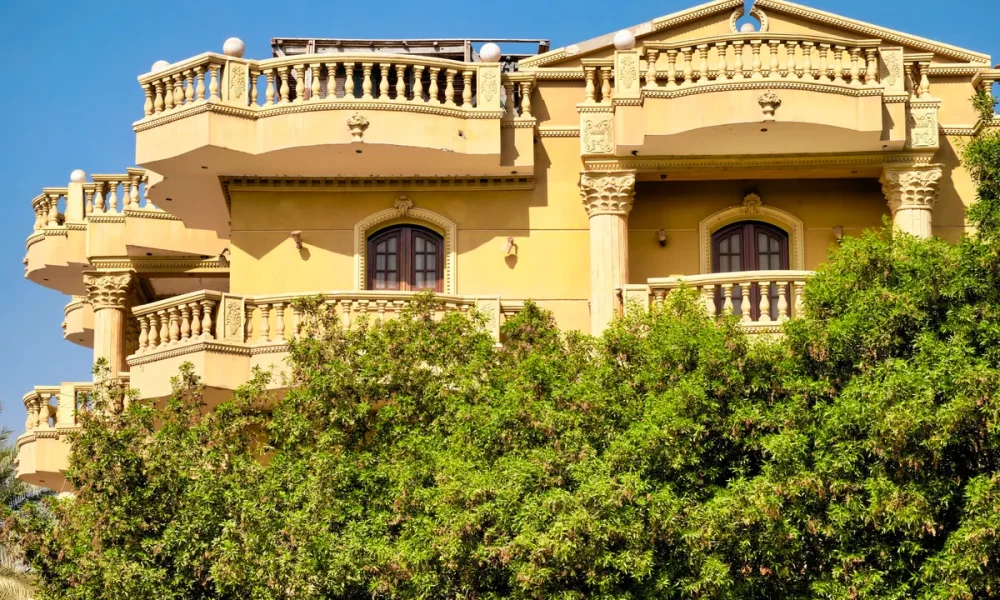
The mansion tax valuation problems surrounding Labour’s High Value Council Tax Surcharge (HVCTS) came into sharper focus this week after reports that the Valuation Office, now part of HMRC, has taken on an extra 493 staff to begin assessing properties that may fall within scope of the new levy.
The surcharge, announced in the November 2025 Autumn Budget, imposes an annual levy on homes in England valued above £2 million. According to BBC News, the charge runs on a four-band sliding scale: £2,500 per year for properties valued between £2 million and £2.5 million, rising to £7,500 for homes at £5 million or above. Eligibility will be determined by a separate valuation exercise using April 2026 market values, with charges collected from April 2028.
The House of Commons Library notes that the OBR estimates around 165,000 properties will be subject to the HVCTS in 2028/29 and 167,000 in 2030/31, before any behavioural responses are factored in. The OBR has itself characterised the costings as carrying a ‘high’ degree of uncertainty.
What Inspectors Will Actually Examine
The Valuation Office says physical inspections will be required where ‘attributes can only be confirmed internally or a re-measurement is required.’ In practice, assessors will examine architectural style, size, and the number of bedrooms, bathrooms and storeys.
One aspect the early coverage has not resolved clearly: how frequently improvements trigger a reassessment. Under the official GOV.UK consultation document, a property’s HVCTS band will not change to reflect improvements alone until the property is sold, split, merged, or a general revaluation takes place. The scenario of a kitchen renovation or a new bathroom prompting an immediate bill is therefore less of a live risk than some commentary has implied. The reassessment question becomes live at the point of sale or at any future general revaluation.
Three Points Where Mansion Tax Valuation Problems Compound
The structural challenges are more stubborn. The OBR has forecast that 20% of HVCTS valuations will be challenged in court, and that 40% of those legal challenges will succeed. Applied to 165,000 in-scope properties, that implies roughly 33,000 contested assessments, of which around 13,200 would be overturned at first instance. The courts, already under sustained pressure, face years of additional property litigation working through the list.
Then there is the price effect. Values in Westminster have fallen 25% and in Kensington and Chelsea by 15%, in part because of the looming surcharge. As properties slide below the £2 million threshold, the number of in-scope homes shrinks further, requiring constant reassessment and feeding additional legal challenges. The OBR itself warned that the incentive to value a property just below the £2 million threshold ‘reduces the estimated yield by reducing the number of properties in scope of the measure.’ The liability threshold will rise in line with inflation, but a shrinking base may outpace that uprating.
On revenue, the projections are already eroding. The OBR estimated the HVCTS would raise £400 million in its first year, rising to £435 million by 2030-31. Against that, it warned that stamp duty, capital gains tax and inheritance tax receipts would fall by £370 million before April 2028 as households sell or downsize in anticipation of the charge. The charge amounts will rise in line with CPI inflation from 2029-30, per The Private Office, but the net yield after displaced receipts is narrow enough that the revenue case rests on behavioural assumptions that the OBR has already flagged as uncertain.
The Administration Cost the Revenue Must Cover
The 493 additional Valuation Office staff represent a permanent addition to the public payroll. If the net yield after displaced tax receipts proves thin, the cost-benefit arithmetic becomes hard to defend. One further structural point: although the HVCTS is collected alongside council tax by local authorities, the revenue flows to central government rather than being retained locally, removing the usual justification that a property-based charge funds local services.
The mansion tax valuation problems may crystallise earlier than April 2028. The valuation exercise using April 2026 market values is already under way, and the first formal challenge to a Valuation Office assessment will be an early signal of how legally robust the framework is. That, rather than the collection date, is the timeline worth watching.
 Bitcoin
 Ethereum
 Tether
 BNB
 USDC
 XRP
 Solana
 TRON
 Lido Staked Ether
 Cardano
 Gram (prev. Toncoin)
 Avalanche