
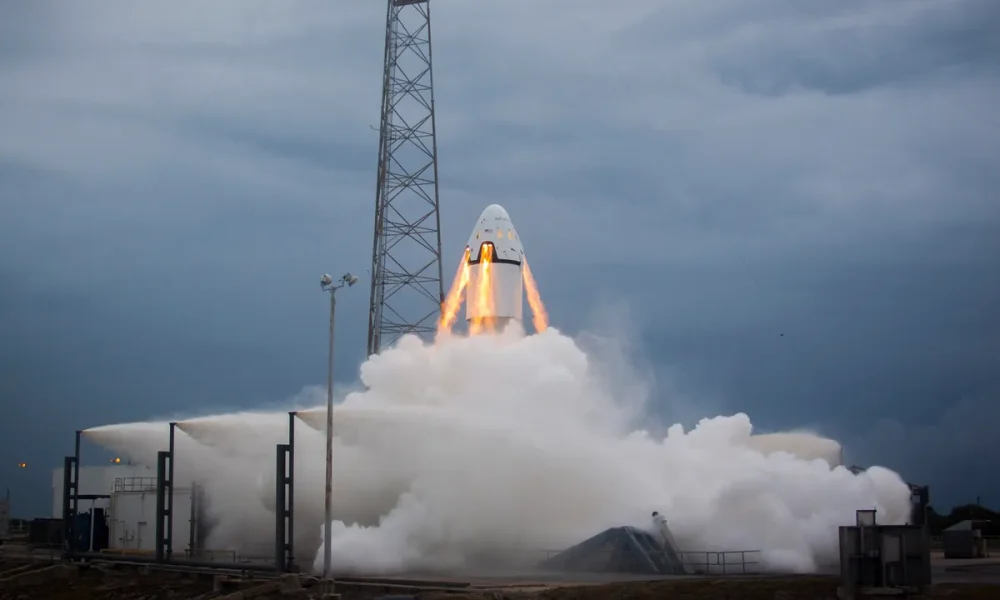
The SpaceX share price valuation has snapped back into debate after SPCX surged 23% over the past month, yet remains more than 30% below the peak it reached shortly after listing earlier this year. For investors weighing whether the recent dip represents a buying opportunity or a warning, the underlying financials offer a more complicated picture than either the bulls or the bears tend to acknowledge.
Revenue growth is real, but so are the losses
The top-line momentum is genuine. On a consolidated basis, SpaceX generated $18.674 billion in revenue in 2025, and for the three months ended 31 March 2026, revenue reached $4.694 billion, representing the 92% year-on-year growth the original filings flagged. Those are figures that would command attention in any sector.
The problem is what sits beneath them. The IPO prospectus financials show a loss from operations of $2.589 billion for the full year 2025, and $1.943 billion for Q1 2026 alone. Adjusted EBITDA was $6.584 billion for 2025 and $1.127 billion for Q1 2026, which suggests the underlying business generates cash before depreciation and stock compensation, but the gap between EBITDA and operating profit is wide enough to matter at this valuation.
The segment breakdown sharpens the concern. The Space division, covering rocket launches, produced only $619 million in revenue for Q1 2026 against a $662 million operating loss in the same period. Launch operations hold roughly 80% of the commercial rocket market by volume, per prospectus disclosures, yet they are not currently profit-generating at the segment level.
The AI drag on SpaceX share price valuation
Starlink is the business carrying the group. With 10.3 million subscribers and over 9,600 satellites deployed as of end-March 2026, it has genuine scale. Its growth has attracted institutional attention and is the core reason the IPO drew the interest it did.
The AI segment, by contrast, recorded an operating loss of $6.4 billion in 2025, with adjusted EBITDA of negative $1.2 billion for the year, according to the Free Writing Prospectus filed with the SEC. That is a substantial drag. The prospectus states that the company intends to use IPO proceeds partly to fund AI compute infrastructure expansion, alongside launch capacity and satellite constellation growth. In June 2026, SpaceX also filed an 8-K announcing a proposed private offering of senior notes, signalling that external capital markets remain part of the funding mix even after the listing.
Whether the AI spending translates into proprietary competitive advantage or simply inflates the cost base is the central question investors cannot yet answer from the available data. The prospectus sets out the intent; it does not guarantee the return.
One further structural point from the S-1 filing: the company operates a dual-class share structure designed to keep Elon Musk in control after the offering. For investors assessing governance risk alongside financial risk, that is a live consideration, not a technicality.
Where the thesis stands
The optimistic case is straightforward to sketch. Starlink’s subscriber base is growing, launch market share is entrenched, and if AI infrastructure spending yields proprietary returns, the current losses could look like investment-phase costs rather than structural weakness. On that reading, the post-IPO pullback from the high might represent an entry point.
The sceptical case is equally coherent. A business posting a $1.943 billion operating loss in a single quarter, with an AI segment that lost $6.4 billion at the operating line in 2025, requires either a very long time horizon or a very high conviction in management’s capital allocation. Geopolitical exposure through Starlink’s use in active conflict zones adds a dimension that conventional valuation models do not readily capture. Competition across launch, broadband, and AI is intensifying.
The 23% monthly move tells you something about how fractured market opinion is. The next test is whether Q2 2026 results, due under the June 30 reporting period, show any narrowing of the operational loss at the segment level. If the Space and AI divisions remain in deep deficit while Starlink absorbs the capital burden, the margin-of-safety argument for the current price becomes harder to sustain.
 Bitcoin
 Ethereum
 Tether
 BNB
 USDC
 XRP
 Solana
 TRON
 Lido Staked Ether
 Cardano
 Gram (prev. Toncoin)
 Avalanche