
Contributed content: this article was written by a third-party contributor and does not necessarily reflect the views of ABC Money. Editorial and Advertising Policy
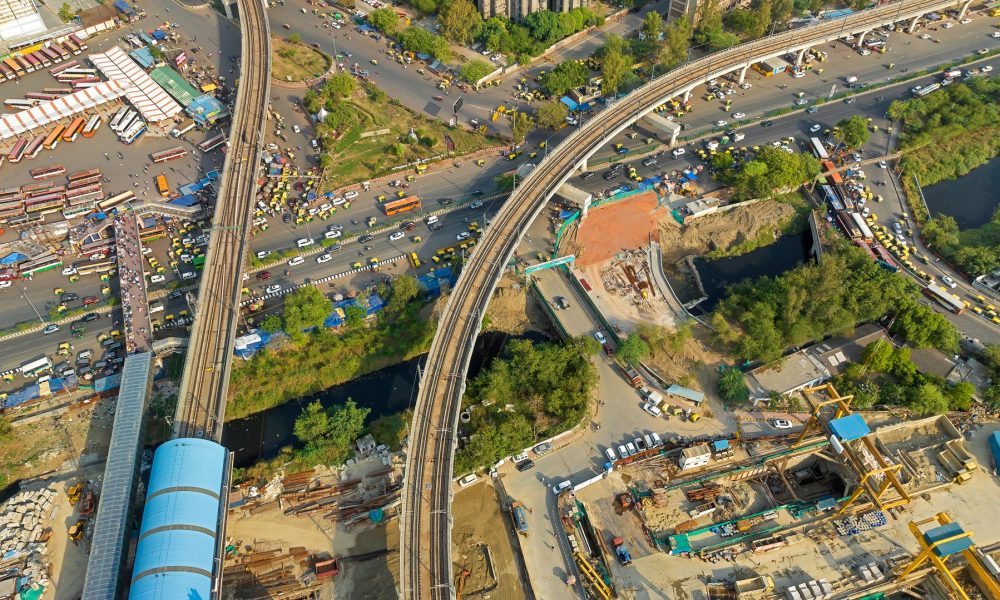
India has just hosted the annual BRICS summit in New Delhi, one of the most important and successful in recent years for the group of 11 emerging economies. Alongside the usual focus on geopolitics and diplomacy, the group agreed measures on infrastructure finance that deserve investors’ attention.
The question tackled in New Delhi was how to make infrastructure development cheaper to finance for global investors – the billion-dollar question for BRICS nations. Government spending alone cannot provide the capital needed to industrialise at pace, so the challenge is how to de-risk major projects enough to attract the global capital that is ready to invest.
Rupin Banker, founder of Royal Fort Infracom, an infrastructure and supply chain finance firm in the Middle East, framed the problem in the same way. “Asia does not have a shortage of infrastructure ambition, and there’s no shortage of global finance appetite. The challenge is building the bridge between the two,” he told The European Business Review in August. The New Delhi summit aims to build that bridge by changing how risk is priced and shared.
The return investors want on an emerging-market infrastructure deal reflects the level of risk largely outside their control. That includes everything from regulatory change and late-paying public counterparties to construction overruns and a weakening local currency. This month’s summit measures are aimed squarely at them.
The most significant measure is the BRICS Multilateral Guarantees initiative being developed within the New Development Bank (NDB). BRIC leaders recognised its potential to mobilise private capital, improve creditworthiness and reduce financing costs. A well-targeted guarantee can turn a project reliant on short, expensive debt into one that pension funds and insurers will hold for 15 or 20 years.
The Declaration also encouraged the NDB, which had approved 141 projects worth about $44 billion by the end of June, to expand its local-currency lending towards its target of 30 per cent. For a toll road or power utility earning revenue in rupees, reais or rand, borrowing in dollars creates a mismatch that hedging only partly solves.
BRICS also welcomed a technical report on public-private partnership models and de-risking, while finance ministers called for best practice on risk allocation, which matters because risk left with the wrong party is always priced in somewhere.
India is already taking a similar approach at home, raising public capital spending to ₹12.2 trillion in its 2026-27 budget, creating an Infrastructure Risk Guarantee Fund for private developers and publishing a pipeline of 852 PPP projects worth more than ₹17 trillion. Finance minister Nirmala Sitharaman told a BRICS seminar in Jaipur in August that “public capital must act as a catalyst, not a substitute, for private investment”, and Anuradha Thakur, secretary of India’s Department of Economic Affairs, said “capital mobilisation must be anchored in frameworks that endure.”
For investors in the West already thinking in decades, the direction of travel from New Delhi looks constructive, but the real test will be whether the first guarantee pilots are properly chosen and priced. A communiqué will not finance a single project, but it’s a signal of intent – and an important one at that.
 Bitcoin
 Ethereum
 Tether
 BNB
 USDC
 XRP
 Solana
 TRON
 Lido Staked Ether
 Cardano
 Gram (prev. Toncoin)
 Avalanche