
US stocks pushed toward record territory on Friday as a much weaker-than-expected September jobs report chilled bets on further Federal Reserve interest-rate rises — a weak jobs report rally that carried Nvidia (NASDAQ: NVDA) to a fresh all-time high and lifted the Nasdaq 100 to a record close, according to Benzinga.
Nonfarm payrolls rose by just 29,000, against forecasts of roughly 84,000 to 90,000, while the unemployment rate ticked up to 4.2% from 4.1%, Benzinga reported. The Federal Reserve Bank of St Louis’s own tracking series puts the most recently confirmed unemployment reading at 4.1% for August, unchanged on the month before (FRED) — a reminder that headline payrolls figures typically land well ahead of their formal statistical confirmation, rather than any challenge to the September print itself.
The market reaction was immediate. Nvidia touched a record $237.88 a share, the Nasdaq 100 gained 1.1% to 30,825, the S&P 500 added 0.6% to 7,714 and the Dow Jones Industrial Average rose 0.3%, or about 137 points, to 51,066, Benzinga’s market wrap showed. Traders also pared the odds of an October Fed rate increase to just 17%, the same report said, as a soft labour market made the case for further tightening harder to sustain.
Benzinga’s account described Treasury yields as having “tumbled” on the data. The most recent prints in the Federal Reserve Bank of St Louis’s database complicate that framing: the 10-year Treasury yield rose to 5.29% on 30 September from 5.26% the previous session (FRED), while the gap between 10-year and 2-year yields — a widely watched measure of how steep the yield curve is — widened to 0.46 percentage points from 0.41 points by 1 October (FRED). Both readings predate Friday’s jobs release, so they don’t resolve what happened on the day itself, but they show long-dated borrowing costs drifting higher, not lower, in the run-up to the report that supposedly sent them tumbling.
Why the weak jobs report rally skipped Accenture
Not every corner of Friday’s narrative holds together as neatly. Investor’s Business Daily ran a Friday headline declaring “Accenture Rockets, Lifts This Group,” casting Accenture plc (NYSE: ACN) as a standard-bearer for IT-services stocks riding the same updraft as the chip names.
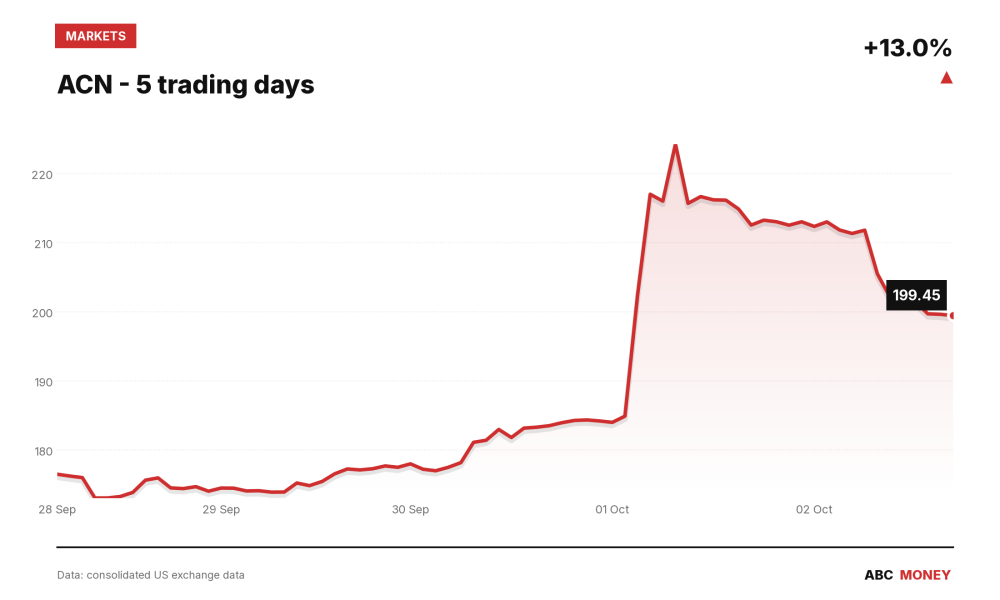
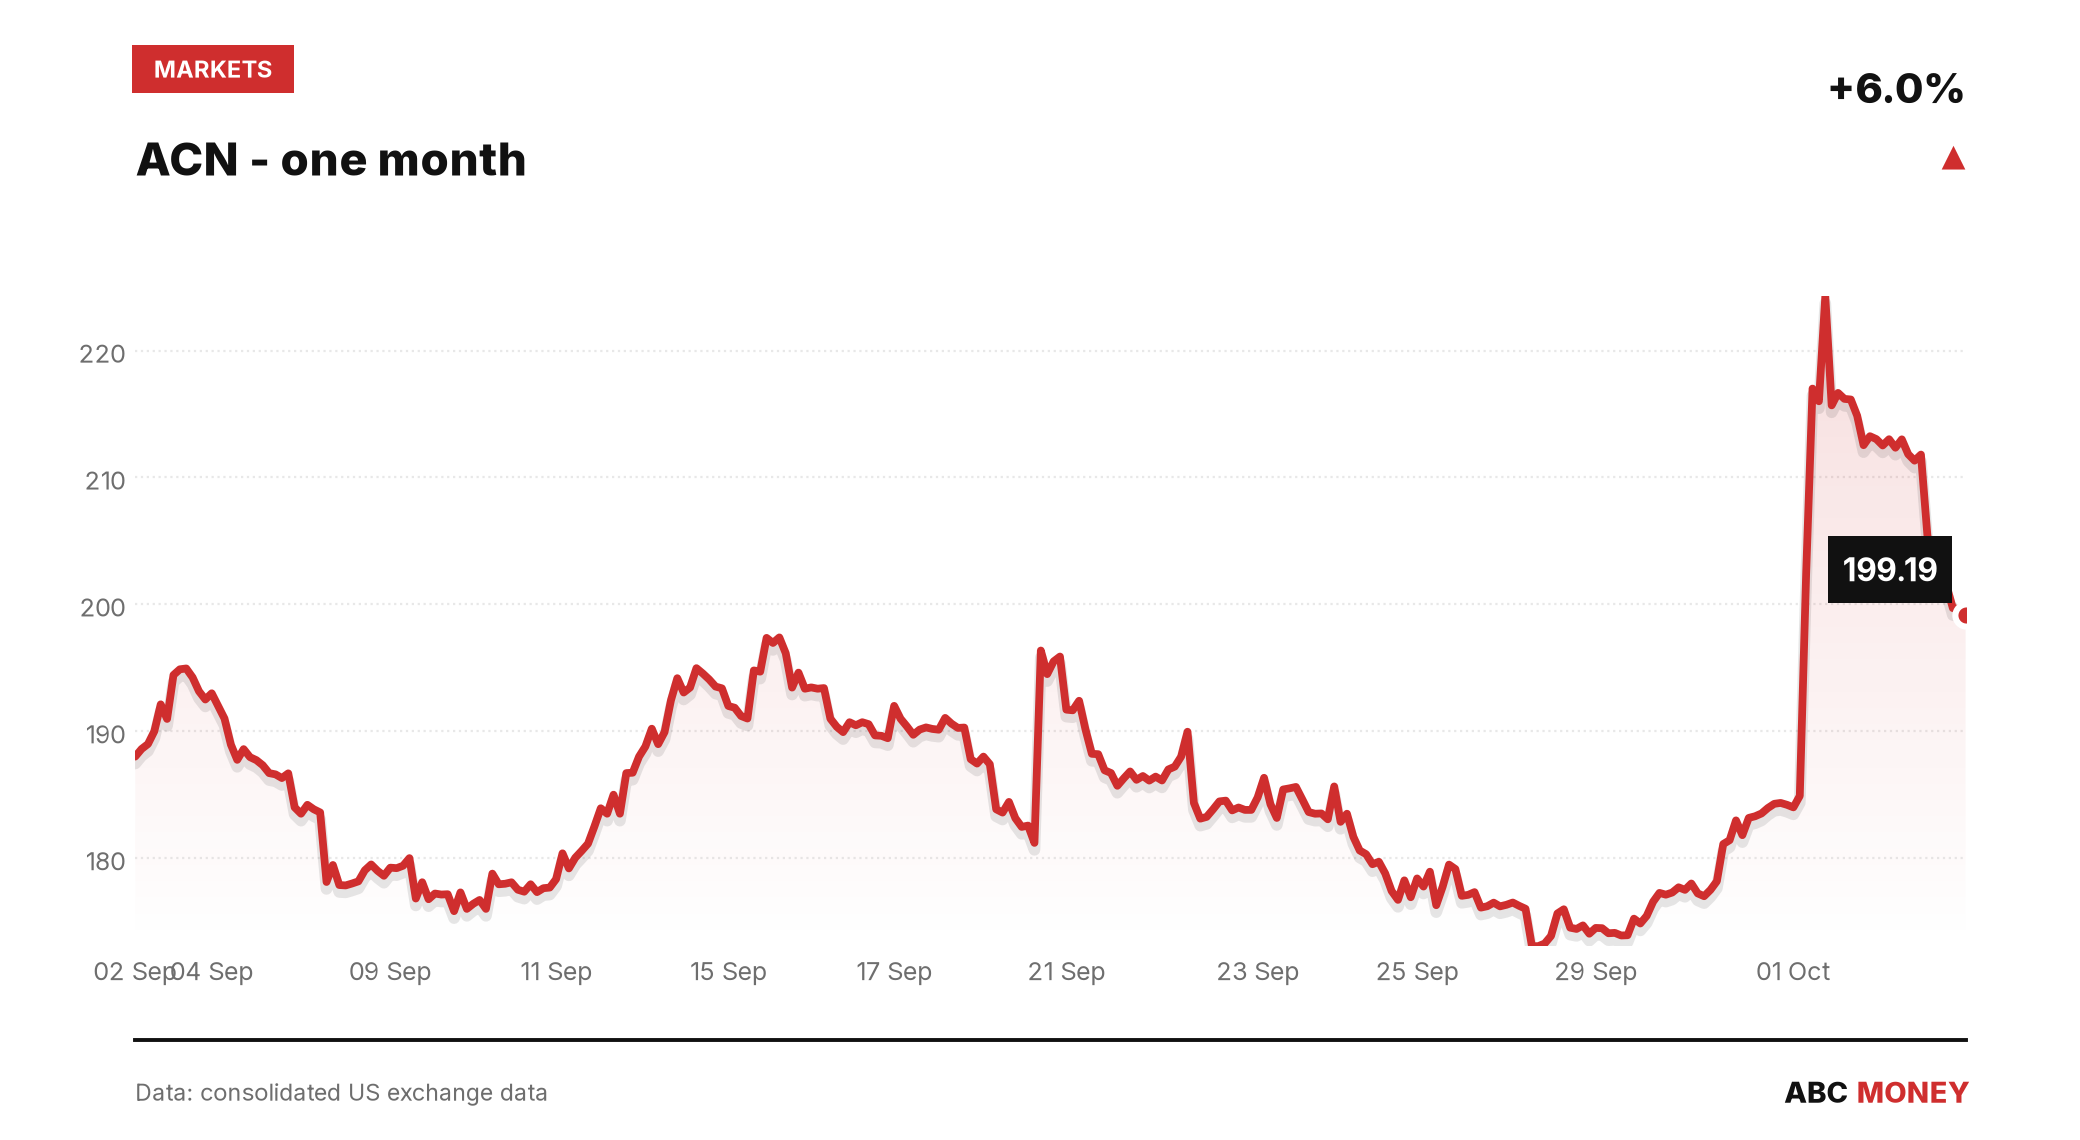
The tape told a different story. As that piece was circulating, Accenture shares were down 5.49% over the prior 24 hours to $200.165, on volume 1.83 times the stock’s 20-day average, and sitting well below the $224.265 high it had touched in the preceding month. That’s despite a 9.08% gain over the full 20-day stretch — a stock that had been running hot into the print and then gave a chunk of it back, rather than one catching a fresh lift from the broader rally.
Positioning data point the same way. The proportion of Accenture’s daily trading volume tied to short sales — bets that the shares would fall, settled by buying the stock back later — climbed to 53.1% on 1 October from 29.4% a week earlier, according to FINRA’s daily short-sale data. That build-up looks more consistent with traders positioning defensively ahead of the jobs report than with a stock about to break out.
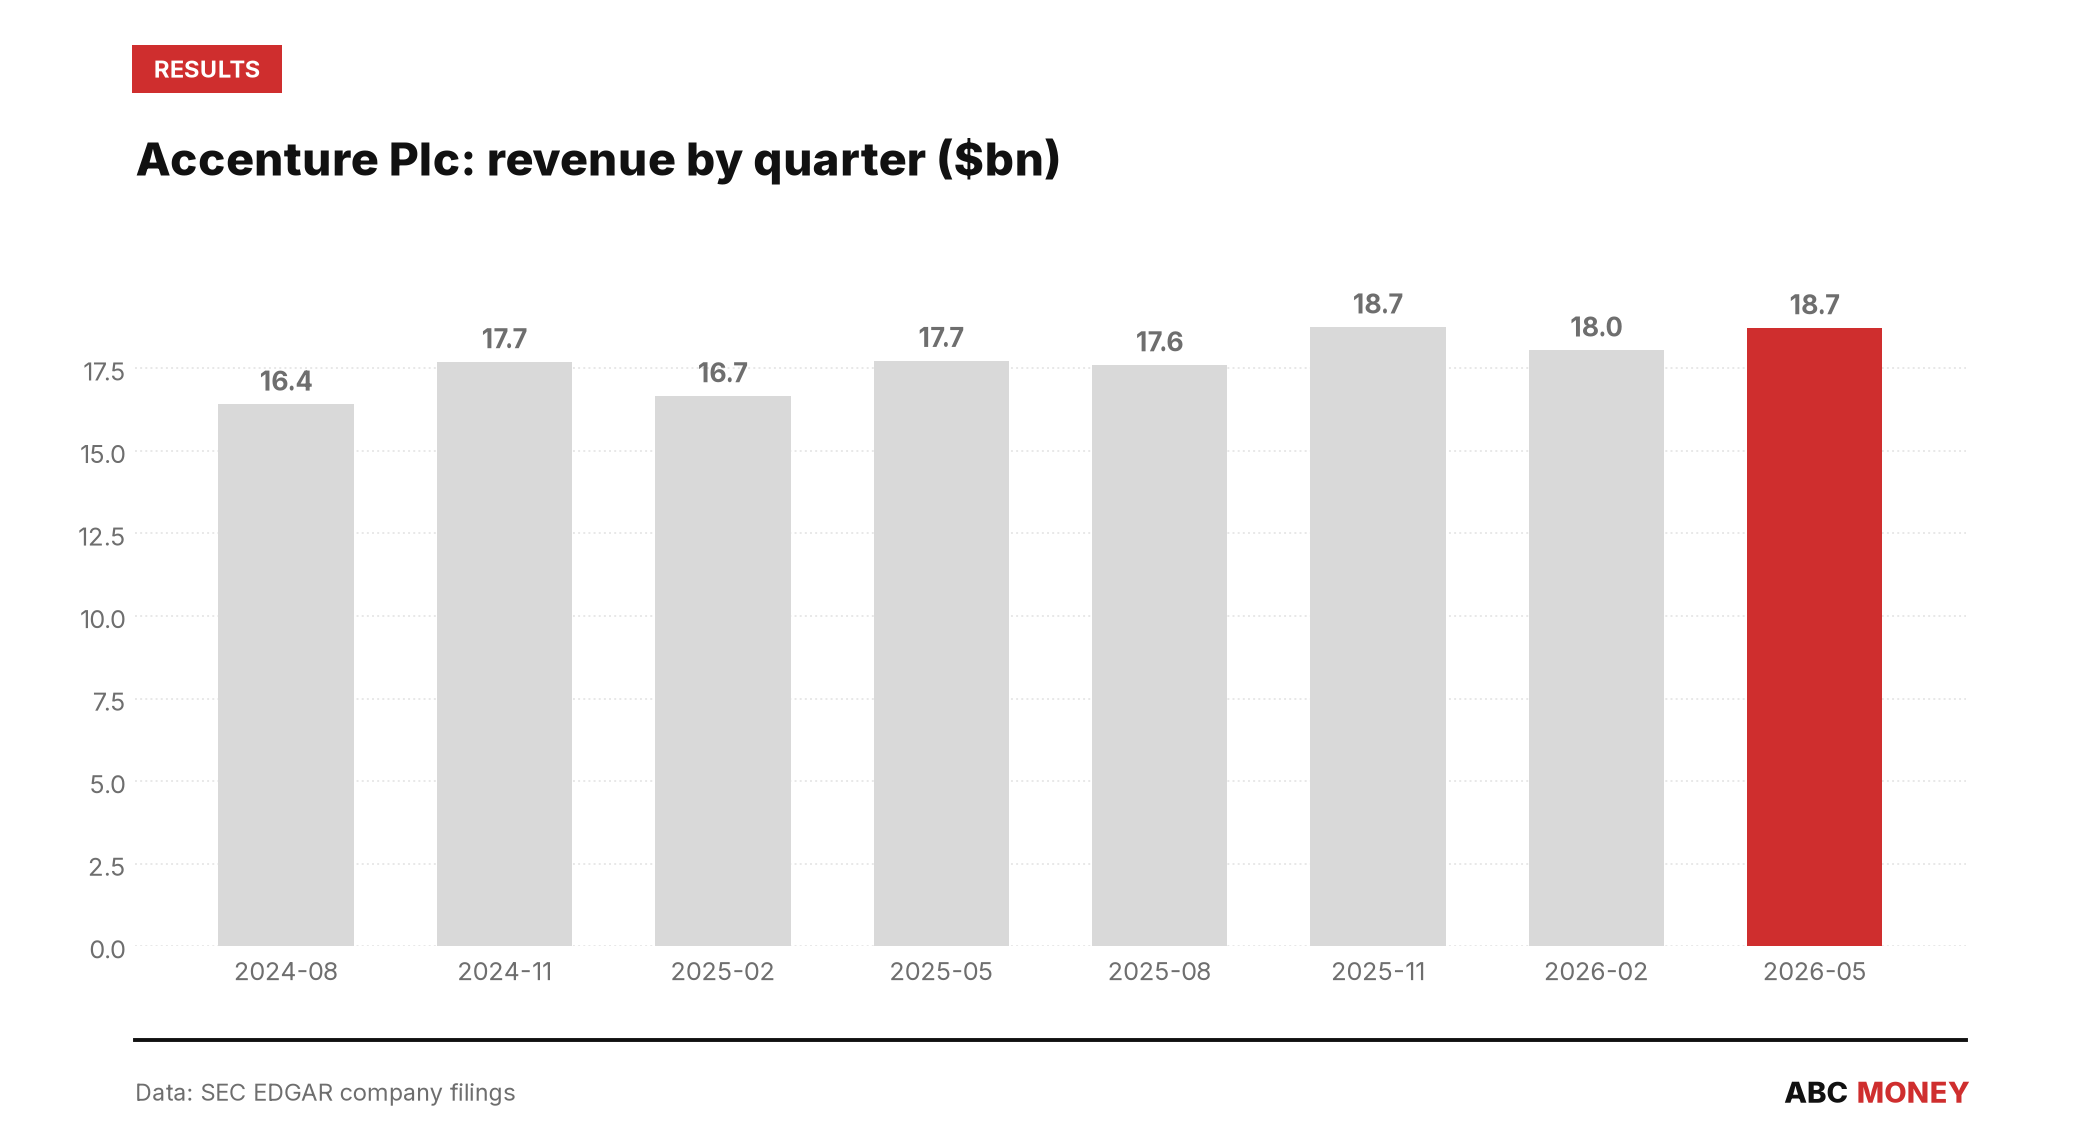
None of this reflects weakness in the underlying business. Accenture’s revenue for the quarter ended 31 May 2026 came in at $18.72bn, with diluted earnings per share of $3.80, both ahead of the $17.73bn and $3.49 reported in the same quarter a year earlier, filings with the Securities and Exchange Commission show. The disconnect on Friday was between the share price and the macro story being told about it, not between the company’s results and expectations.
A rally with uneven footing
Taken together, the session captured something true about markets in moments like this: a single data point can move an index and a mega-cap chip stock in the same direction while leaving individual names — even ones with solid underlying numbers — moving the opposite way. Benzinga’s companion report also flagged Western Digital as a notable decliner even as the broader tape rallied, underscoring that Friday’s gains were concentrated rather than uniform.
With Fed-hike odds for the October meeting down to 17% on the jobs data, according to Benzinga, the next scheduled payrolls release and any revisions to September’s figures are likely to carry outsized weight for how durable this repricing proves to be — and for whether stocks such as Accenture, still trading well off their recent high, find their own footing or keep lagging the names at the centre of the rally.
This article is for information only and is not investment advice or a recommendation to buy or sell any asset. Markets move quickly; figures are correct as sourced at the time of writing. Always do your own research before making financial decisions.

 Bitcoin
 Ethereum
 Tether
 BNB
 USDC
 XRP
 Solana
 TRON
 Lido Staked Ether
 Cardano
 Gram (prev. Toncoin)
 Avalanche