
How Aarion Capital Is Using Volatility, Technology and Risk Discipline to Navigate Modern Markets
Contributed content: this article was written by a third-party contributor and does not necessarily reflect the views of ABC Money. Editorial and Advertising Policy
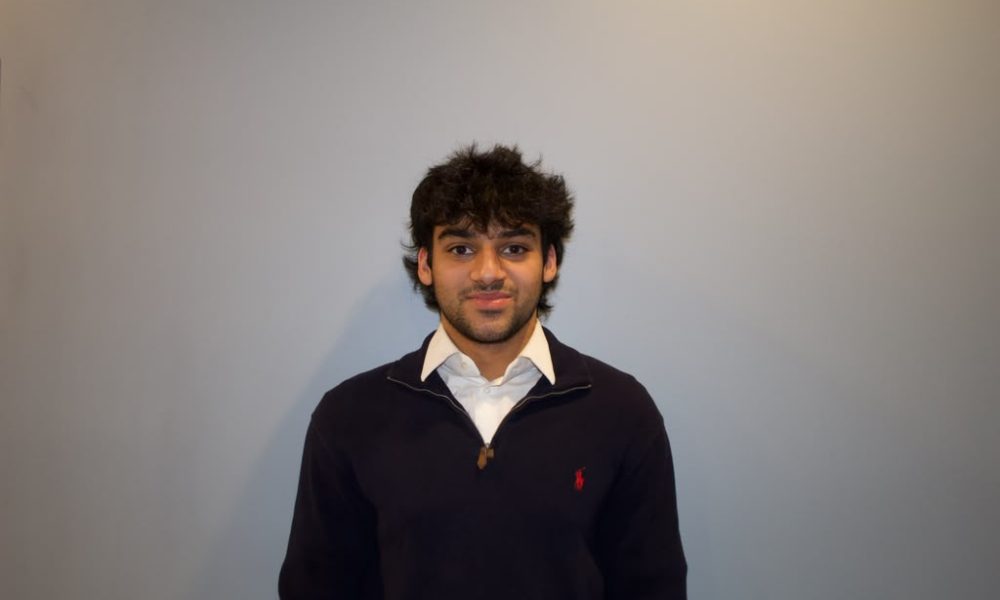
Aarion Capital Founder and CIO Aarush Garg believes modern investment firms need to combine faster research and technology with something much older: disciplined judgment.
Financial markets have become faster, more interconnected, and increasingly difficult to interpret.
Real-time news moves prices in seconds. Algorithms react before many investors have finished reading a headline. Options activity can influence underlying equities through hedging flows. Social media spreads useful information and misinformation at the same speed, while artificial intelligence is accelerating the amount of data investors can process.
For Aarush Garg, Founder and Chief Investment Officer of Aarion Capital LP, the answer is not to attempt to predict every market move.
It is to build a repeatable process for responding to uncertainty.
Aarion Capital is a New York-based multi-asset investment firm operating across equities, fixed income, commodities, options, and derivatives. Its strategy incorporates global macro and event-driven analysis, with a particular focus on identifying market dislocations while maintaining portfolio-level risk controls.
At the center of Garg’s philosophy is a relatively simple principle: opportunity should not come at the expense of capital discipline.
"Capital preservation means protecting investor capital before pursuing return," Garg says. "Growth should not come from uncontrolled risk."
That philosophy shapes how Aarion approaches volatility, derivatives, portfolio construction, technology, and investment research.
Why Volatility Matters
Garg’s interest in markets began as a teenager, when a sharp late-day move in a SPY options contract sparked his fascination with how quickly expectations can change. Some of the more lasting lessons, however, came from trades that went wrong.
One event-driven Astra position became a particularly useful risk-management lesson. The trade initially benefited from volatility surrounding a rocket launch, but when the launch failed, the position moved sharply against him as liquidity deteriorated. The experience reinforced a principle that later became central to Aarion’s process: conviction in an idea does not make the outcome certain.
Risk has to be addressed before a trade is placed, not after it begins moving in the wrong direction. Today, Aarion establishes position-sizing limits and broader portfolio risk parameters before deploying capital.
"Volatility isn’t something we fear because fear usually comes from not knowing how to manage and hedge against it," Garg says.
For Aarion, volatility is not automatically bullish or bearish.
It is information.
Rapid repricing can reveal changes in expectations, temporary dislocations, hedging pressure, liquidity conditions, or shifts in how the market is interpreting a catalyst. That creates potential opportunities, but only if those opportunities fit within the firm’s predefined risk framework.
Knowing When Not to Trade
One of Garg’s most important investing principles is also one of the least dramatic.
Sometimes the right trade is no trade at all.
Aarion’s team may decide not to deploy capital when a thesis has not been sufficiently developed, when the expected reward does not justify the exposure, or when an opportunity falls outside established risk parameters.
"The best investment decision is sometimes the one you don’t take," Garg says.
The idea runs counter to the constant-activity mentality that can develop in modern markets. With financial news, social media, options markets, and brokerage platforms available almost continuously, investors can feel pressured to react to every development.
Garg believes discipline includes resisting that pressure. Access to more information does not necessarily create better decisions. In some cases, it creates more noise.
Options, Hedging Flows and Modern Market Structure
Garg sees several forces changing market behavior simultaneously. Artificial intelligence has accelerated research, algorithmic trading has increased the speed of reactions, social platforms have created new channels for information and speculation, and retail participation has introduced additional behavioral forces.
Options markets are another part of that shift. Short-dated and zero-day options can concentrate leverage into very small windows of time, while dealer hedging associated with options positions can add another layer to how underlying securities respond to catalysts and changing market conditions.
Garg believes derivatives increasingly need to be considered alongside the equities or other assets they reference. Options positioning, implied volatility, leverage, liquidity and associated hedging flows can all affect the way a security trades around an earnings release, macroeconomic announcement, geopolitical event, or other catalyst.
That does not mean derivatives explain every move. It means the underlying security may be only one part of the market structure surrounding a trade. For Aarion, understanding that structure is part of evaluating whether volatility represents opportunity, a warning sign, or simply noise.
Global capital flows add another layer of complexity. A development in one market can transmit quickly through rates, currencies, commodities, equities, and derivatives, making isolated analysis less useful when conditions are changing rapidly.
"The barrier to entry is close to none," Garg says of modern markets.
That democratization creates opportunities for individuals and smaller organizations that once lacked access to institutional-grade information. But Garg believes information access can easily be mistaken for expertise.
A trader may have access to the same headline as a professional institution without having the same framework for evaluating its importance, portfolio implications, liquidity risk, or potential second-order effects. For Aarion, the goal is therefore not simply to consume information faster. It is to structure that information in a way that supports better decisions.
Building VAL
A central part of that effort is an internally developed system called VAL (Volatility Analytics and Logistics).
VAL is designed to analyze market conditions and portfolio exposures, map sectors against catalysts and upcoming events, process research, and synthesize market and portfolio information into analytical outputs.
Inputs can include market conditions, portfolio data, company and sector research, upcoming catalysts, internal reports, and analysis produced by the Aarion team.
The system is intended to help the team compare information across sectors, portfolio exposures, catalysts, and internal research so that relationships or potential risks that may not be obvious in isolation can receive further human analysis. In that sense, VAL is less a generic AI summarizer than an internal decision-support layer for organizing how different pieces of the investment process interact.
It does not make the final decision.
Garg is particularly cautious about the idea that artificial intelligence should independently determine portfolio allocations.
"AI is useful when it directly helps you make better-informed decisions," he says.
His concern begins when AI is treated as if it can predict markets with certainty. Models operate using data, assumptions, and inputs that can be incomplete. Unexpected geopolitical events, shifts in liquidity, policy decisions, or market behavior can quickly undermine a previously reasonable scenario.
That is why VAL functions as decision support. Outputs are reviewed by the team, while final portfolio decisions remain with Garg as CIO.
Technology Without Surrendering Judgment
The distinction reflects Garg’s broader view of the future of investment management. He expects investment firms to become increasingly technology-enabled, but not less accountable.
AI can summarize research, compare scenarios, analyze exposures, map catalysts, structure large datasets, and help teams organize information more efficiently. Quantitative analysis can make investment research more repeatable.
None of that, Garg argues, removes responsibility from the people making the investment decision.
"AI should support rather than replace judgment because models can be wrong or incomplete and responsibility for investor capital should remain human," he says.
That principle also influences how Aarion structures its internal research. Investment ideas can originate throughout the team and move through deeper analysis, risk assessment, position sizing, portfolio consideration, monitoring, and eventual adjustment or exit.
Human judgment sits throughout that chain.
Building a Repeatable Investment Process
For Garg, one of Aarion’s most important developments has been documenting how decisions are made. The firm maintains strategy logs, internal research, records of investment decisions, and information about how strategies change over time.
The aim is to create what Garg considers intellectual infrastructure. Instead of only reviewing a portfolio’s outcome, the firm wants to preserve the thinking behind it: why a position was entered, what assumptions supported the thesis, what changed, and which assumptions proved correct or incorrect.
That allows future decisions to be informed by previous ones.
Garg began developing this mentality before launching Aarion, maintaining datasets around his own trading history and studying why certain decisions succeeded while others failed. He also worked with mentors with prior professional experience at financial institutions including Schwab and Morgan Stanley, alongside independent advisors who broadened his exposure to markets and financial technology.
Over time, the objective shifted from simply finding trades to building a process capable of improving.
A Firm Designed Around Risk
Aarion’s investment process combines return-seeking strategies with risk controls at both the position and portfolio level.
The firm’s portfolio can include concentrated equity positions, income-oriented fixed-income investments, commodities used partly for hedging, and options and volatility strategies. The broader objective is to pursue long-term growth in net asset value while managing portfolio-level risk.
That portfolio-level view matters because the risk of an individual position is not considered only in isolation. The team also evaluates how an exposure fits alongside existing positions, broader market conditions, upcoming catalysts, and the possibility that several seemingly different risks may be linked by the same macroeconomic or market driver.
Aarion incorporates macroeconomic and event-driven analysis when identifying potential market dislocations. Catalysts can include central-bank policy, inflation data, economic releases, geopolitics, energy and commodities, company-specific events, market positioning, and real-time news.
For Garg, those factors cannot be viewed separately. A geopolitical development can affect energy. Energy can affect inflation. Inflation can influence central-bank expectations. Rate expectations can affect currencies, equities, bonds, and capital flows.
That is why Aarion’s research process attempts to combine individual-security analysis with a broader understanding of the macro environment, derivatives positioning, portfolio exposure, and the catalysts that could change those relationships.
From Trading to Institution Building
Garg says his own role has evolved from primarily focusing on individual investment decisions to spending more time on strategy development, systems, technology, reporting, people, and the processes required to execute the firm’s investment philosophy consistently.
"My role today is no longer simply about finding the next trade," Garg says. "It is about continuing to develop the strategy, building processes around it, and creating an organization capable of executing and improving that approach over time."
Research and portfolio recommendations increasingly come from members of the Aarion team, with Garg retaining final investment authority. He views that delegation as part of building a process that can scale without becoming overly dependent on a single person.
The Next Phase
Aarion Capital was founded in August 2025 and officially began operating in January 2026. Since then, the firm has focused heavily on developing its research infrastructure, internal technology, investment processes, team, investor reporting, and broader operational capabilities.
The firm intends to continue growing its investment book and relationships while further developing VAL and giving members of its team greater responsibility.
Garg ultimately wants Aarion to become a significantly larger and internationally recognized investment organization.
Yet his philosophy around growth closely resembles his philosophy around investing.
Scale should follow preparation.
Opportunity should be weighed against risk.
Technology should improve judgment rather than replace it.
And more activity is not always better activity.
In financial markets increasingly defined by speed, automation, and information overload, Garg believes discipline may become more important rather than less.
For Aarion Capital, that means continuing to develop the systems behind each investment decision, even when the best decision is to do nothing at all.
To learn more about Aarion Capital and its investment approach, visit aarioncapital.com.
 Bitcoin
 Ethereum
 Tether
 BNB
 USDC
 XRP
 Solana
 TRON
 Lido Staked Ether
 Cardano
 Gram (prev. Toncoin)
 Avalanche