Bitcoin
 Ethereum
 Tether
 BNB
 USDC
 XRP
 Solana
 TRON
 Lido Staked Ether
 Cardano
 Gram (prev. Toncoin)
 Avalanche
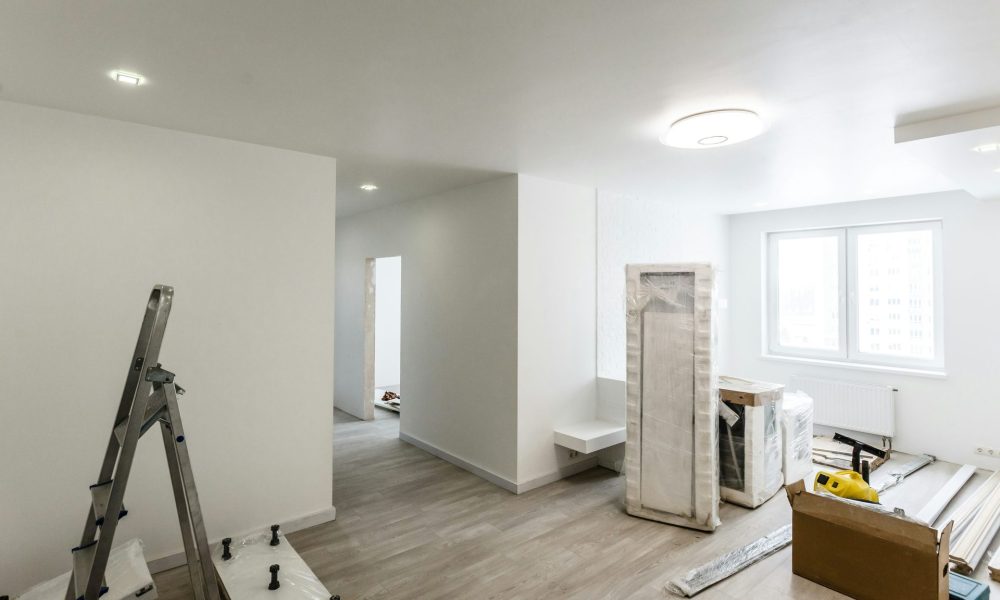
Whether you’re looking to knock down walls for a modern kitchen extension, convert a dusty loft into a home office, or drag a dated fixer-upper into the modern era, home improvements are a massive trend.
But unless you have a giant chest of cash sitting under your mattress, you’re going to need to figure out how to pay for it. In the 2026 credit market, lenders are keeping a close eye on affordability, but there are still plenty of ways to secure the funds.
Choosing the right path depends entirely on the size of your project and how much equity you have locked in your bricks and mortar. Here are four of the most effective ways to fund your property transformation.
1. The Standard Remortgage (Capital Release)
For big-ticket transformations – like a full double-story extension or a complete structural overhaul – remortgaging is usually the most cost-effective play.
This process involves replacing your current mortgage deal with a larger one, allowing you to pull out the cash difference to pay your builders. For example, if your home is worth £400,000 and your mortgage is £200,000, you might remortgage up to £260,000 to free up £60,000 for the works.
In plain English:
- The Perk: You get access to standard mortgage interest rates, which are significantly lower than personal loans.
- The Catch: You are spreading the cost over the full length of your mortgage (often 20 to 25 years), meaning you’ll pay more interest in the long run. You also need to watch out for Early Repayment Charges (ERCs) if you break your current fixed rate early.
2. A Further Advance
If you have a spectacular interest rate on your current mortgage and don’t want to lose it by remortgaging the whole balance, a Further Advance is the perfect middle ground.
This is where you go to your existing lender and ask to borrow extra money as a separate “chunk” on top of your main loan. The bank treats this as a separate mini-mortgage, often with its own interest rate and term, meaning your original main deal stays completely untouched.
The Strategy: It’s a brilliant option if you are midway through a 5-year fixed deal. The application process is generally quicker than a full remortgage, and you bypass those nasty early exit penalties.
3. Unsecured Personal Loans
If your project is more cosmetic – think a new kitchen refit, a landscaping project, or redoing a couple of bathrooms – a personal loan is often the cleanest route.
In 2026, high-street lenders offer unsecured home improvement loans up to £25,000, and sometimes up to £50,000 for borrowers with top-tier credit scores. The money lands directly in your bank account, often within a few days.
- The Pros: There are no legal fees, no property valuations required, and the payments are fixed over a short term (typically 1 to 7 years). Crucially, the loan isn’t secured against your house, making it far less risky.
- The Cons: The interest rates are higher than a mortgage, meaning your monthly repayments will be meatier.
4. 0% Money Transfer Cards
This is a slightly cheeky, insider financial tactic for smaller projects under £10,000. While a standard 0% purchase credit card is great, many builders and plumbers won’t accept credit card payments—they want a bank transfer or cold cash.
A 0% Money Transfer Card allows you to move cash from the card straight into your current account. You pay a small one-off transfer fee (usually around 3% to 4%), but you then get an interest-free window—sometimes up to 12 or 18 months—to pay that cash balance off.
The Risk: If you don’t clear the balance before the 0% promotional period ends, the interest rate will skyrocket. It requires military-grade financial discipline.
The “Value” Test
Before you sign on the dotted line for any form of finance, run your project through a basic reality check.
Are you spending £40,000 on a garage conversion that will only add £15,000 to the value of the house? If you plan to live in the property for the next twenty years, that “overspend” might be worth it for your lifestyle. But if you’re planning to sell up in a few years, you could find yourself out of pocket.
The Verdict
For small, fast projects, keep it simple with a personal loan or a 0% card. For major structural changes that require serious capital, speak to a broker about releasing equity via your mortgage.