
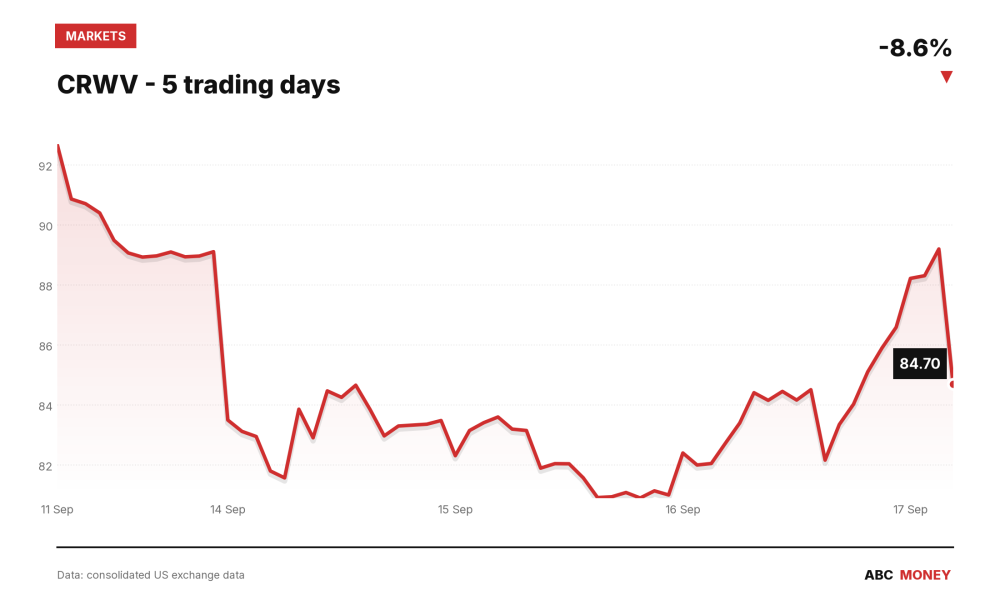
CoreWeave (Nasdaq: CRWV) has launched a proposed $3.0 billion convertible notes offering, its third large debt raise in under a year, as the AI cloud-computing firm keeps tapping credit markets to fund a build-out that is still burning cash by the hundreds of millions each quarter.
The company said on 17 September that it intends to sell $3.0 billion of convertible senior notes due 2033 – bonds that pay a coupon but can be exchanged for CoreWeave shares later, letting the company borrow more cheaply now in return for handing bondholders potential upside (and existing shareholders potential dilution, the reduction in their proportional ownership) if the stock rises far enough. The notes are being offered privately to qualified institutional buyers under Rule 144A, a standard exemption that lets large, sophisticated investors trade unregistered securities among themselves without a public prospectus.
CoreWeave is also giving the banks running the sale, known as initial purchasers, an option to buy up to an additional $500 million of notes, exercisable within a 13-day window from first issuance – the kind of over-allotment mechanism that typically signals demand the company hopes will exceed the headline size. The terms, maturity date and guarantee structure were confirmed in the company’s own filing with the SEC.
A now-familiar rhythm of upsized raises
This is not CoreWeave’s first trip to the convertible market this year, and the pattern is worth noting. In December 2025 the company priced an upsized $2.25 billion of 1.75% convertible notes due 2031, having originally proposed $2.0 billion. In April 2026 it went back again, pricing an upsized $3.5 billion of notes due 2032 after initially floating $3.0 billion. If September’s deal follows the same script, the final print could land above the $3.0 billion headline figure, though nothing has been priced yet.
The new notes will sit alongside a stack of existing debt – CoreWeave’s 9.250% senior notes due 2030, 9.000% and 9.750% notes due 2031, 9.625% and 8.500% notes due 2032, and the 1.75% convertibles due 2031 and 2032 – all guaranteed by the same group of subsidiaries, according to reporting from Futu News. That coupon range, mostly in the high single digits, is one reason convertibles look more attractive to a company still scaling: swapping a cash coupon for a conversion option can lower the interest bill, provided investors believe the equity story.
Losses widen as revenue scales past $2.5bn
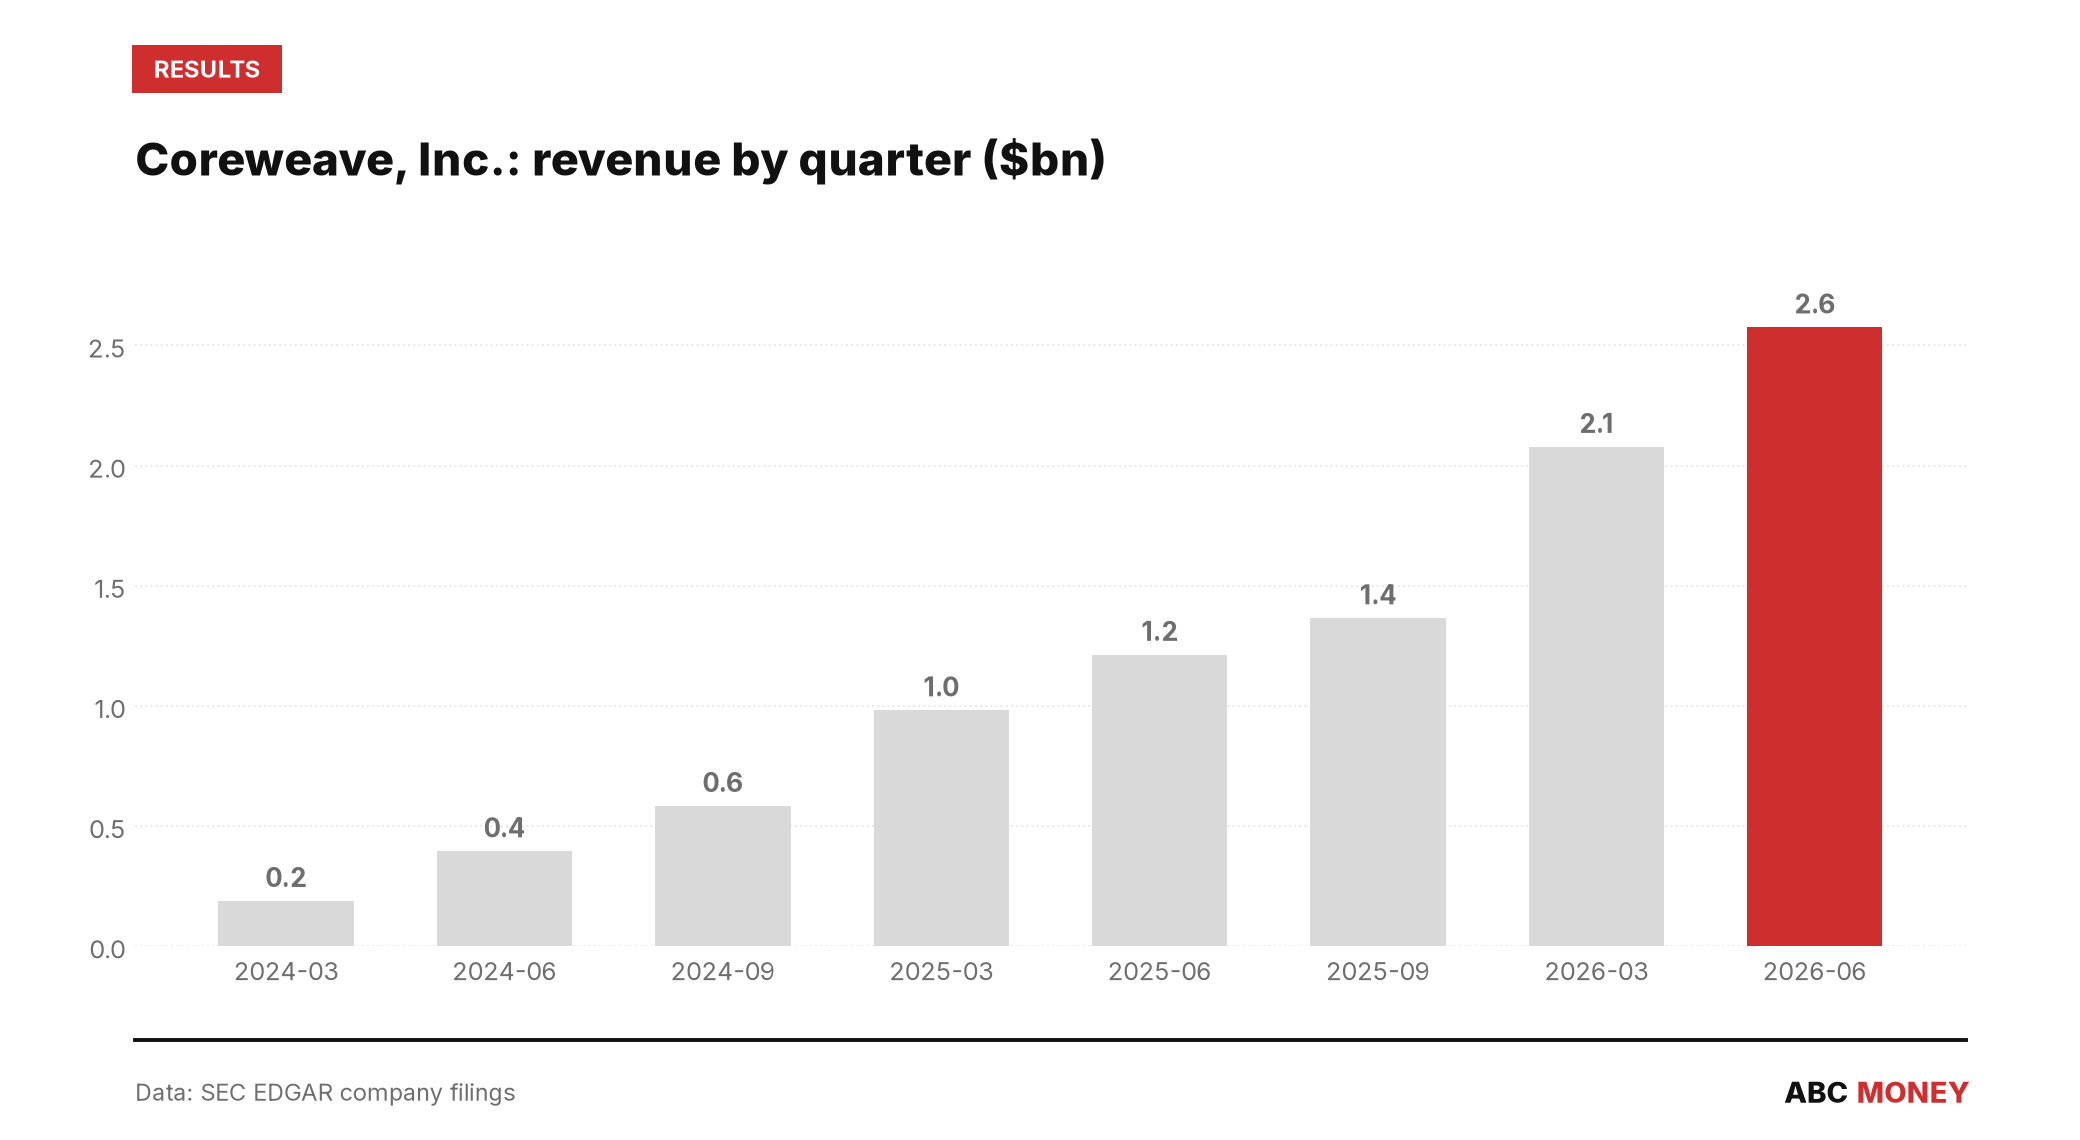
The borrowing keeps funding growth that remains unprofitable at the bottom line. CoreWeave’s quarterly revenue rose to $2.078 billion in the first quarter of 2026 and $2.575 billion in the second, a rapid climb from roughly $189 million two years earlier. But net losses have widened in dollar terms even as the top line has grown: the company reported a net loss of $740 million in the first quarter of 2026 and $626 million in the second, according to its quarterly filings. That is the trade-off at the heart of the story the angle brief flags – a business scaling revenue fast enough to keep lenders and convertible buyers interested, while still consuming enough cash that equity discipline has yet to arrive.
Short interest ticked up ahead of the announcement
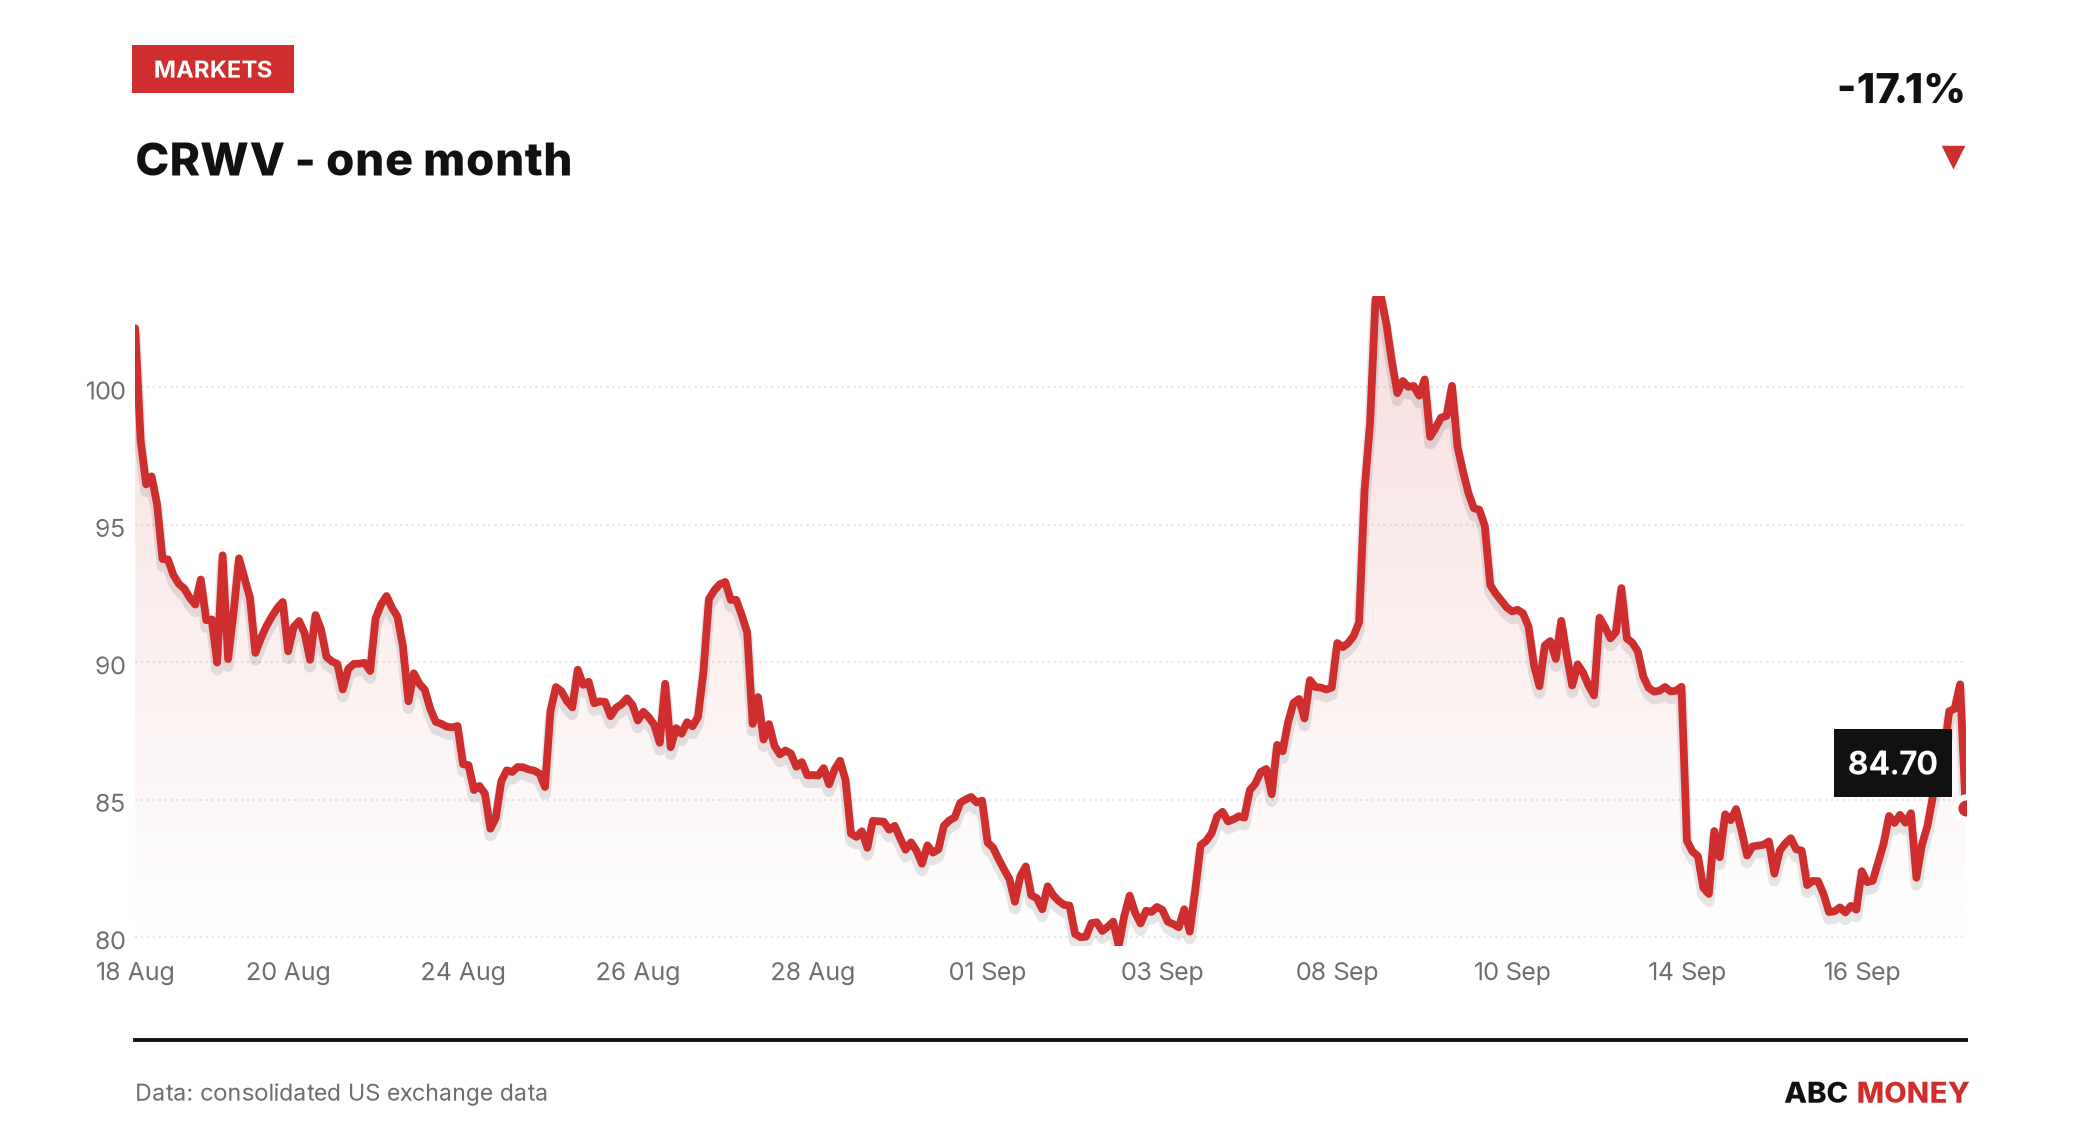
Positioning data hint that some investors saw the raise coming, or at least bet against the stock in the run-up to it. FINRA’s daily short-sale volume ratio for CRWV – the share of daily trading volume accounted for by short sales – rose from 0.469 on 9 September to 0.652 by 16 September, the day before the offering was announced, according to FINRA data. CoreWeave shares last traded at $85.65, up 1.93% on the day but still down almost 6% over the preceding 20 trading sessions, on volume running at roughly half the 20-day average.
The timing also lands against a backdrop of elevated borrowing costs generally: the 10-year US Treasury yield stood at 5.00% as of 15 September, up marginally from 4.97%, according to Federal Reserve data. With benchmark rates near that level, convertible structures – which trade a lower cash coupon for potential equity upside – remain one of the cheaper ways for a fast-growing but loss-making company to raise large sums without loading on straight high-yield debt at double-digit rates.
Pricing terms for the new notes, including the coupon and conversion premium, have not yet been set. Investors will get those details, along with confirmation of whether the initial purchasers exercise their $500 million option, once the offering closes – the next marker in what has become a fairly regular feature of CoreWeave’s financing calendar.
This article is for information only and is not investment advice or a recommendation to buy or sell any asset. Markets move quickly; figures are correct as sourced at the time of writing. Always do your own research before making financial decisions.


 Bitcoin
 Ethereum
 Tether
 BNB
 USDC
 XRP
 Solana
 TRON
 Lido Staked Ether
 Cardano
 Gram (prev. Toncoin)
 Avalanche