
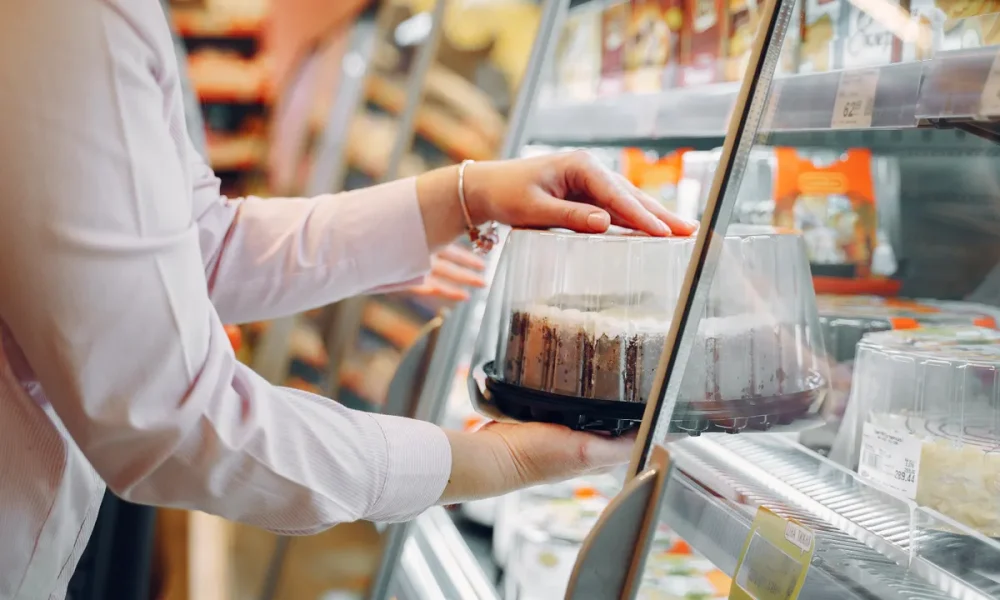
Cake Box Holdings‘ dividend yield has reached 6.1% on a forward basis, making CBOX one of the few AIM-listed stocks where a genuine growth narrative sits alongside a high income payout. With the franchise operator’s share price down 45% from its post-pandemic peak, the yield has expanded sharply: a £3,000 investment at current prices buys 1,538 shares and, on current forecasts, would produce around £183 in annual passive income.
A Franchise Model With Momentum
Cake Box operates an asset-light franchise model selling egg-free cream celebration cakes through a store estate that now numbers 310 sites. The pandemic years briefly turned the stock into a momentum favourite, with the share price surging 250% from its lows before accounting errors in early 2022 triggered a sharp reversal and the departure of the co-founder and chief financial officer.
Recovery has been methodical. New CFO Michael Botha, previously at Domino’s Pizza, has helped rebuild governance credibility while the underlying business has continued expanding. Full-year results for the 52 weeks ended 29 March 2026 showed group revenue up 39% to £59.7m, with system sales reaching £111.27m across the franchise network. The core Cake Box segment delivered 9.3% sales growth with overheads rising only 3.0%, which drove a 21.7% increase in the unit’s underlying EBITDA. Group underlying EBITDA rose 41.6% to £12.4m, while underlying profit before tax climbed 22.6% to £8.67m.
Diluted earnings per share rose almost 20% to 15.4p. City analysts currently have 15% to 16% EPS growth pencilled in for both FY27 and FY28. Management noted in June that FY27 had started decently. The balance sheet carries a leverage ratio of 0.88 times, below the group’s own target of 1.0.
Cake Box Holdings Dividend and Valuation
The dividend policy has kept pace with earnings. Last year’s payout grew 5.9% to 10.8p per share; this year’s forecast calls for 11.9p, growth of around 10%. The prospective dividend is expected to be covered 1.5 times by underlying EPS, which provides reasonable headroom. No dividend is ever guaranteed, but coverage at that level looks defensible unless earnings disappoint materially.
At 11 times forward earnings, the valuation is undemanding for a business growing EPS at mid-teens rates. The CEO has been buying shares in the open market, which, taken alongside the low multiple, suggests management sees the current price as an undervaluation rather than fair value.
The Ambala Expansion Case
The acquisition of Ambala Foods, completed on 21 March 2025, is the most consequential strategic move Cake Box has made since its IPO. The deal totalled £22m: £16m for Ambala Foods Limited and £6m for its freehold manufacturing facility in Welwyn Garden City. Funding comprised a £7.0m equity raise, a £15.2m term loan facility, and a £0.2m retail offer, as confirmed at announcement.
Ambala, a manufacturer and retailer of Asian sweets (mithai) with roots stretching back to the 1960s, brought 22 stores into the group at the time of acquisition. By the end of March 2026, that count stood at 34. Ambala contributed £14.14m in revenue in its maiden full-year period and generated underlying EBITDA of £1.85m, up from just £0.09m in FY25 as the integration began. The strategic logic is demographic: a large and growing British Asian population creates a durable demand base for celebration sweets tied to Diwali, Eid, and community events throughout the year.
The group’s stated targets are 400 Cake Box and 100 Ambala locations. Near-term annual opening targets, set at the H1 FY2026 earnings call, are 25 new Cake Box franchisee stores per year and at least 10 new Ambala franchisee stores per year. With Ambala at 34 sites and the target at 100, the runway is long.
The risks are real, however. Consumer discretionary spending on celebration cakes is sensitive to the cost-of-living environment, and high-street competition for the category is intense. Inflation remains an overhead cost pressure even where it has eased at the headline level. Renewed tension in the Middle East adds a layer of macro uncertainty that could dampen the consumer confidence the business depends on.
The thesis is straightforward: a profitable franchise operator with a 6.1% forward yield, earnings growing at mid-teens, and a second brand in the early stages of its rollout, all priced at 11 times forward earnings. The next test is whether Ambala’s EBITDA margin can expand materially as the franchise network scales beyond 50 sites; that is the number that would confirm the acquisition was transformative rather than merely additive.

 Bitcoin
 Ethereum
 Tether
 BNB
 USDC
 XRP
 Solana
 TRON
 Lido Staked Ether
 Cardano
 Gram (prev. Toncoin)
 Avalanche