
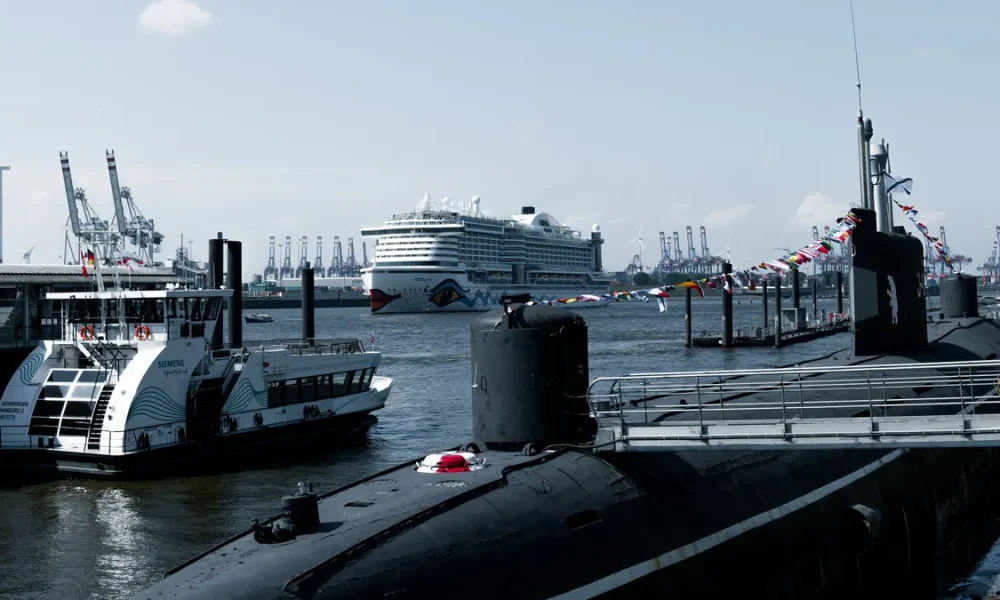
The Babcock International share price has fallen 17.1% in a single month, dragging it below levels seen when the current defence spending optimism began, and sitting 33% lower than at the start of the year. BAE Systems has slipped 13.1% since mid-August, despite being up 15% year to date. Rolls-Royce has pulled back 5% in recent days. The surface reading is a sector rotation away from UK defence. The underlying picture, at least for Babcock, is more complicated.
Why UK Defence Stocks Are Pulling Back
The common pressure across all three names is the fiscal backdrop. UK government bond yields have climbed to a 28-year high, and higher debt-servicing costs leave less room for discretionary spending, including defence budgets. When gilt yields move like this, the market reprices growth assumptions for companies whose revenues depend on government appropriations.
The Middle East escalation adds a layer of ambiguity rather than straightforward support. Rising oil prices and inflation concerns weigh on the commercial aviation cycle that Rolls-Royce depends on. For defence contractors, Gulf-state customers may spend more, but UK Treasury constraints are the binding variable closer to home.
Babcock’s specific re-rating reflects a broader reset of expectations following the appointment of John Healey as Chancellor of the Exchequer in July. His move from defence secretary was initially read as bullish for the military budget; the stock has since given all of that back, and then some.
Babcock International Share Price and the Fundamental Case
The valuation reset looks harder to justify once you examine what the business actually delivered in its most recent full year. Babcock’s FY26 annual report (year ended 31 March 2026) shows revenue of £5,178m, up from £4,831m in FY25. Underlying operating profit rose to £433m from £363m, with the underlying margin expanding to 8.2% from 7.5%. Underlying free cash flow more than doubled, from £153m to £262m. Net debt (excluding leases) was a net cash position of £23m, having been £101m net cash the prior year.
These are not the numbers of a business in distress. According to Babcock’s investor relations page, the company now classifies itself as a FTSE 100 defence company, having completed a multi-year turnaround focused on balance-sheet repair and portfolio simplification. The snippet’s reference to it as a FTSE 250 stock reflects an earlier period; the FTSE 100 promotion reflects the recovery since.
The contract backlog stood at approximately £9.8bn at FY26 year-end, with around 29,000 employees globally and approximately 80% of revenue derived from defence and nuclear operations. Forward earnings are currently priced at under 14 times, which is undemanding for a business with this degree of revenue visibility.
Nuclear and Submarine Work Provide Long-Duration Visibility
The structural argument for Babcock rests on the nature of its contracts rather than cyclical defence budgets. The company provides engineering support and maintenance for the Royal Navy’s nuclear submarine fleet. Its Frontline Mission Support Programme, a five-year contract worth approximately £3.5bn covering naval base operations at HMNB Clyde and HMNB Devonport, completed on 31 March 2026. Babcock has agreed a bridging arrangement with the Ministry of Defence (MoD) while a new long-term agreement reaches its final stages of negotiation.
Separately, Babcock secured a £114m contract from the MoD to prepare for the defuelling of four decommissioned submarines, with work recommencing from 2026. It is the first nuclear defuelling of a British submarine in over 20 years, creating more than 150 jobs at Devonport.
Civil nuclear adds a second growth vector. Nuclear already represents 40% of group revenue, and Babcock holds a joint-venture role supporting Rolls-Royce’s small modular reactor programme in North Wales. As CEO David Lockwood put it before handing over to successor Harry Holt in August 2026: ‘Whoever buys SMRs is going to need an owner’s engineer, a government-side person. No one’s ever done this before, so everyone needs engineering support on the buying side…That adds up to a 25-year growth story.’
The UK government’s commitment to reach 3.5% of GDP on core defence by 2035 provides a political floor beneath the budget debate. SKYNET, the MoD’s military satellite communications capability, and Babcock’s cybersecurity work add further revenue lines that are difficult to replicate.
Berenberg has maintained a Buy rating on BAB and raised its price target to £16.70 from £14.40, reflecting the improving margin trajectory. The next test for the Babcock International share price is whether the bridging arrangement on the submarine sustainment programme converts to a new long-term contract on terms that preserve or extend the existing margin profile. If it does, the current multiple will look cheap in retrospect.

 Bitcoin
 Ethereum
 Tether
 BNB
 USDC
 XRP
 Solana
 TRON
 Lido Staked Ether
 Cardano
 Gram (prev. Toncoin)
 Avalanche