
Goldman Sachs has lifted its Palantir price target to $230, upgrading the stock from Neutral to Buy in a note that landed just as Palantir Technologies (NASDAQ: PLTR) extended a three-month rally into a fresh leg higher. The call, from analyst Gabriela Borges, was framed by Seeking Alpha and Investing.com as implying roughly 18% upside, built on an improving outlook for sovereign artificial-intelligence contracts and what Borges called “bespoke development” work widening the company’s addressable market, according to 24/7 Wall St.
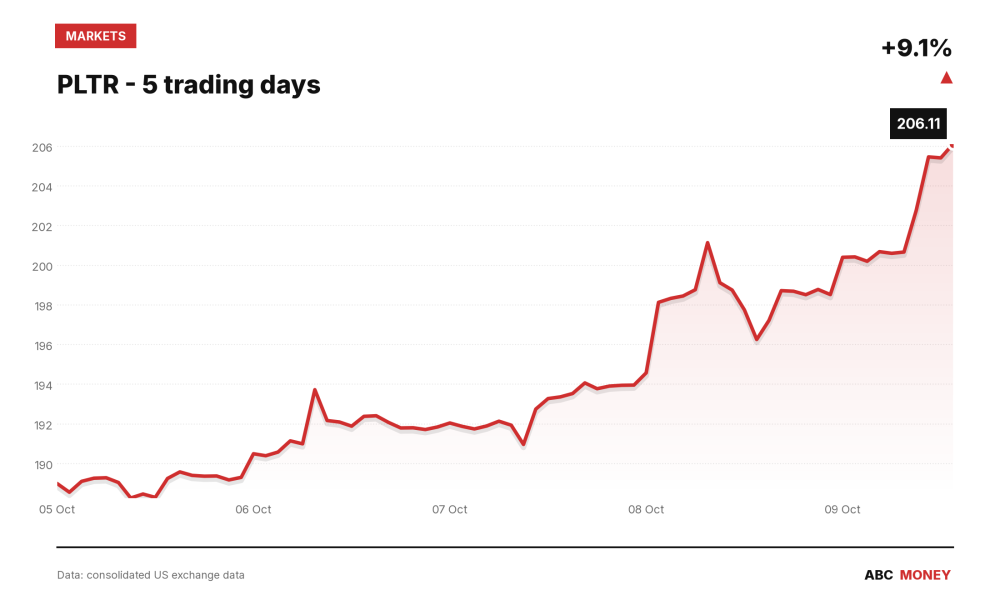
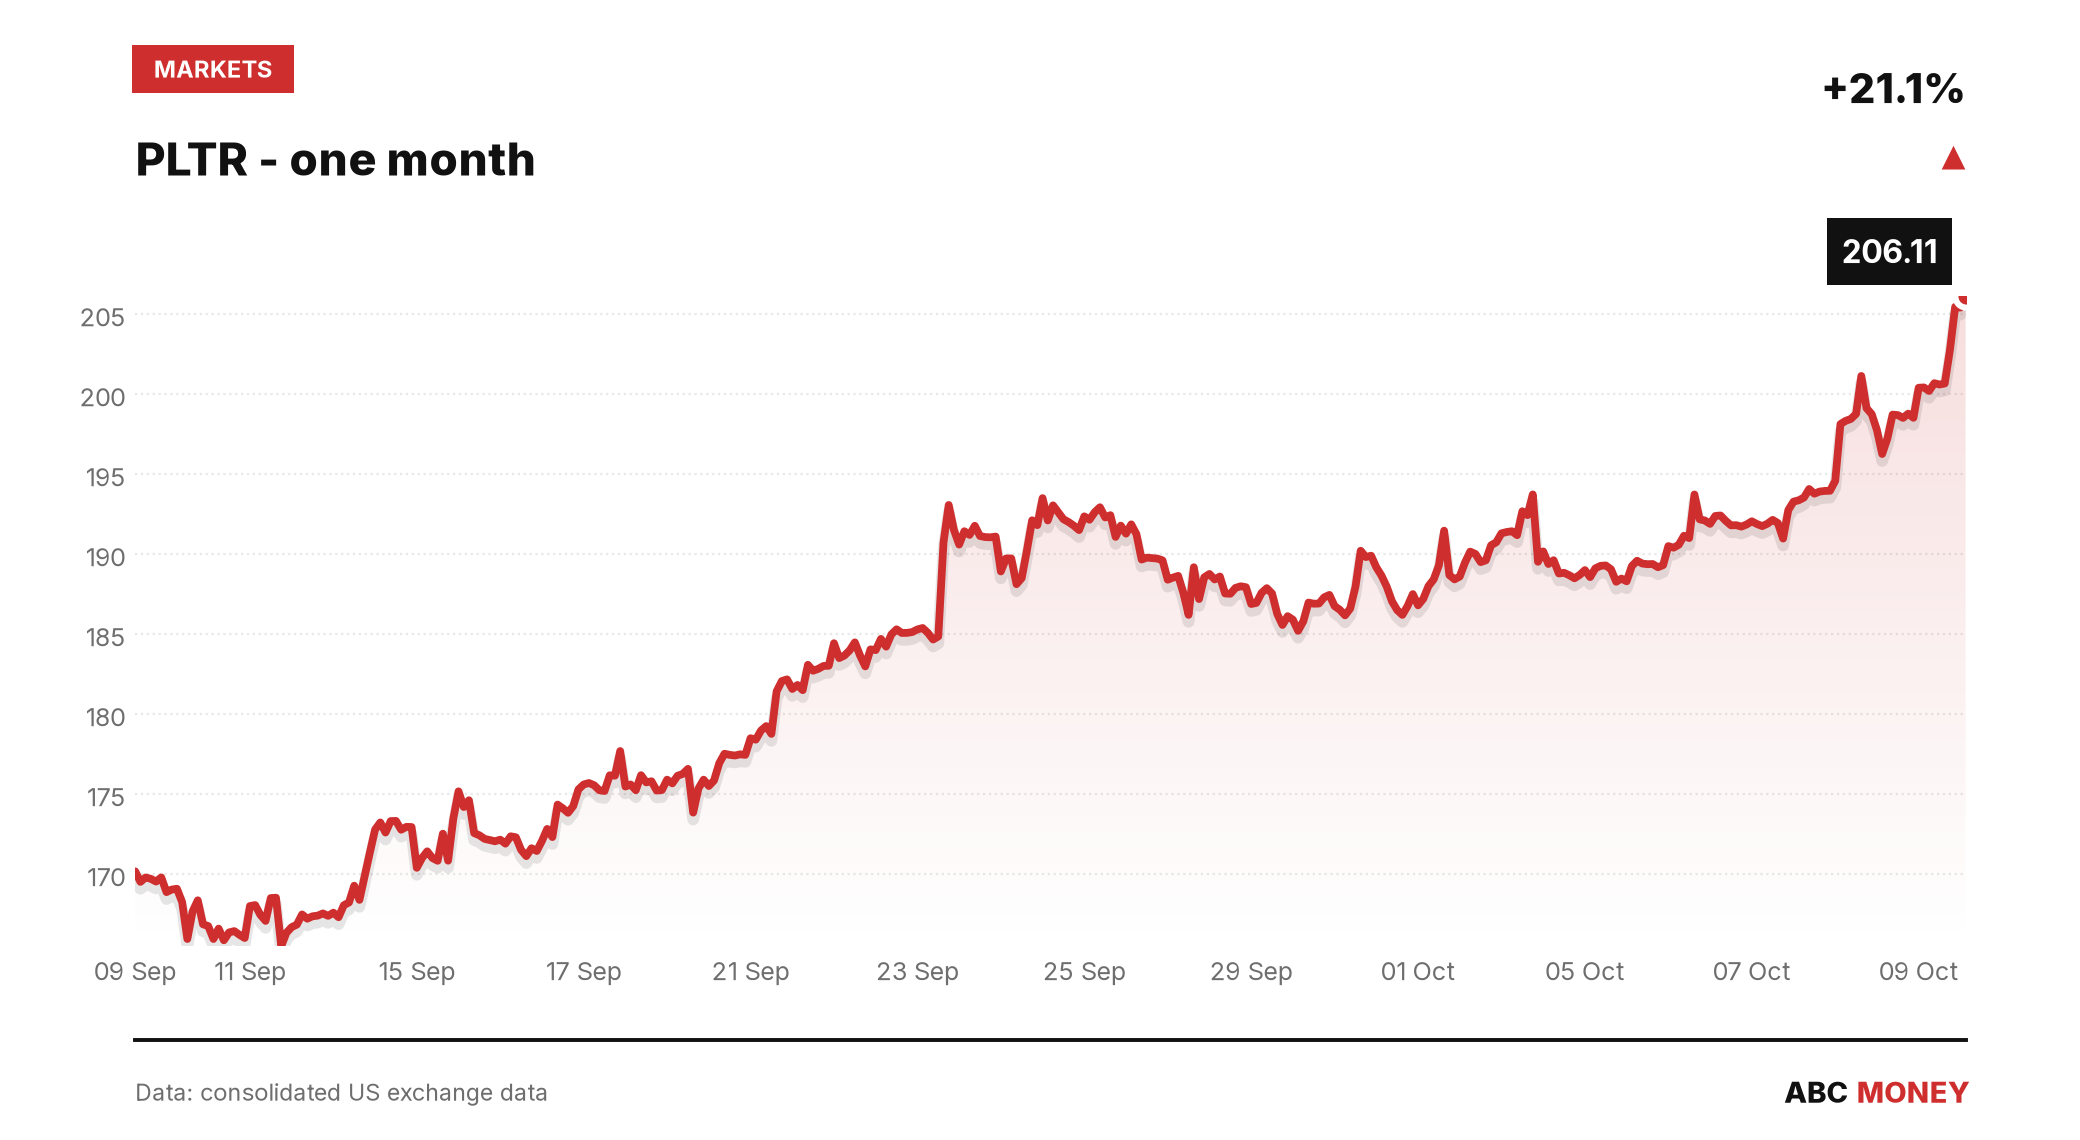
Palantir shares, which closed at $205.766 as of 9 October, were up 2.78% on the day and 16.3% over the preceding 20 trading sessions, with volume running nearly twice the 20-day average – a sign the market was paying attention rather than shrugging.
Why the Palantir price target upside kept shrinking
Here is the catch for anyone chasing the headline figure: Palantir didn’t sit still long enough for a single upside number to stick. GuruFocus calculated the $230 target as 18.5% above Wednesday’s close of $194.12. By Thursday, after the stock had already jumped roughly 3.8% to $201.37 on the upgrade itself, the same target implied closer to 14.2% upside, per TradingView, citing Barron’s. With the stock pushing past $205 the following session, the gap between target and price had narrowed further still. None of the figures are wrong – they are simply snapshots of a stock that was moving faster than the news cycle could describe it.
That is worth flagging because the “18% upside” line has now appeared in multiple headlines as though it were fixed. It was accurate at the moment Goldman published its note. It is a moving target – literally – once a stock is rallying this hard.
A rally that already had a head of steam
Goldman’s upgrade didn’t arrive in a vacuum. Palantir had already gained around 45% over the three months before the call, closing at $194 on 7 October after second-quarter revenue rose roughly 93% year-on-year, according to Yahoo Finance. Street sentiment was already skewed bullish going in, with 19 buy ratings and one outperform against nine holds, and a consensus price target near $200 before Goldman’s move – meaning the $230 figure didn’t just nudge the average up, it pulled the top of the range higher.
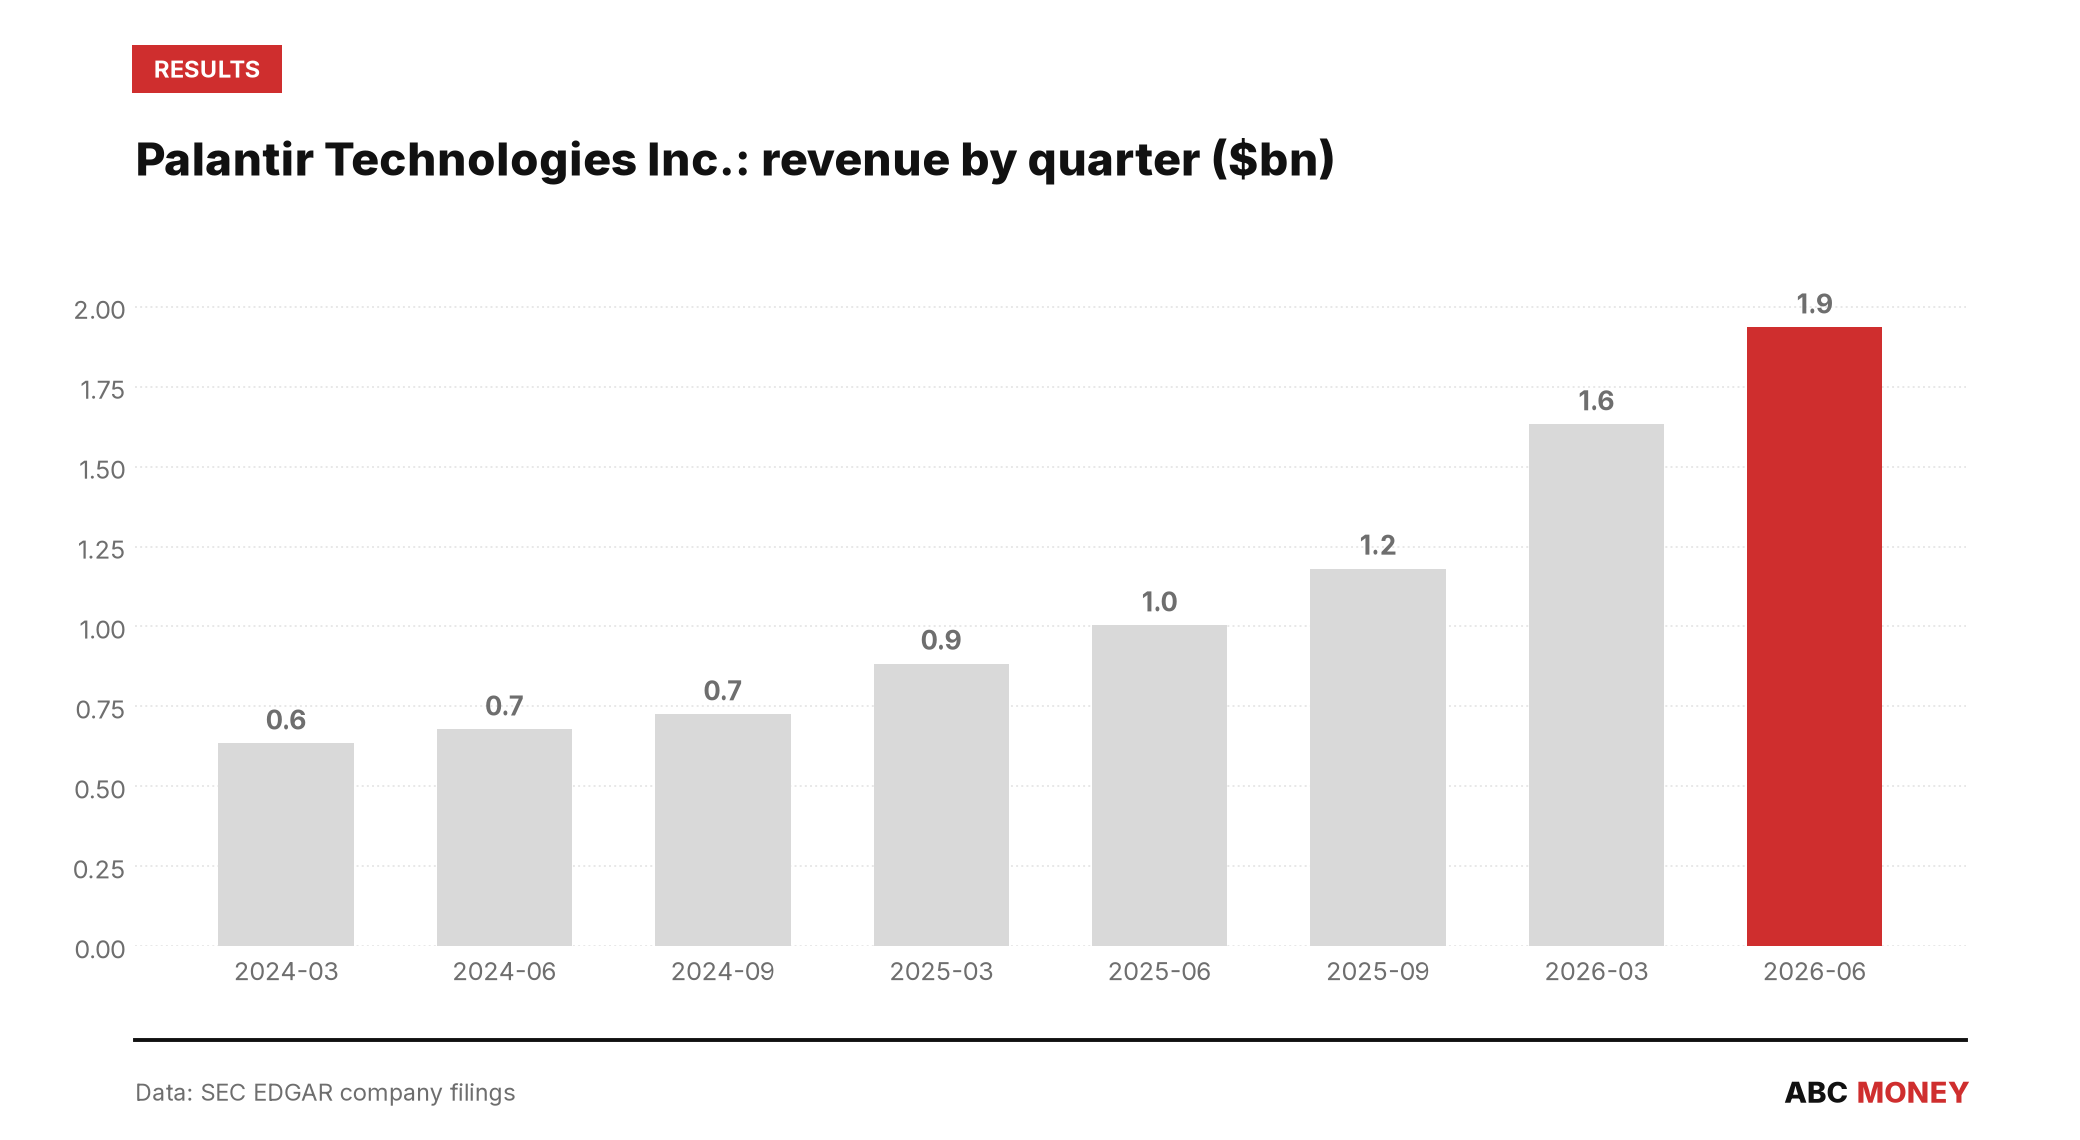
The filings back up the growth story Goldman is leaning on. Palantir’s quarterly revenue, tracked through its own SEC disclosures, climbed from $634.3m in the first quarter of 2024 to $1.94bn in the second quarter of 2026 – a trajectory that has accelerated rather than flattened. Net income over the same run moved from $105.5m to $1.06bn, with diluted earnings per share rising from 4 cents to 41 cents across the same two quarters, per the company’s 10-Q filings with the SEC. That is the kind of compounding that tends to earn a growth stock the benefit of the doubt from analysts, even after a 45% run.
Positioning tells its own story
There are small signs the market was repositioning around the news rather than simply buying the dip. FINRA’s daily short-sale data shows the proportion of Palantir volume tied to short sales – bets that the stock would fall – climbing to 0.637 on the day of the upgrade, up from 0.474 just over a week earlier. That is not evidence of a short squeeze; short-sale ratios this size are routine market-making activity rather than a crowded bearish trade. But the uptick does suggest more two-way flow around the announcement than a simple one-way rush into the stock.
Separately, a Form 4 filing from Palantir insider Lauren Elaina Friedman hit EDGAR on 6 October, two days ahead of the upgrade. The filing disclosed no share counts or dollar values, so it tells readers little beyond the fact that insider paperwork was moving through the system in the same window – a detail for the record rather than a signal either way.
Goldman’s note reportedly extends its bullish view into 2027, per 24/7 Wall St., betting that the sovereign AI and bespoke-development pipeline Borges cited has further to run rather than being a one-quarter phenomenon. Whether the next print of Palantir’s revenue growth – due with its following quarterly filing – keeps pace with the 93% year-on-year rate that got Wall Street’s attention will do more to settle that question than any single price target, however it’s calculated.
This article is for information only and is not investment advice or a recommendation to buy or sell any asset. Markets move quickly; figures are correct as sourced at the time of writing. Always do your own research before making financial decisions.

 Bitcoin
 Ethereum
 Tether
 BNB
 USDC
 XRP
 Solana
 TRON
 Lido Staked Ether
 Cardano
 Gram (prev. Toncoin)
 Avalanche