
Chariot Limited shares have returned 109.78% year-to-date as of 10 September 2026, against 6.25% for the FTSE 100, after the AIM-listed Africa-focused energy group moved from idea to execution on a material Angola oil-production deal. The stock traded around 1.5p at the start of August; by early September it had reached 3p before pulling back slightly.
The Angola Deal Driving Chariot Limited Shares Higher
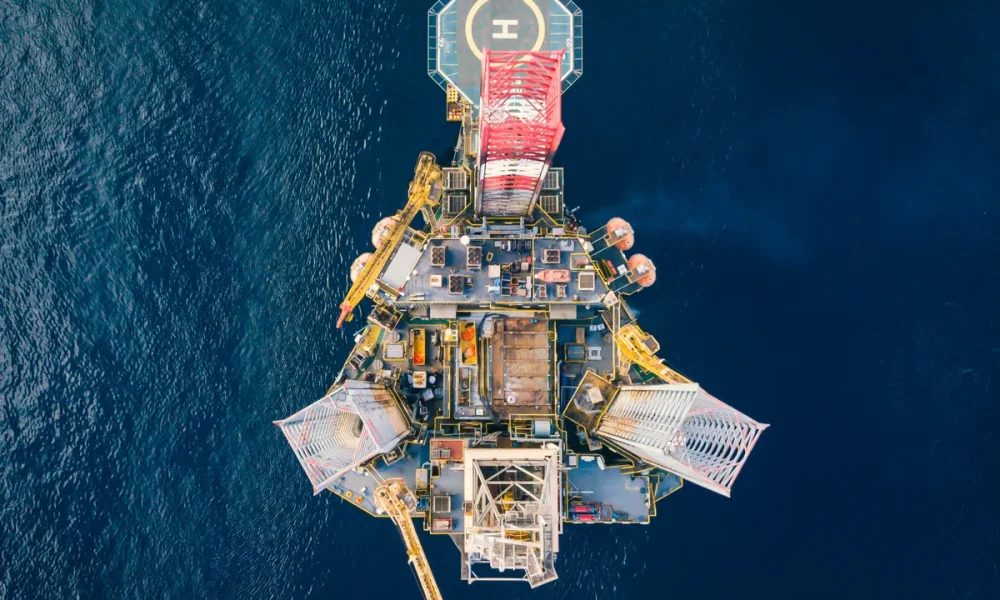
The immediate catalyst is a framework agreement with Etu Energias and BW Energy tied to the acquisition of deepwater producing assets offshore Angola. Etu Energias is acquiring a 31% working interest in Block 14 and a 15.5% interest in Block 14K from Chevron, two producing deepwater licences offshore Cabinda. Etu intends to assume operatorship of Block 14.
Under the framework agreement, Chariot gains economic exposure equivalent to around 4,000 barrels of oil per day from those producing blocks. BW Energy’s parallel support to Etu gives it exposure to cashflow corresponding to approximately 8,000 bbl/d and associated net 2P reserves of 19 million barrels.
Two sources place the headline transaction at different figures: one aggregator cites $250 million while a second cites $260 million for the same Etu Energias acquisition of Chevron’s interests; the $260 million figure aligns with the preemptive right Etu exercised to block a prior bid at that level, so that is the figure used here. The transaction structure also involves Shell Trading providing acquisition finance in exchange for offtake barrels.
To part-fund its participation, Chariot announced on 19 February 2026 a fundraise comprising a Proposed Placing and Subscription to raise approximately US$20 million (£14.8 million) and an Open Offer to raise up to approximately US$4 million (approximately £3 million). Proceeds are earmarked to part-finance Etu Energias’ acquisition of the working interests, cover transaction costs, and add corporate working capital, according to the Chariot official fundraising announcement.
The Open Offer attracted stronger demand than anticipated: acceptances were received for 46.2 million shares against the 23.4 million shares available, a significant oversubscription for a company at this market capitalisation.
Return to Profitability Provides a Second Pillar
The Angola deal alone might have moved the stock, but Chariot’s return to profitability gave investors a second reason to reassess the valuation. The group reported net income of $0.345 million for the 2025 financial year, against a net loss of $22.35 million in 2024. For a micro-cap that has spent years in development mode, that swing from deep loss to positive territory changes the narrative.
Chariot’s broader asset base adds further options. The group holds a 75% working interest in an offshore gas project in Morocco, through its Lixus and Rissana offshore licences and the Loukos onshore licence. It also holds wind assets in South Africa and green hydrogen interests in Mauritania. Management has indicated it may divest parts of the renewables portfolio to fund further upstream activity, which, if executed, would sharpen the production-focused story.
The counterparty profile adds context. Etu Energias, Angola’s largest privately owned energy company and formerly known as Somoil, has invested more than $1.5 billion in asset acquisitions over roughly the past four to five years, according to CEO Edson dos Santos in a Reuters interview. In March 2026, Etu also preempted Maurel & Prom and BW Energy on a separate stake in Block 14 from the BP and Eni joint venture Azule Energy, demonstrating consistent appetite for these specific assets.
Risks That Could Unsettle the Thesis
The setup is clear enough on paper. Execution is the variable that matters now. Cross-border transactions of this complexity, involving multiple parties, structured finance, and Angolan regulatory approvals, rarely close on schedule. Commodity price exposure means production-stage cash flows can shift quickly if oil markets weaken. Political and regulatory risk in African jurisdictions is a standing consideration for any investor in this space.
Dilution risk is also live. The fundraise announced in February already added shares to the register, and further rounds cannot be ruled out as transaction costs and working capital requirements evolve.
Broker Cavendish lifted its target price after the Etu Energias deal, citing substantial upside, though the full target figure was not available in published summaries at time of writing. Analyst price-target upgrades at the micro-cap end of AIM should be weighed against liquidity constraints and execution timelines rather than taken at face value.
The market capitalisation has moved from roughly £40 million in July to near £80 million today. Whether that re-rating is justified depends almost entirely on whether management can convert the framework agreement into steady, cash-generative production. The next staging post is formal completion of the Etu Energias acquisition of the Chevron interests: watch for that announcement.

 Bitcoin
 Ethereum
 Tether
 BNB
 USDC
 XRP
 Solana
 TRON
 Lido Staked Ether
 Cardano
 Gram (prev. Toncoin)
 Avalanche