
The BP share price target of 770p set by the most bullish of the 27 analysts covering the stock represents a 50% gain from BP’s current level of 515p, and the question of whether it is achievable has sharpened considerably since the company’s largest hydrocarbon discovery in 25 years moved into appraisal.
What the BP Share Price Target Range Reveals
The consensus one-year target from those 27 analysts sits at 600p, implying around 16% upside from here. Layer in the forward dividend yield of 4.9% and the total potential return climbs above 20%. The range of individual forecasts, however, is unusually wide: from 454p to 770p. That spread reflects genuine uncertainty about where the oil price settles, not merely different views on BP’s execution.
Of the 30 analysts who have issued ratings in the past three months, 12 have a Strong Buy, two a Buy, 13 a Hold, one a Sell and two a Strong Sell. The 13 Holds matter here. They are not a negative signal in themselves, but they tell you that a meaningful portion of the analyst community sees the risk-reward as balanced rather than compelling at current prices.
Brent crude has had a turbulent year. The conflict in Iran pushed the price to around $118 a barrel at the end of April; it has since retreated to $88, though that is still 47% above the $60 level at which the year began. Where crude goes from here determines more about BP’s near-term earnings than almost any operational variable the company can control.
Bumerangue: Scale, Terms and What Comes Next
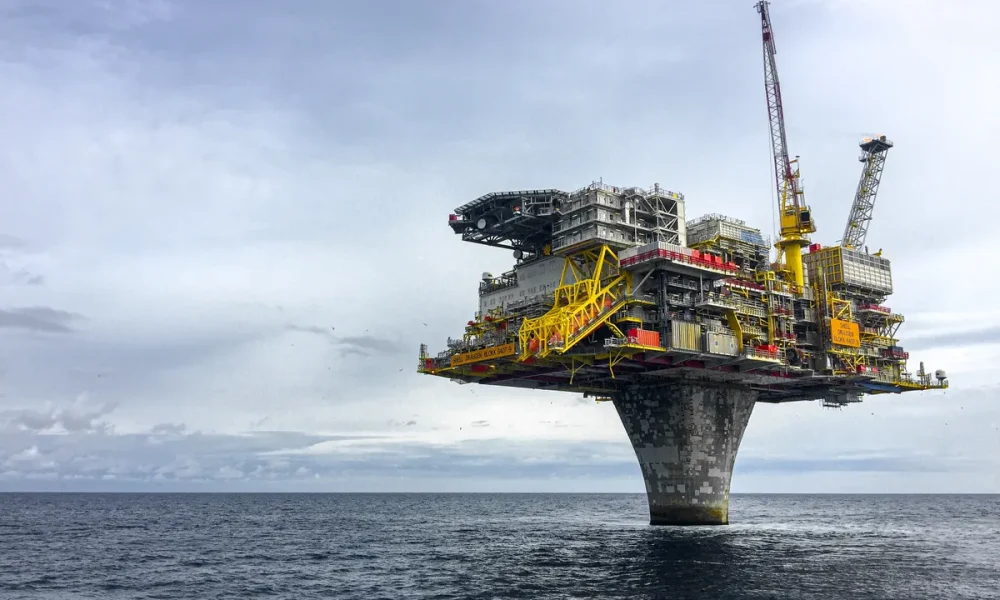
The Bumerangue discovery, located in the Santos Basin 404 kilometres from Rio de Janeiro in 2,372 metres of water, drilled to a total depth of 5,855 metres and penetrated an estimated 500 metre gross hydrocarbon column in pre-salt carbonate reservoir. The areal extent exceeds 300 square kilometres. BP estimates roughly 8 billion barrels of liquids in place, according to its Q4 2025 earnings report, though the figure is subject to appraisal.
BP secured the block in December 2022 on terms it describes as commercially attractive: 80% cost oil and 5.9% profit oil. The company holds a 100% participation interest, with Pré-Sal Petróleo S.A. as the Production Sharing Contract manager. Bumerangue is also BP’s tenth exploration discovery of 2025, a run that includes finds in Trinidad, Egypt, the Gulf of America, Libya, Namibia and Angola.
On 25 August 2026, Halliburton announced it had received an integrated drilling-services contract from BP for the first appraisal campaign at Bumerangue, including deployment of its LOGIX™ automation and remote operations system. Appraisal drilling is expected to begin late 2026 or early 2027, according to Oil & Gas Journal. Results from rig-site analysis did flag elevated carbon dioxide levels, which adds a technical variable to any development planning. The discovery alone does not translate quickly into production; deepwater pre-salt appraisal and development timelines typically run into years.
New CEO, New Structure, Old Pressures
Meg O’Neill became BP’s chief executive on 1 April 2026, following Murray Auchincloss’s departure on 18 December 2025 and a brief interim period under Carol Howle. O’Neill came from Woodside Energy, where she had been chief executive since April 2021 and oversaw the acquisition of BHP Petroleum International. She brings 23 years of ExxonMobil experience before that.
Her base salary has been set at £1,600,000, with a cash pension allowance of 20% of salary in line with the wider workforce. She is not eligible for a salary increase until April 2027.
Under her leadership, BP has reorganised into two segments: upstream and downstream, with Supply, Trading & Shipping spanning both. Renewable businesses, including solar and offshore wind, have been moved into the Technology function under a capital-light model. The direction of travel is clear: hydrocarbon production is the priority, with BP targeting output of 2.3 to 2.5 million barrels of oil equivalent per day by 2030.
On the balance sheet, BP’s Q1 2026 filing with the Securities and Exchange Commission (SEC) shows the company plans to reduce its perpetual hybrid bond capital from a notional $13.3 billion to approximately $9 billion, subject to market conditions, as divestment proceeds come in. The same filing revised BP’s Brent oil impairment price assumption upward to $82.80 per barrel (from $70.00 per barrel) in real 2024 terms for 2026, reflecting the geopolitical environment.
For investors weighing BP today: the five-year total return, including dividends running at roughly 5% annually, is approaching 100%, and the stock has absorbed a great deal of turbulence in getting there. The 770p target is not a base case; it is the top of a wide distribution. The next test is whether Bumerangue appraisal data, due in the first half of 2027, upgrades the resource estimate and whether O’Neill’s restructured upstream machine can hold costs as the oil price oscillates.
 Bitcoin
 Ethereum
 Tether
 BNB
 USDC
 XRP
 Solana
 TRON
 Lido Staked Ether
 Cardano
 Gram (prev. Toncoin)
 Avalanche