
Tax Relief for Landlords: The Legal Deductions FBR Offers That Most Property Owners Don’t Know About
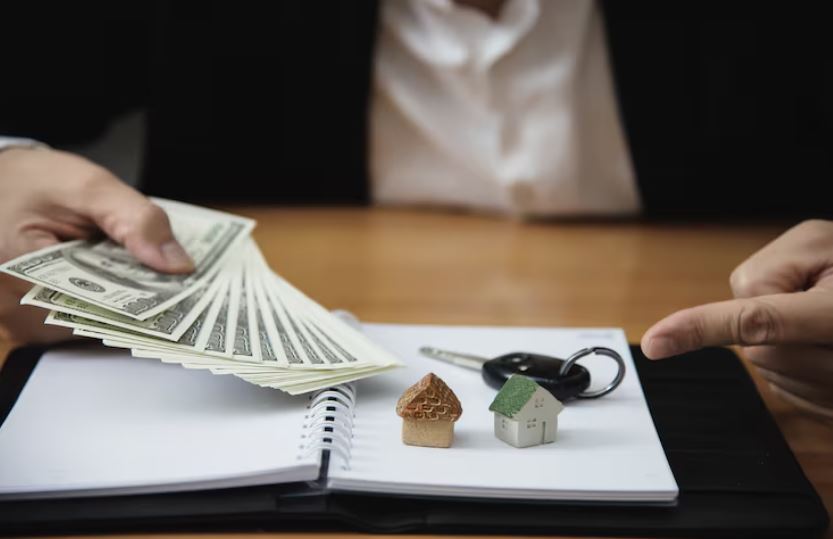
Any mid-sized Pakistani city, such as Sialkot, Faisalabad, or Lahore, will have rows of stores with handwritten lease agreements hidden in desk drawers, apartment complexes where rent is paid in cash each month, and landlords who have been collecting money for years without ever filing a tax return. It’s not always carelessness. Many people sincerely think that rental income falls into some unofficial category that FBR doesn’t cover. It doesn’t. And it’s getting more difficult to maintain that assumption as 2026 approaches.
The ability of the Federal Board of Revenue to cross-reference bank deposits, property values, and rental agreements has greatly increased. Tax notices are increasingly being sent to landlords who have not declared rental income; this is not because they did anything complicated, but rather because they were unaware that they were required to report it. Rent from land or a building, whether residential or commercial, is considered “Income from Property” under Section 15 of the Income Tax Ordinance 2001 and needs to be reported. For years, that has been the case. The degree to which FBR is enforcing it has changed.
The amount that can be legally deducted before any taxes are computed is what often surprises people. The most helpful deduction, which is listed in Section 15A of the Ordinance, doesn’t require any paperwork at all. No receipts or explanation are needed; a fixed 20% of gross rental income is automatically subtracted as a notional repair and maintenance allowance. Before anything else is applied, the taxable base decreases to Rs. 1.44 million if a landlord receives Rs. 1.8 million in rent over the course of a year. Many landlords still don’t know how to claim that significant reduction.
Other deductions may be applicable where they are actually incurred, in addition to the automatic repair allowance. The profit or interest paid on a bank loan that you used to build or buy the rental property is deductible. The taxable amount can be further reduced by provincial property tax, local government fees, insurance premiums against building damage, administration and collection costs up to 4% of gross rent, and, in some situations, unpaid rent from a defaulting tenant. Documentation is the key word throughout. The deductions are legitimate, but they need accurate documentation to withstand scrutiny in the event that FBR inquires.
Another distinction that many landlords are unaware of is that the withholding tax regulations are based on who is paying the rent rather than the amount. If your tenant is an individual renting a home for personal use, they typically do not deduct any tax from the rent; instead, you receive the entire amount and are responsible for paying the tax when you file your annual return. Your tenant must legally deduct tax at the source before delivering the monthly payment if they are a business or an association of persons. The property, the rent, and the cash flow situation are all entirely different. If a landlord changes from an individual tenant to a corporate one without taking this into consideration, the end-of-year computation may not go as planned.
Most landlords are unaware of how important filer status is. The standard progressive slab rates on net rental income are paid by active taxpayers. In addition to losing out on lower rates on real estate transactions, banking, and other aspects of financial life, non-filers are more vulnerable to withholding. Every year, the practical difference between filers and non-filers grows, and for a landlord with several properties, the total difference is truly substantial. It’s easy to become an active filer; all you need to do is get started.
Another area where the rules are more advantageous than people think is joint ownership. Each co-owner only reports their proportionate share of the rental income when a property is co-owned by several family members, which is typical in inheritance situations. The 20% notional repair deduction on each person’s share is available to them individually. This can keep individual tax liabilities within lower slabs than if one person paid the entire amount, depending on how the income is distributed. When the arrangement is authentic and recorded on the property title, it is completely lawful and worthwhile to consider.
Even among property owners who have been in the market for decades, there is still a great deal of uncertainty surrounding rental tax compliance in Pakistan. Once you understand the rules, they are not very difficult. The deductions are accurate. There is documentation of the thresholds. The habit of treating rental income as income, subject to the same reporting requirements as anything else, is what many landlords have been lacking.
 Bitcoin
 Ethereum
 Tether
 BNB
 USDC
 XRP
 Solana
 TRON
 Lido Staked Ether
 Cardano
 Gram (prev. Toncoin)
 Avalanche