
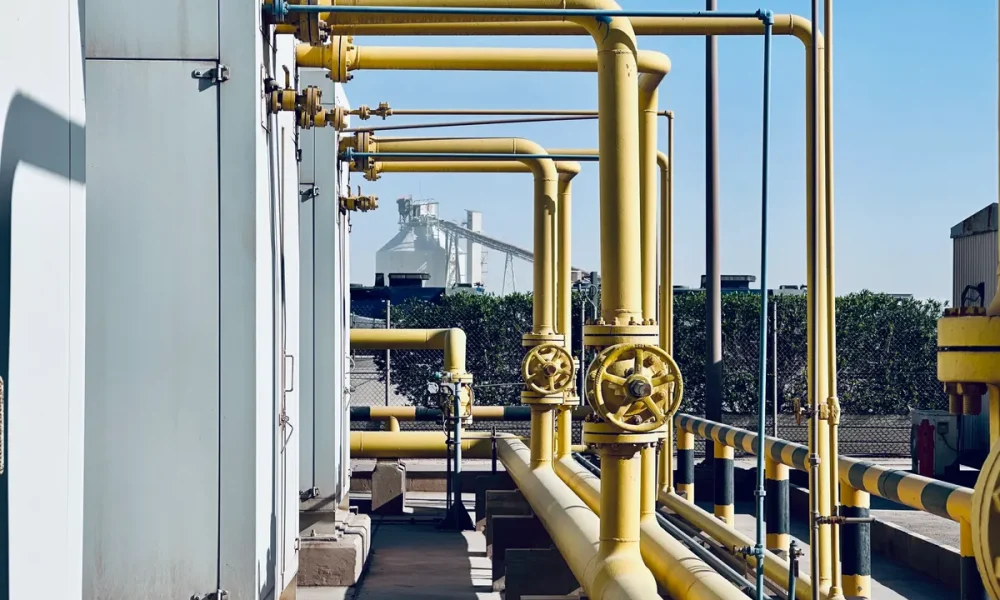
The Targa Resources ExxonMobil deal, announced on 17 August 2026, gave the $65 billion midstream operator a 20-year contractual anchor across both the Permian Delaware and Permian Midland basins, sending its shares up 10% on the day and setting up a capex cycle that will run well into the next decade.
Inside the Targa Resources ExxonMobil Deal
The agreements, executed with subsidiaries of ExxonMobil rather than the parent directly, cover integrated fee-based services: gathering, processing, treating, NGL transportation, and fractionation in the Delaware, plus new acreage dedications and extended fee-floor gathering and processing agreements in the Midland. Both basins include 20-year NGL dedications running through 2046 to Targa’s logistics and transportation assets.
What gives the arrangement structural weight is what was already in place before it. Targa’s 2025 annual report discloses that the company holds approximately 72.8% of WestTX, a joint venture covering certain plants and around 5,500 miles of gathering pipelines in the Permian, with ExxonMobil holding the remaining interest. The new agreements deepen a commercial relationship that already existed at the asset level.
The physical build-out to support the deal is considerable. Targa has announced three new natural-gas processing plants in the Permian Delaware (Wrangler, Ranger, and Ranger II) with a combined capacity of approximately 825 million cubic feet per day, all expected operational in the first half of 2028. Bull Run II, an approximately 70-mile natural-gas pipeline providing takeaway from those plants to Waha, is part of the same programme. As of Targa’s 2025 10-K filing, the Permian Delaware system already comprised approximately 7,700 miles of gathering pipelines and 23 processing plants with aggregate capacity of 4,282 MMcf/d; the three new plants represent a material addition to that base.
Capital spending reflects the scale of the commitment. Targa raised its full-year 2026 growth capital estimate from approximately $4.5 billion to approximately $5.0 billion, incorporating the new Delaware plants, incremental field capital, and Bull Run II. The company spent $2.1 billion on growth and maintenance capital in the first half of 2026, up 23% from the same period in 2025.
In December 2025, Targa had already moved to consolidate its Permian footprint, agreeing to acquire the Stakeholder gathering and processing platform for $1.25 billion, representing approximately six times 2026 estimated unlevered adjusted free cash flow and underpinned by long-term acreage dedications across approximately 170,000 acres in the San Andres play.
Why Midstream Economics Work
The pipeline industry’s investment case rests on a structural asymmetry between upfront cost and long-run returns. A large-diameter pipeline capable of carrying around one million barrels of oil per day costs approximately $5 million per kilometre over flat terrain. A 1,000-kilometre pipeline therefore carries a headline cost of around $5 billion before any geographic complications. Take-or-pay contracts, under which customers pay for committed capacity regardless of whether they ship product, transfer much of the volume risk to the shipper and make the pipeline operator’s cash flows far more predictable than those of the upstream companies feeding it.
The economics of the alternatives underpin this logic. Transporting oil by pipeline costs approximately $5 per barrel on average. Road or rail pushes that figure to around $18 per barrel. At the height of the US-Iran conflict earlier this year, some central African producers were reported to be paying as much as $200 per barrel, with $50 of that attributable to transport alone. Those numbers explain why the pipeline construction pipeline (to use the term loosely) remains full: according to The Economist, citing Global Energy Monitor, 12,300 kilometres of pipeline are currently under construction worldwide, with a further 20,100 kilometres proposed.
Targa’s own full-year 2026 adjusted EBITDA guidance, set in February, ran to $5.4 billion to $5.6 billion, with the midpoint representing an 11% increase over 2025. Second-quarter 2026 net income attributable to Targa Resources Corp. came in at $765 million, up from $629 million in the same quarter of 2025. The board declared a quarterly cash dividend of $1.25 per common share ($5.00 annualised), representing a 25% increase over the 2025 annual dividend.
Picks, Shovels and Sector Peers
Targa is not the only name worth examining. The broader midstream sector has re-rated as AI-driven power demand creates a second growth vector alongside oil and gas transport. Goldman Sachs Research projects domestic power demand from data centres will more than double from 31 gigawatts to 66 gigawatts by 2027, consuming over 8.5% of total US peak summer electricity. Natural-gas pipelines are the near-term solution for connecting new gas-fired generation to production zones.
Kinder Morgan (NYSE: KMI), the largest US natural-gas pipeline operator, reported record net income of $867 million in the second quarter, up 21% year on year. Its construction backlog stood at $9.7 billion at quarter-end, with natural-gas projects comprising 92% of the total. The company expects adjusted EBITDA of $9 billion for the full year, with adjusted earnings per share rising 12%.
The table below sets out the key metrics for the main listed midstream operators:
| Company | 2026 capex guidance | Trailing P/E | Dividend yield |
|---|---|---|---|
| Kinder Morgan (KMI) | N/A disclosed | Low 20s | 3%–5.5% |
| Enbridge (ENB) | C$10bn–C$11bn | Low 20s | 3%–5.5% |
| Williams Companies (WMB) | $7.3bn–$7.9bn | Low 20s | 3%–5.5% |
| Enterprise Product Partners | $2.9bn–$3.4bn | Partnership structure | Higher (MLP) |
| Targa Resources (TRGP) | ~$5.0bn | N/A in snippet | $5.00 annualised |
For investors who prefer a single fund wrapper, the Alerian Midstream Energy Dividend UCITS ETF (LSE: MMLP) holds all three C-corporation names plus 16 others, with Kinder Morgan, Williams, Enbridge and Targa comprising around 40% of the fund. It yields 3.6% on a trailing 12-month basis. Investors wanting the higher yields available from master limited partnerships (7.4% on the Alerian MLP ETF) should be aware that US Schedule K-1 tax forms make those structures burdensome for non-US investors and most smaller domestic US investors alike.
For those seeking exposure further up the risk curve, the Speedway NGL Pipeline, a 500-mile, 30-inch diameter line running from Targa’s Permian assets to Mont Belvieu at an estimated cost of $1.6 billion, is due in service in the third quarter of 2027. It illustrates the scale and duration of the current build cycle. The next material test for the Targa thesis will be whether the three Delaware processing plants achieve their first-half 2028 in-service dates on budget; any slippage there would be the first signal that the ExxonMobil commitment is running ahead of execution capacity.
 Bitcoin
 Ethereum
 Tether
 BNB
 USDC
 XRP
 Solana
 TRON
 Lido Staked Ether
 Cardano
 Gram (prev. Toncoin)
 Avalanche