Bitcoin
 Ethereum
 Tether
 BNB
 USDC
 XRP
 Solana
 TRON
 Lido Staked Ether
 Cardano
 Gram (prev. Toncoin)
 Avalanche
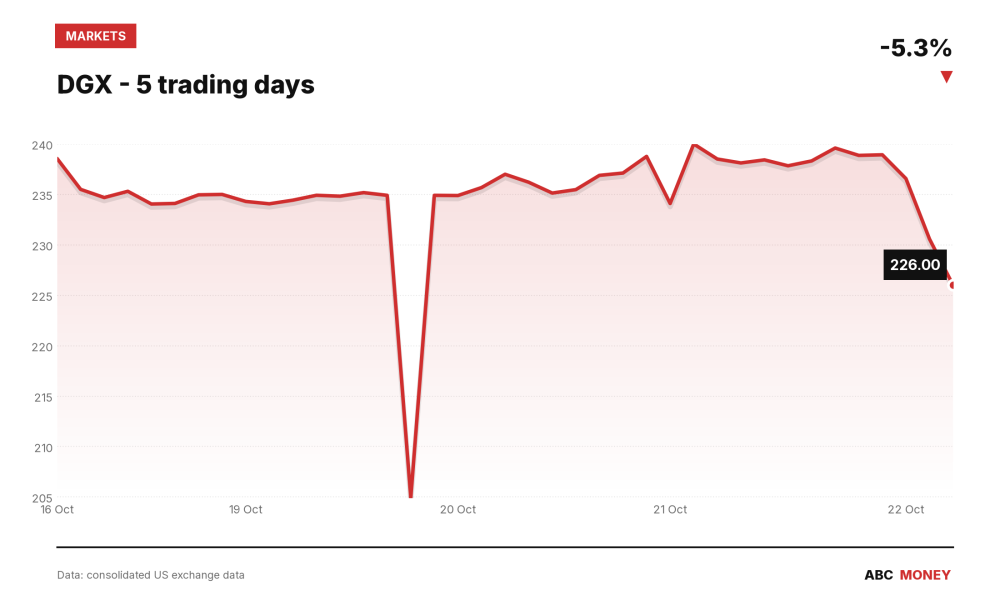
Quest Diagnostics (NYSE: DGX) delivered a decisive Quest Diagnostics earnings beat on 22 October 2026, lifting full-year guidance for the second straight quarter – and then watched its shares fall almost 5% anyway. Third-quarter revenue came in at $3.10bn, up 10.0% on the same period in 2025, while reported diluted earnings per share (EPS, the profit allocated to each share once all dilutive instruments like options and convertible debt are counted) rose 28.7% to $2.78, according to the company’s own filing and its results statement. Adjusted diluted EPS, which strips out one-off items, climbed 15.4% to $3.00.
Both figures beat what analysts had pencilled in. Consensus had looked for adjusted EPS of $2.87 and revenue of $3.05bn; Quest cleared both bars, according to Investing.com. Yet the diagnostics giant’s shares closed the session down 4.98% at $226.00, having traded as high as $240 and as low as $204.90 over the preceding 20 trading days.
A beat-and-raise that kept beating
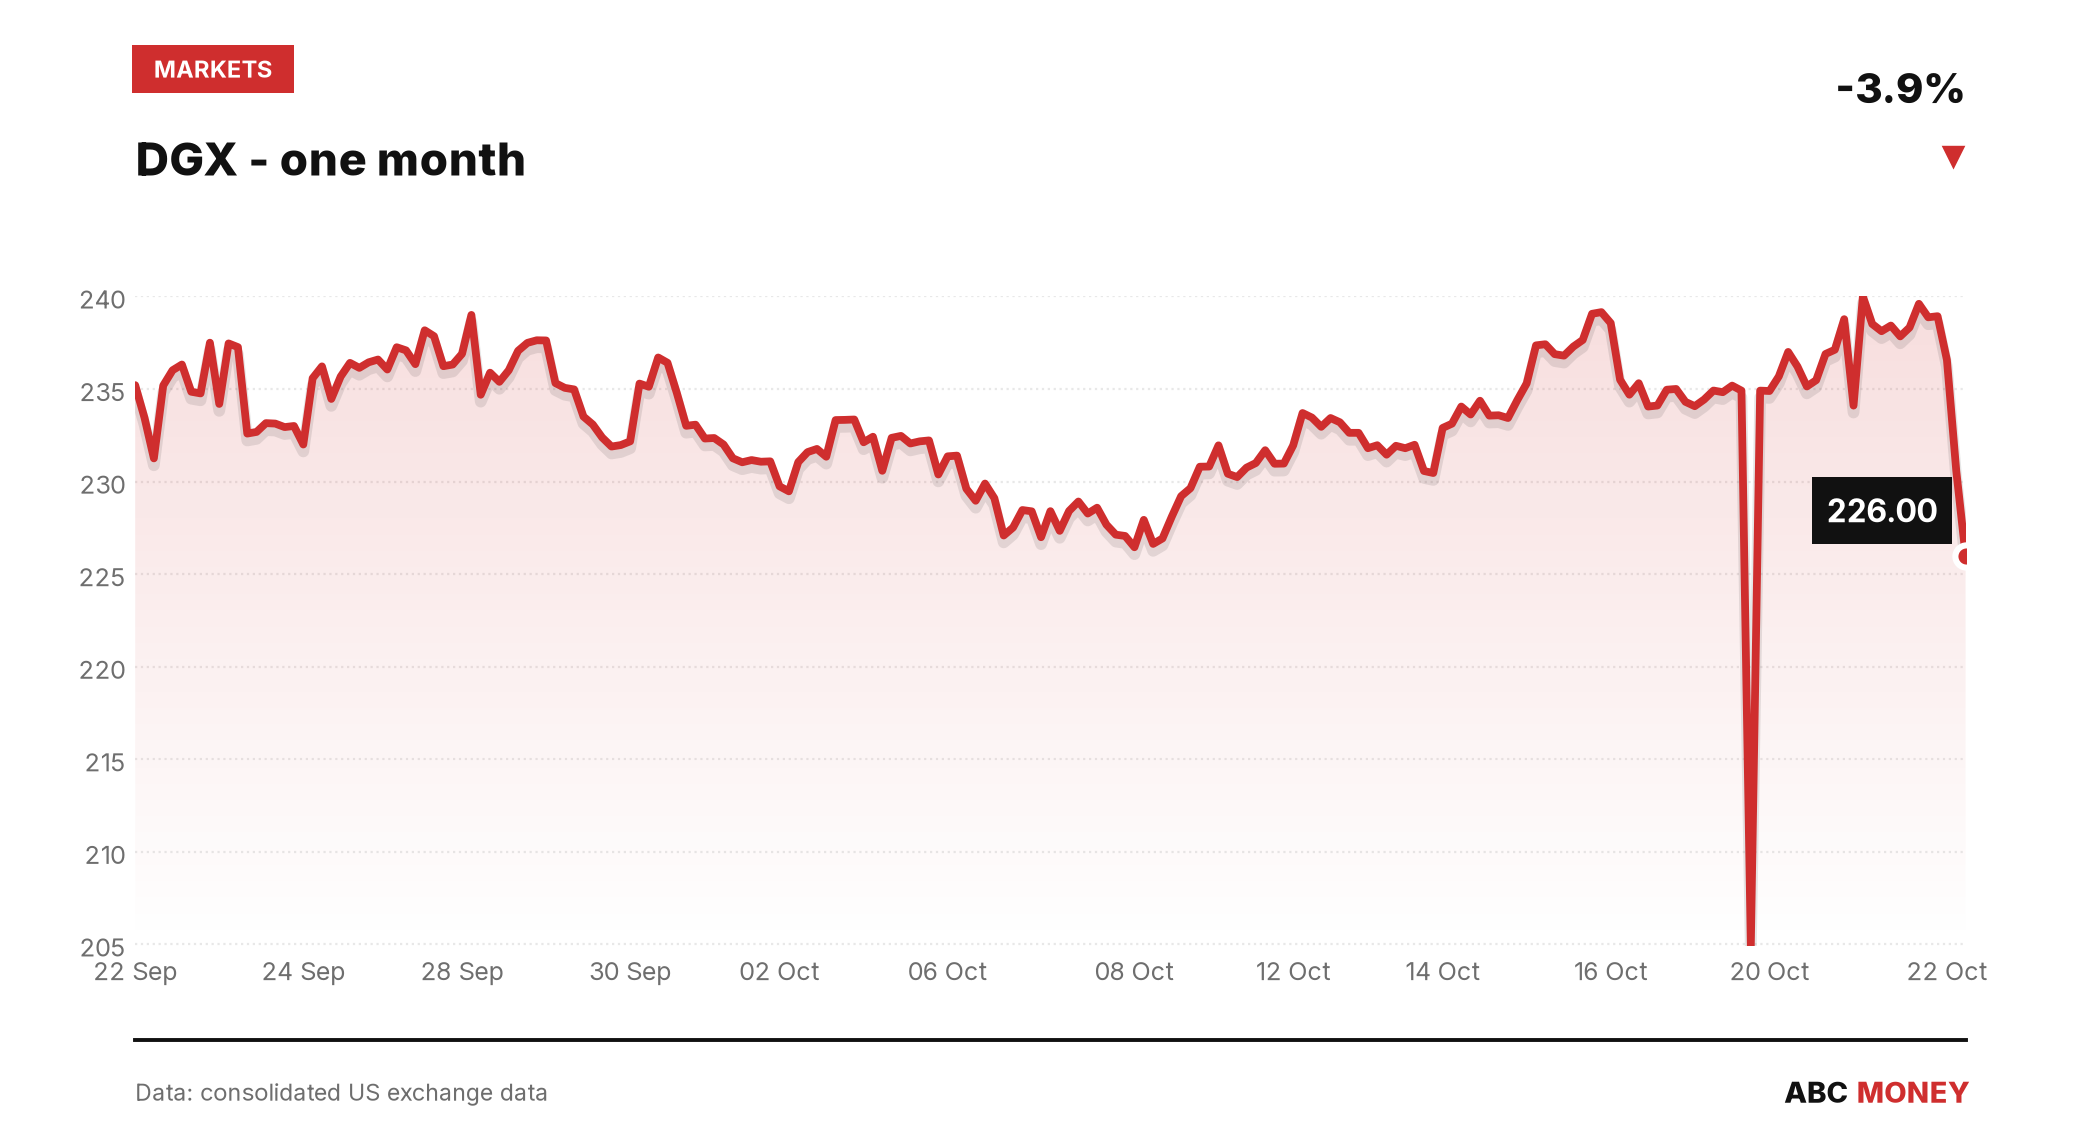
This was not a one-off upgrade. Quest lifted its full-year revenue range to $12.065bn-$12.105bn from a prior $11.95bn-$12.05bn, and nudged its adjusted EPS outlook up to $11.25-$11.35. That follows a similar move after second-quarter results in July, when the company had already raised its full-year revenue guidance to $11.95bn-$12.05bn from an original $11.78bn-$11.90bn, according to a release carried by Morningstar. Reported diluted EPS guidance for the full year now sits at $10.21-$10.31.
The underlying quarterly trend backs up the pattern rather than relying on any single print. Quest’s quarterly revenue has climbed in each of the past ten quarters on record, from $2.366bn in the first quarter of 2024 to $3.043bn in the second quarter of this year, before this quarter’s $3.10bn. Chief executive Jim Davis attributed the quarter to growth “on continued strength across our physician, hospital and consumer channels, complemented by productivity gains from automation and AI,” per the filing.
So why did the shares fall?
Nothing in the numbers points to an operational miss. The gap between a clean beat-and-raise and a falling share price looks instead like a valuation story. Research outlet GuruFocus pegged Quest’s fair-value estimate at $197.74 even after the print, implying shares were trading roughly 20.8% above that level, a point it raised in a note on the results. For a stock that had already run up over recent months, a strong quarter may simply have been the trigger for profit-taking rather than a surprise in itself.
The broader rate backdrop does Quest no favours either. The 10-year US Treasury yield stood at 5.15% as of 19 October, up from 5.09% the previous reading, according to data from the Federal Reserve Bank of St. Louis. Higher long-term yields tend to weigh more heavily on richly valued, steady-cash-flow healthcare names, since investors can get more from holding safer government debt instead – a dynamic that can compress share prices even when the earnings themselves are solid. A separate report on the day’s trading, carried by Investing.com, likewise framed the drop as a reaction despite the beat rather than because of any flaw in it.
What the quarter actually changed
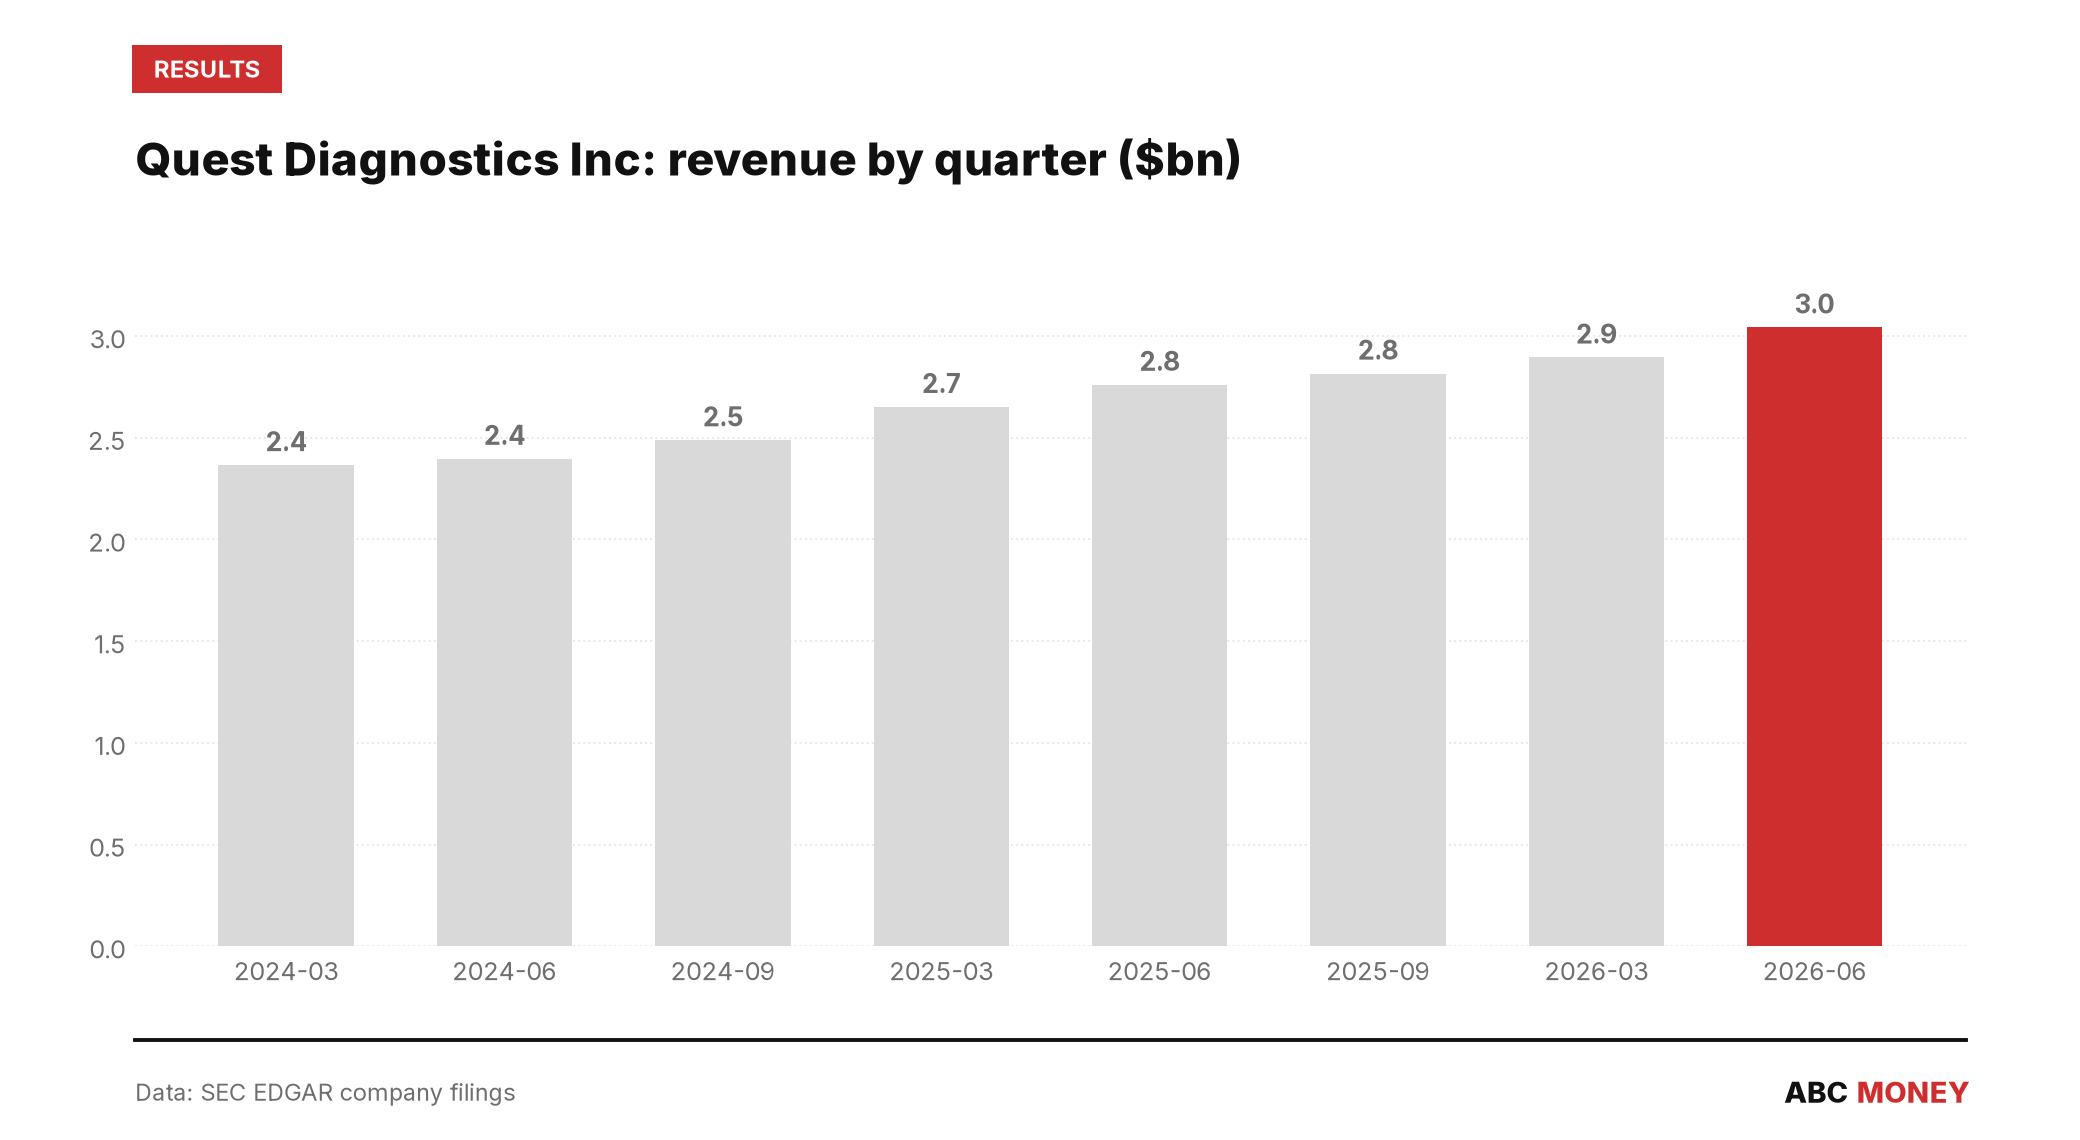
For investors parsing the release rather than the share-price reaction, the substance is straightforward: Quest grew revenue by double digits, expanded margins enough to push adjusted EPS up faster than sales, and raised its own full-year targets for the second consecutive quarter. Reported EPS growing faster than adjusted EPS – 28.7% versus 15.4% – suggests some of the quarter’s strength came from items excluded from the adjusted figure, such as tax effects or one-off gains, though the underlying adjusted trajectory still points comfortably upward.
None of that resolves the valuation question GuruFocus raised, and it is that question – not the quarter itself – that looks to be driving the share-price move. With guidance now raised twice this year and consensus already cleared twice over, the market’s attention shifts to whether Quest can keep growing into a share price that, even after Thursday’s fall, remains well above where it stood at the start of the year.
This article is for information only and is not investment advice or a recommendation to buy or sell any asset. Markets move quickly; figures are correct as sourced at the time of writing. Always do your own research before making financial decisions.