Marvell to Buy Lumentum in $115bn All-Stock AI Deal
The Marvell Lumentum merger values the optics maker at $115bn, but the all-stock deal leaves holders exposed to Marvell's share price until 2028.
In this article 3 sections
Marvell Technology has agreed to buy Lumentum Holdings (NASDAQ: LITE) in an all-stock Marvell Lumentum merger valued at $115bn including debt, the two companies said, in a deal that would weld together one of the chip industry’s fastest-growing AI networking businesses with a dominant supplier of the optical components that move data between racks of AI processors. The boards of both companies approved the agreement unanimously, according to the companies’ statement reported by Investing.com.
Under the terms, each Lumentum share converts into 4.5 Marvell shares, implying a value of roughly $1,132 per Lumentum share and a premium of about 23.9% to the stock’s last unaffected close, according to Marvell’s investor relations announcement. Once the deal closes, existing Marvell shareholders would own about 67% of the combined company and Lumentum holders roughly 33%, on a fully diluted basis – a term that, in plain English, means the ownership split accounts for all shares that could eventually be issued, including those tied to options and awards, not just the shares outstanding today.
The headline $115bn figure is worth unpacking before anyone treats it as the cheque Marvell is writing. That number is an enterprise value – it bundles in Lumentum’s debt alongside the value of the shares changing hands. The actual stock consideration being handed to Lumentum holders is closer to $102.54bn, according to Reuters reporting carried by MarketScreener. It’s a modest but meaningful distinction: the bigger number makes for a cleaner headline, the smaller one is closer to what’s actually being exchanged.
A fixed ratio, not a locked-in price
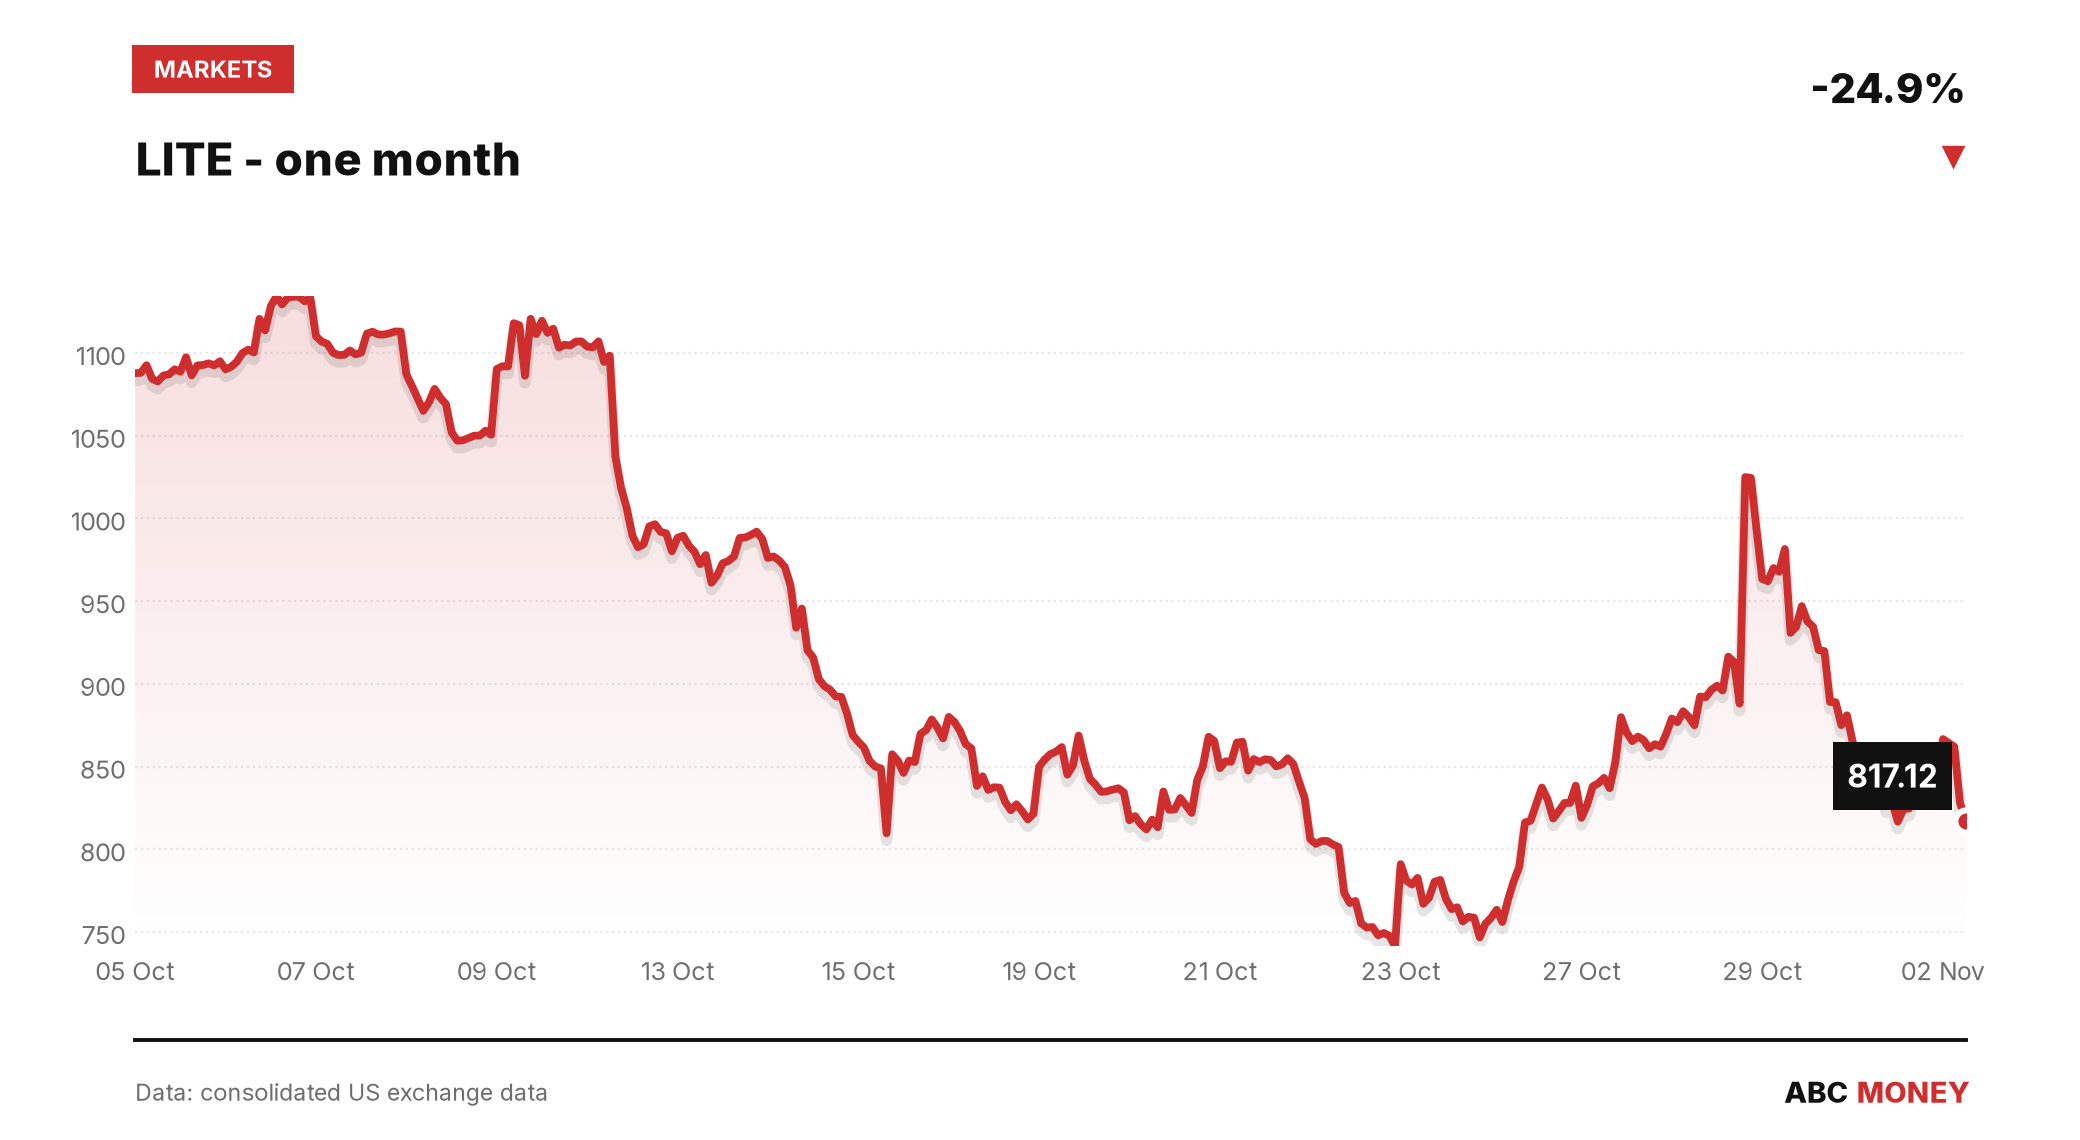
Because the consideration is set in Marvell shares rather than cash, the deal’s value to Lumentum holders will keep moving with Marvell’s own stock price between now and completion – which the companies expect in the first half of 2028, pending shareholder and regulatory sign-off, according to TokenPost. That is a long runway for a semiconductor deal, and it means Lumentum investors are less banking a premium today than making an 18-month-plus bet on where Marvell’s stock lands by closing.
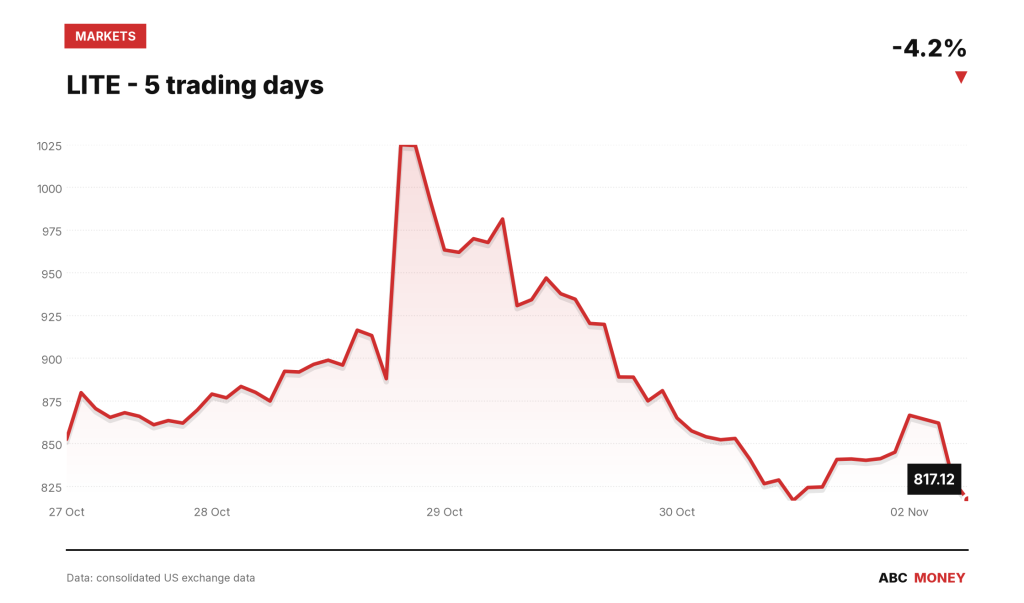
Lumentum shares were halted pre-market pending the announcement after trading as much as 2.5% higher earlier that morning, Investing.com reported, which is why the stock’s last recorded print of $818.02 – down 2.64% on the day and roughly 20% below its 20-day high of $1,025 – doesn’t yet reflect the deal’s implied value. Marvell’s own share price, in other words, is now the thing to watch, since it sets the real exchange rate for the transaction every day until it closes.
FINRA’s daily short-sale data shows some of that tension building before the announcement went official. Lumentum’s short ratio – the share of daily trading volume attributable to short sales, where investors borrow and sell stock betting the price will fall – eased from 0.665 on 27 October to 0.423 by 30 October, according to FINRA’s short sale volume data, consistent with speculation building into the deal rather than against it.
From loss-maker to AI beneficiary
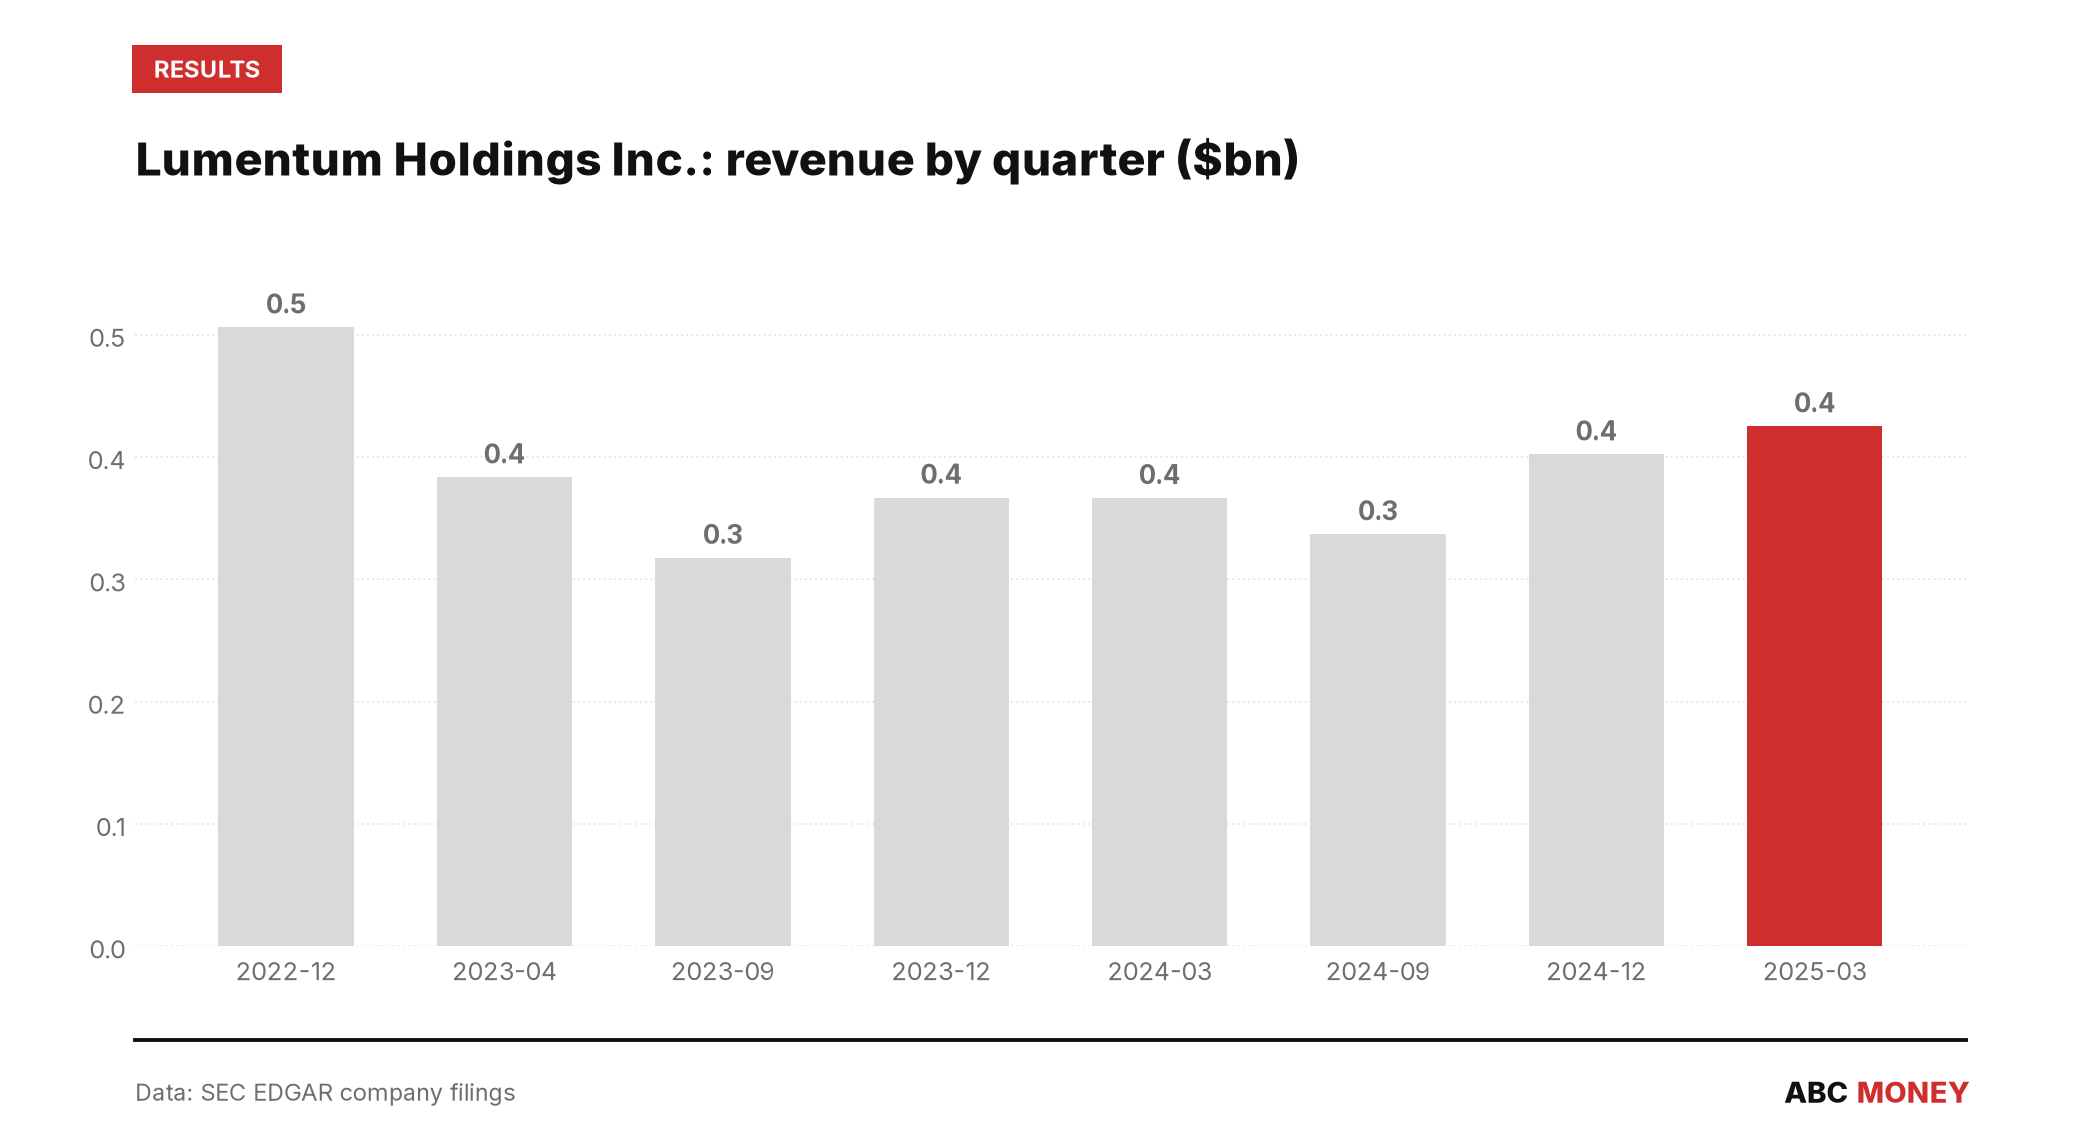
The deal caps a sharp turnaround in Lumentum’s own numbers. The company was still posting quarterly losses as recently as its fiscal 2025 third quarter, with diluted earnings per share of negative $0.64, following a run of red ink that included a loss of $1.47 a share in the December 2023 quarter and $1.88 in the following quarter, according to Lumentum’s SEC filings. The company swung to a modest profit by its fiscal 2026 first quarter and kept building from there, reporting diluted earnings per share of $0.89 in the following quarter and $1.50 by its fiscal 2026 third quarter, filings show. Net income over the same run went from a $99.1m loss to income of $144.2m, according to EDGAR records – the kind of trajectory that tends to attract a buyer rather than merely survive as one.
The strategic logic sits squarely in the AI infrastructure build-out. Marvell and Lumentum together are pitching a combined addressable market of roughly $550bn and more than $1bn in annual run-rate cost savings, according to Reuters. It would be Marvell’s largest acquisition since its $10bn purchase of Inphi in 2021, and arrives months after Nvidia took $2bn stakes in each of Marvell and Lumentum separately, underlining how central optical connectivity has become to the economics of AI data centres. A proposed US ban on new Chinese optical transceivers could add further tailwind, potentially steering demand toward domestic suppliers like the combined group, per Reuters reporting via The Globe and Mail.
What investors are watching now
Marvell’s chief executive, Matt Murphy, would remain chairman and chief executive of the combined company, with three Lumentum directors – including its chief executive, Michael Hurlston – joining Marvell’s board, Investing.com reported. For now, the arithmetic that matters most to Lumentum holders isn’t the $115bn headline figure but Marvell’s own share price on the day the deal eventually closes, given how much ground remains between now and the first half of 2028.
This article is for information only and is not investment advice or a recommendation to buy or sell any asset. Markets move quickly; figures are correct as sourced at the time of writing. Always do your own research before making financial decisions.