
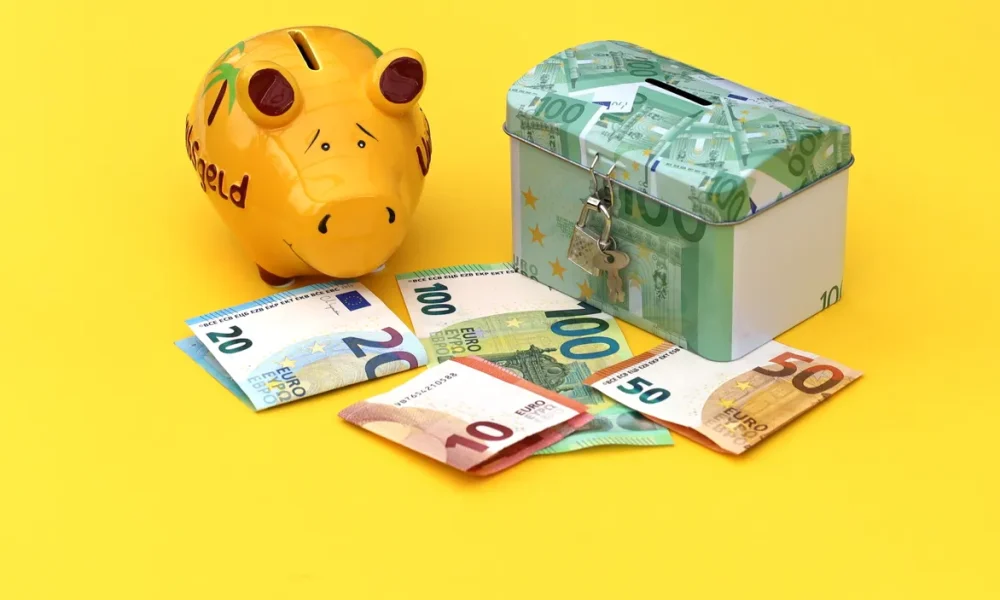
A child trust fund transfer into a Junior ISA could meaningfully improve returns for the millions of families still holding accounts that have effectively been left to stagnate since the scheme closed to new savers in 2011. With 758,000 CTFs unclaimed and a further pool of active accounts still running on legacy terms, the cost of inertia is rising.
What CTFs and Junior ISAs Actually Offer
Child Trust Funds were tax-free savings accounts opened for children born between 1 September 2002 and 2 January 2011, seeded with a government contribution of £250. Parents could add to them, choosing between cash and investment versions, with the money locked until the child turns 18. Junior ISAs replaced them in November 2011, but CTFs were not converted automatically: they simply continued under existing providers, many of whom shifted their commercial focus to the newer product.
The annual contribution limit is £9,000 for both account types, and both are free from UK income tax and capital gains tax on returns. The practical differences, however, have widened considerably over time.
Most Junior ISAs can be opened and managed online. Some CTF providers still operate largely by post or phone. And because CTF accounts do not automatically convert to adult ISAs at maturity (Junior ISAs do), an unclaimed or unmanaged CTF can sit idle, earning whatever rate the provider applies by default, with no prompt to act.
The Fee Gap on Investment Accounts
For families in cash accounts, the rate difference is real but moderate. Yorkshire Building Society’s now-closed CTF currently pays 3.65%, dropping to 2.35% after maturity. On a typical CTF pot of £2,200, that produces £80 of interest in a year, falling to £51.70 once the account matures. Leek Building Society’s top cash Junior ISA rate is 3.85%, which would generate £84.70 on the same pot, around £30 more per year under a matured rate comparison.
The investment side is where the gap becomes structurally harder to ignore. HMRC placed millions of children into default stakeholder CTF accounts, typically invested in basic UK tracker funds, with annual charges capped at 1.5% per year. That cap was a ceiling, not a promise of efficiency.
Antonia Medlicott, founder of Investing Insiders, puts the compounding effect in context: ‘Over 15 years, the average fund in the Investment Association’s global sector grew by around 240%, while stakeholder CTF returns tracked closer to the far more modest bond and mixed-investment sector averages. That’s two decades of compounding working against these children rather than for them.’
A stocks and shares Junior ISA from a mainstream platform can cost between 0.15% and 0.35% per year in platform fees before underlying fund charges. AJ Bell charges 0.25% annually (capped at £2.50 per month) for funds, with a £1.50 dealing charge per fund trade. Hargreaves Lansdown charges no platform fee and no trading fee on funds for its Junior ISA, with indicative portfolio fees of £0 across portfolio sizes from £1,000 to £50,000, according to Trust Intelligence. Hargreaves Lansdown’s Junior ISA also converts into a regular stocks and shares ISA when the child turns 18, with Direct Debits available from £25 a month.
AJ Bell calculates that investing £500 a year from birth could grow to almost £15,000 by age 18, assuming 5% annual returns and excluding platform charges. The drag of a 1.5% annual fee versus 0.25% compounds materially over an 18-year horizon.
Alice Haine, head of personal finance at Hargreaves Lansdown, highlights an additional structural advantage: ‘A child can only hold one CTF and switching between cash and investments may require a transfer to another provider. With a JISA, a child can hold both a cash Junior ISA and stocks and shares one simultaneously, with the savings limit split between the two as desired. So there can be benefits to transferring across.’
Making a Child Trust Fund Transfer
The process requires the registered contact (usually a parent, or the child once they turn 18) to complete a transfer form with the chosen new provider. You will need your child’s Unique Reference Number, found on the annual CTF statement, plus details of the account type and existing provider. The CTF must be transferred in full and closed: you cannot hold both accounts simultaneously.
If the account details have been lost, GOV.UK’s CTF locator can identify the provider using a National Insurance number, though it does not disclose the balance held. Transfers typically take between two and six weeks. Some platforms offer cashback incentives for incoming transfers.
OneFamily, one of the larger CTF administrators, moved 1.3 million policies from legacy systems onto a new platform in 2023, according to its entry on the FCA Mutuals Public Register. The scale of that migration reflects how much of the CTF estate remains in the hands of a small number of specialist providers, not the mainstream investment platforms competing hardest on price and product range.
Before transferring, compare charges, investment options, platform usability, and whether the receiving provider accepts CTF transfers (not all do). The fee difference alone makes the exercise worth an hour of research. For families sitting in a 1.5% stakeholder account with a decade or more still to run, the arithmetic is not close.

 Bitcoin
 Ethereum
 Tether
 BNB
 USDC
 XRP
 Solana
 TRON
 Lido Staked Ether
 Cardano
 Gram (prev. Toncoin)
 Avalanche