 Bitcoin
 Ethereum
 Tether
 BNB
 USDC
 XRP
 Solana
 TRON
 Lido Staked Ether
 Cardano
 Gram (prev. Toncoin)
 Avalanche
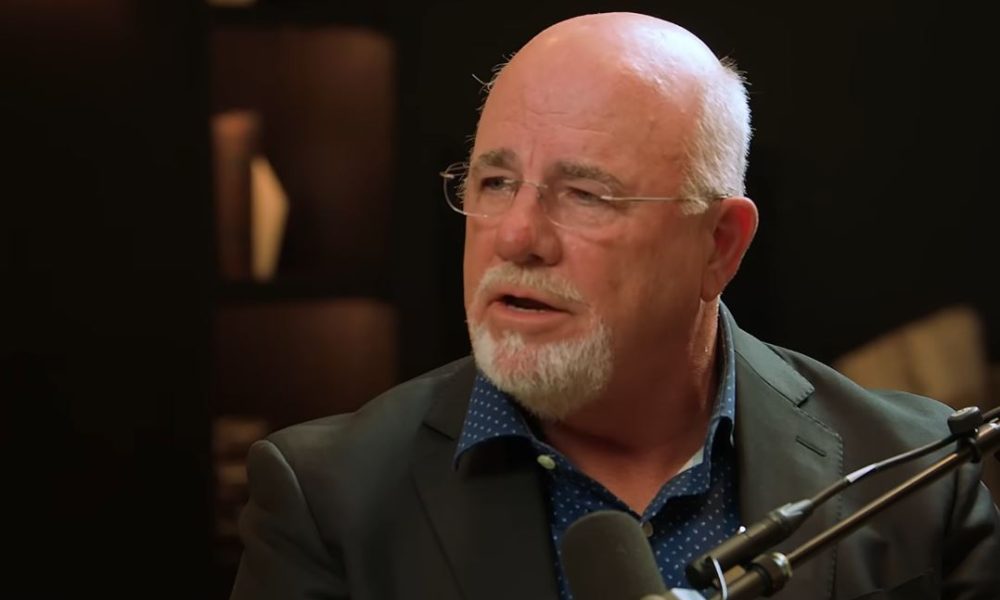
Dave Ramsey’s $18 Million Stock Advice: Why He Told This Seattle Mom to Sell Even If It Costs Her
Most people discover misplaced cash in old birthday cards or coat pockets. In a long-forgotten tech stock account, 50-year-old Seattle homeschooling mother Sarah discovered $18 million. It’s the kind of story that seems almost too good to be true until you realize that the windfall isn’t the punchline. It’s what follows.
With what she awkwardly described as a very good problem, Sarah called The Ramsey Show. When she was expecting her first child, she quit her job at a tech company more than 20 years ago, and she essentially never looked back. For years, the employee benefits account was largely inactive.
She eventually mentally filed it away and stopped thinking about it. After that, the stock surged, with many speculating that it was Nvidia due to its remarkable performance during the AI boom. What was once hardly noticeable had risen to about $18 million. She purchased shares for about $14. After several stock splits, the math had accomplished something remarkable without her help.
Her husband’s tech salary, which is about $250,000 annually, still provides for her family. She had not changed her way of life. The money had not been moved by her. For twenty years, she just sat on it, not really on purpose.
Dave Ramsey responded in a straightforward, almost blunt manner. He described investing all of your money in a single company’s stock as “scary and unwise.” He didn’t celebrate for very long. He swiftly highlighted the danger, pointing out that a stock valued at $18 million might drop to $3 tomorrow. It has previously occurred to well-known businesses. The pattern remains the same, but the names change.
His main recommendation was to diversify and begin selling, distributing the funds among 90 to 200 different stocks or mutual funds. Not all at once, not carelessly, but urgently. It is complicated by the tax situation. Selling results in long-term capital gains taxes, which can reach 20% at the federal level and an additional 7% in Washington State. Sarah’s rate increases from 15% to 20% on everything above the $583,000 income threshold for married filing jointly if she sells too much in a single year. Ramsey admitted that this is not a minor issue. However, he was clear about his priorities. He told her straight out, “I would rather have the safety than the extra 20 percent.”
It’s important to remember that not all finance professionals hold this opinion. Broad diversification was famously dismissed by Charlie Munger as a tactic for inexperienced individuals. Similar remarks were made by Mark Cuban. For their target audience, which consists of knowledgeable investors with the temperament to withstand severe volatility and a thorough understanding of a company, they are not incorrect. However, Ramsey’s argument is more difficult to refute for a homeschooling mother on a single-income household who didn’t realize the account existed.
Before making any big decisions, Ramsey advised her to consult a qualified tax planner and investment advisor. He wasn’t dismissive of the tax bill; rather, he didn’t want her to remain vulnerable out of fear. Being tax-smart and being tax-paralyzed are two different things, and Sarah was in danger of becoming the latter.
This story subtly highlights a point that most financial advice ignores: concentration risk can accumulate over years without anyone actively choosing it. Sarah had no intention of investing her family’s financial stability in a single business. Time took care of that for her. The real story now starts with the difficult, unglamorous task of unwinding it carefully, deliberately, and with a true professional.