HCA Healthcare launches fresh senior notes offering
HCA's senior notes offering is the hospital group's latest debt raise, arriving as Q3 profit rises and Treasury yields stay near 5%.
In this article 3 sections
HCA Healthcare’s financing subsidiary is going back to the bond market. The hospital operator said its wholly owned unit, HCA Inc., proposes to offer senior notes – unsecured bonds that sit behind secured debt but ahead of shareholders in a default – with the size, maturity and interest rate still to be fixed once the deal is actually priced. Seeking Alpha carried the same announcement within minutes of the original release.
The company says net proceeds will go toward “general corporate purposes,” which it notes may include redeeming all or part of existing notes – corporate shorthand for refinancing older, possibly more expensive debt with new paper, rather than funding anything unusual.
A well-worn playbook, not a distress signal
This is not HCA’s first trip to this well. The investor relations archive shows an essentially identical “proposed public offering of senior notes” announcement from HCA Inc. in October 2025, and another in April 2026, both using the same template language. HCA has run variations of this manoeuvre since at least 2016, when it announced a $1.0bn senior secured notes offering in the same format. Routine refinancing of this kind is standard fare for a highly leveraged hospital operator with predictable cash flows, and nothing in the release points to anything more pressing.
What’s notable is the backdrop the company is issuing into. The announcement landed a day after HCA filed its third-quarter 10-Q, which showed net income of $1,579,000,000 on revenue of $19,849,000,000 for the three months to 30 September 2026. Diluted earnings per share came in at $7.27, up from $6.96 a year earlier. That continues a steady climb: quarterly revenue has risen from $17,492,000,000 in the second quarter of 2024 to just shy of $20bn in the most recent quarter, with net income holding consistently above $1.4bn every period along the way. A company issuing debt from that kind of run is doing so by choice, not necessity.
Borrowing against a backdrop of stubborn yields
Where it gets more interesting is the rate environment HCA is pricing into. The 10-year US Treasury yield – the benchmark against which corporate bond coupons are ultimately set – stood at 4.98% on 29 October 2026, the day before the announcement, having eased only marginally from 5.05%. The 2-year yield sat at 4.61%, leaving the gap between short and long maturities – the yield curve – at a modestly positive 0.38 percentage points. None of that is dramatic, but it does mean HCA is locking in new borrowing costs in a market that has not meaningfully cheapened from the elevated levels of the past couple of years. Refinancing older notes now only makes sense if the coupons being replaced are higher still, or if management simply wants to push maturities further out regardless of near-term rate levels.
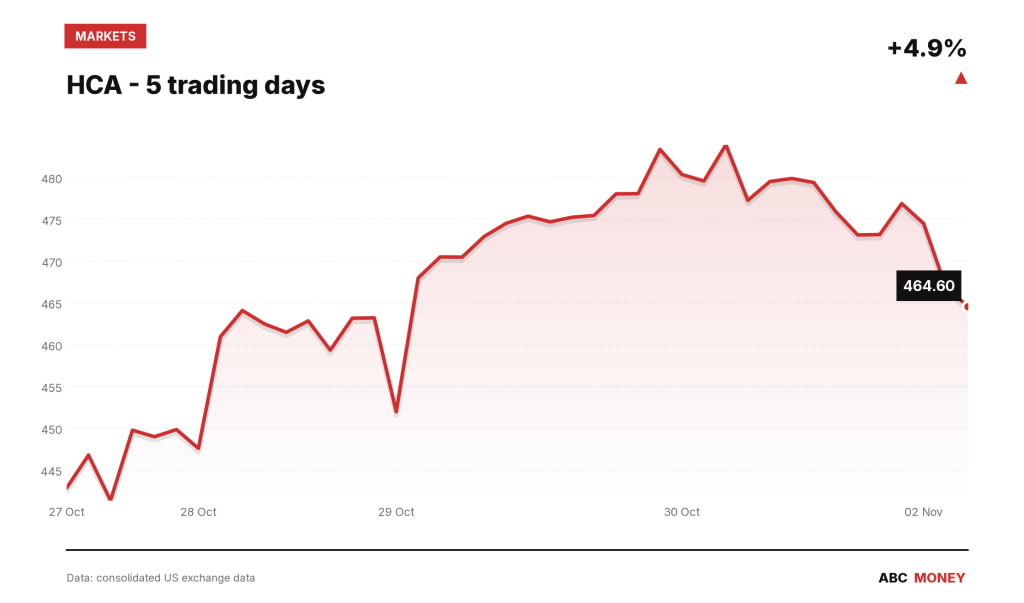
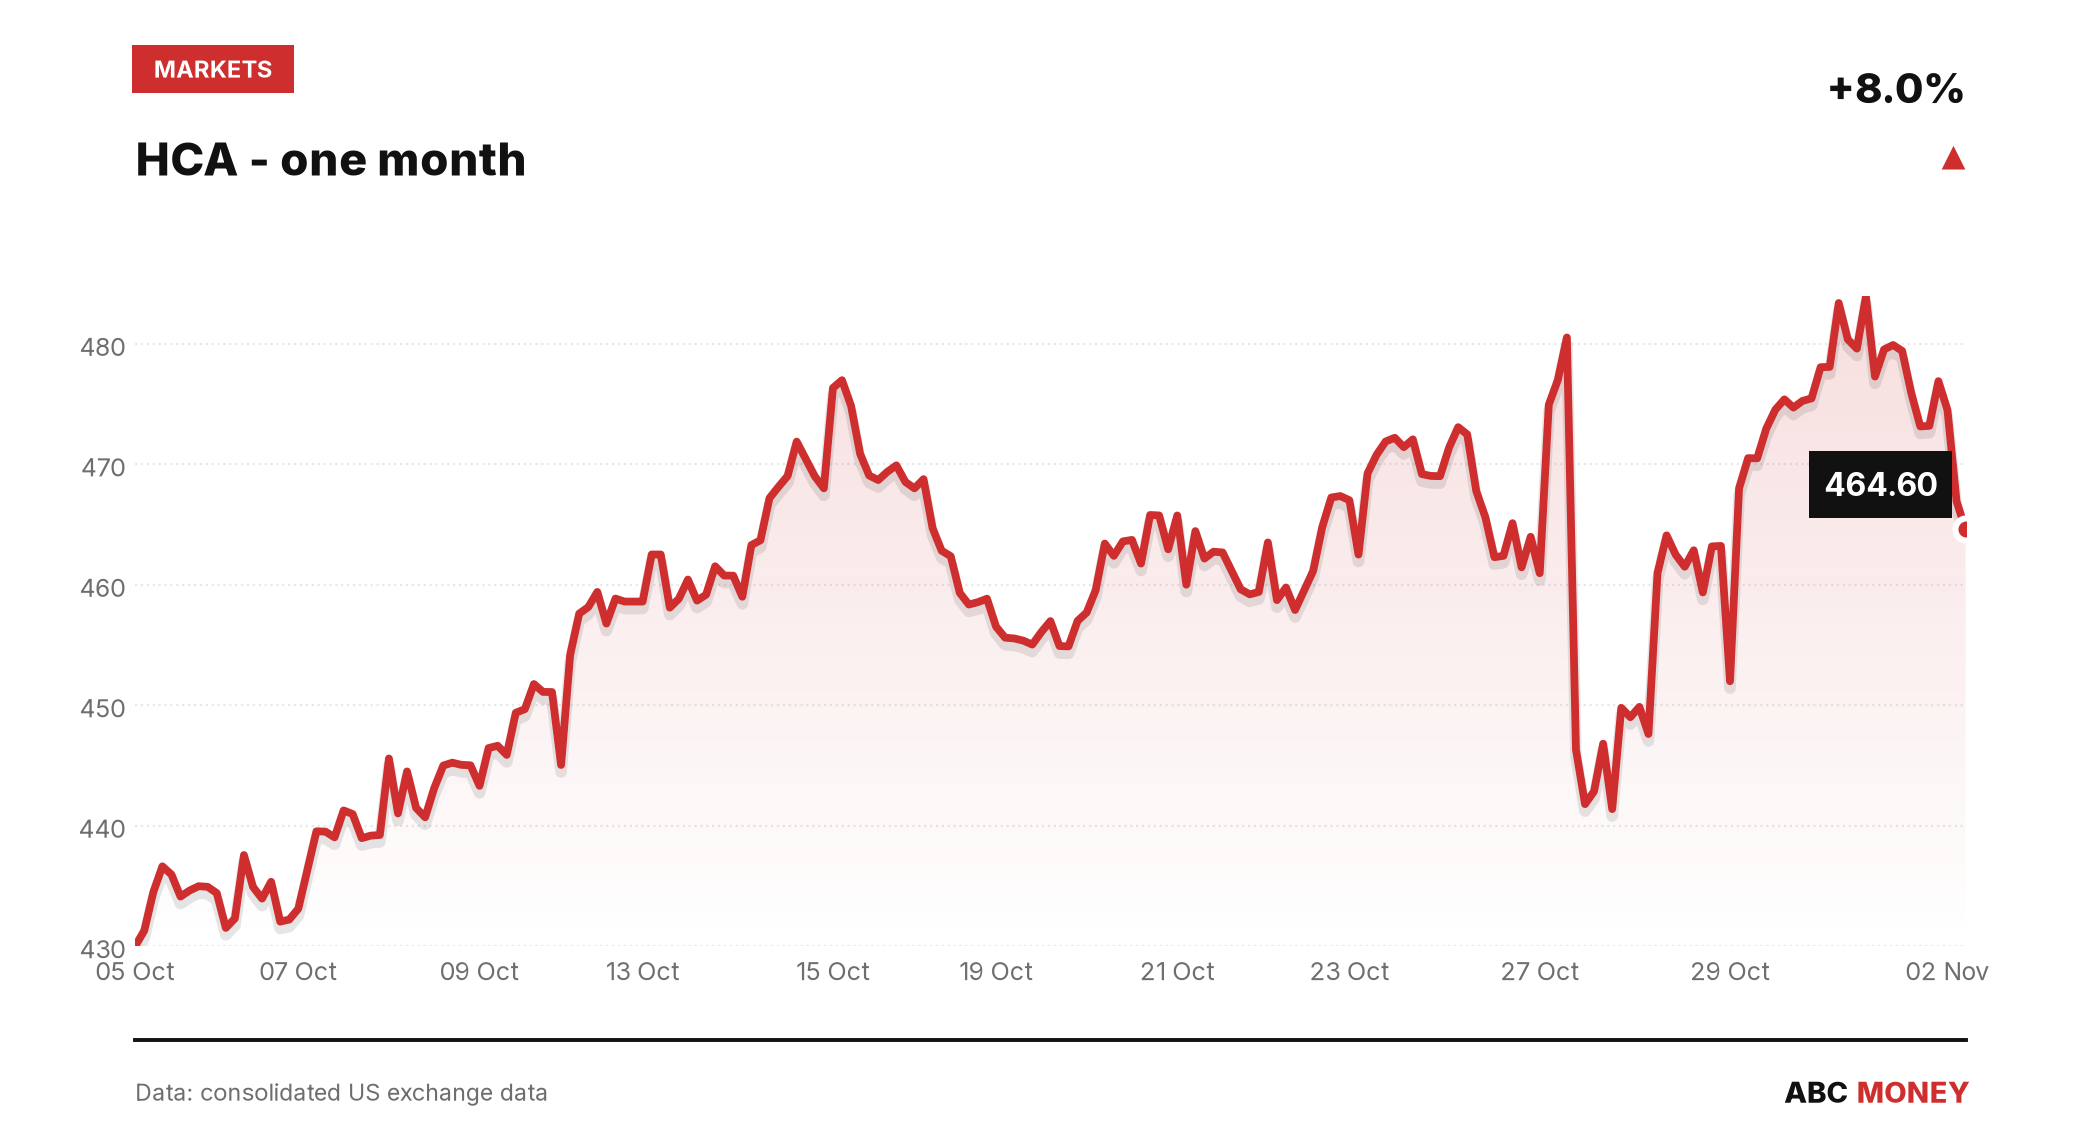
Shares in HCA Healthcare (NYSE: HCA) had fallen 3.66% over the 24 hours to $461.85 by mid-afternoon on 2 November 2026, pulling back from a 20-day high above $483 but still roughly in line with where the stock traded three weeks earlier. Trading volume ran at about three-quarters of its 20-day average, a sign the move reflected ordinary portfolio repositioning rather than a rush for the exits. Daily short-sale activity tracked by FINRA offers a similar read: the short-volume ratio – the share of trading volume attributable to short sales, where traders borrow stock to sell it in anticipation of a lower price – sat at 0.641 around the announcement date, comfortably within the 0.382-to-0.773 range it had occupied over the prior fortnight. There was no spike in bearish positioning timed to the notes news.
What the deal signals about HCA’s balance sheet
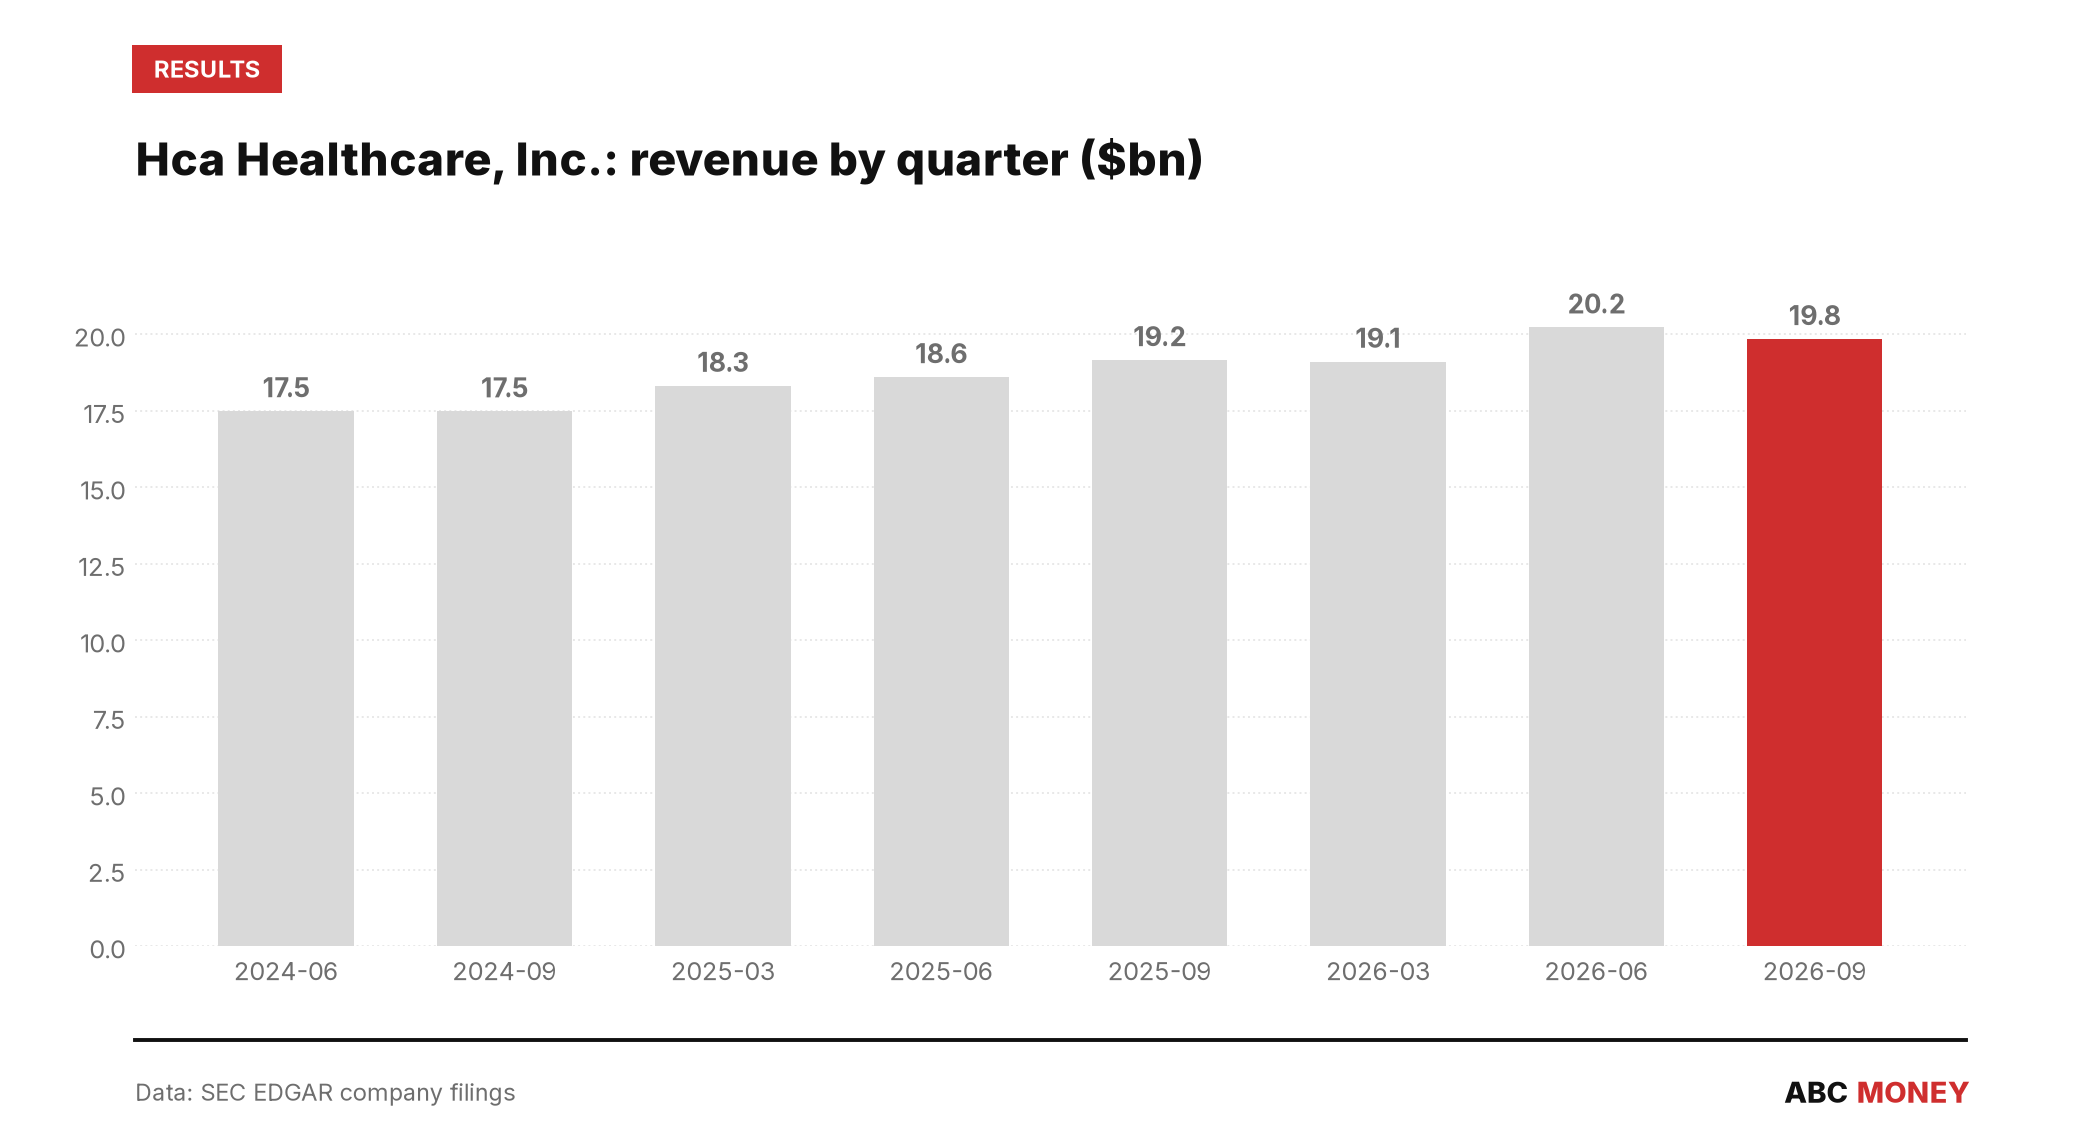
For bondholders and equity investors alike, the more useful signal is what this offering is not: it is not an emergency liquidity raise, and it is not evidence of strain. HCA has described proceeds in near-identical language across multiple issuances over the past year, each time pointing to general corporate purposes and potential redemption of existing notes. Set against rising quarterly revenue, EPS growth of roughly 4% year-on-year in the third quarter, and a share price that has barely moved on a one-month view, the pattern reads as a large, consistently profitable borrower managing its debt stack opportunistically rather than defensively.
The terms that matter now – coupon, maturity and size – will only become clear once the deal prices, typically within days of an announcement like this one. Bond investors will be watching where HCA Inc. settles its coupon relative to the roughly 5% Treasury backdrop, and whether the proceeds are earmarked to retire a specific tranche of existing notes once the pricing supplement is filed.
This article is for information only and is not investment advice or a recommendation to buy or sell any asset. Markets move quickly; figures are correct as sourced at the time of writing. Always do your own research before making financial decisions.