 Bitcoin
 Ethereum
 Tether
 BNB
 USDC
 XRP
 Solana
 TRON
 Lido Staked Ether
 Cardano
 Gram (prev. Toncoin)
 Avalanche
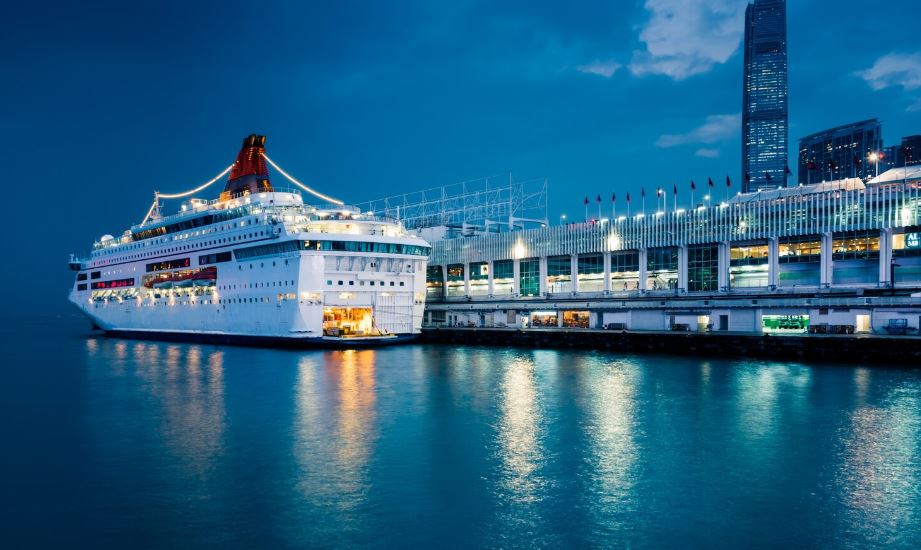
Bank of America Cruise Stock Buy: Why Wall Street Sees Royal Caribbean as a Bargain After a 26% Drop
A specific type of Wall Street moment occurs when a company is doing well but its stock is still declining. It is referred to as a disconnect by analysts. It is sometimes referred to as confusing by regular investors. In late September 2026, Bank of America referred to it as a purchasing opportunity. After shares fell about 26% from their late-summer peak, the bank upgraded Royal Caribbean Cruises – NYSE: RCL – from Neutral to Buy. It set a price target of $330 and argued that the selloff has pushed valuations into territory that doesn’t reflect what the company is actually doing.
A valuation argument lies at the core of the Bank of America cruise stock purchase thesis. The decline caused Royal Caribbean’s projected enterprise value-to-EBITDA multiple for 2027 to fall below 10x. Just to put things in perspective, that same multiple had recently been sitting at about 12x. That type of compression seems at least worth a second look for a business with returns on invested capital in the high teens and EBITDA margins of almost 40%. The company has hedged over half of its fuel exposure for 2027, and the balance sheet has an investment-grade rating. This is significant because fuel prices are currently one of the key factors influencing cruise stocks.
The discrepancy between the company’s reporting and what the stock price has been indicating is difficult to ignore. According to data from Bank of America, travel expenditures have been increasing at a mid- to high-single-digit rate since February. In July and August, cruise spending in particular picked up speed again, reaching mid-teens growth. At a recent Bank of America conference, Royal Caribbean’s own commentary highlighted consistent demand, which gave the bank’s analysts enough confidence to forecast net yield growth of at least 4% in the fourth quarter—the highest anticipated number for the cruise industry. That isn’t a tale of a business collapsing. It tells the tale of a stock that was caught in a larger selloff and priced in a lot of unfavorable news that might not materialize.
The $3 billion deal Royal Caribbean announced to purchase a 50% share in Sandals Resorts is the other, and more intriguing, component of the Bull case. A cruise ship operates in a different physical world than Sandals, the all-inclusive Caribbean brand known for its instantly identifiable blue and yellow branding. Land-based properties, fixed assets, and the inability to sail elsewhere during hurricane seasons.
Bank of America publicly identified those risks. However, the analysts also noted that the deal increases Royal Caribbean’s near-term EBITDA by 3% to 4% at a price of about 10x 2027 EBITDA, or about $1 million per room. Additionally, there is a realistic way to increase the Sandals operation’s current EBITDA of about $600 million to $900 million by 2030 if the company applies its supply chain efficiency, loyalty program, and pricing discipline.
The Sandals wager might pay out more than the market anticipates right now. During a severe Atlantic hurricane season, the fixed-asset exposure might also become problematic. Bank of America didn’t act as though this uncertainty didn’t exist. The bank did contend that the risk-reward ratio significantly favors buyers at the current prices.
Here, too, the larger context is important. The other well-known brand in the industry, Carnival Corporation, has a Buy rating from Bank of America as well, with a $38 price target and valuations that are less than seven times the bank’s 2027 EBITDA projections. According to reports, Carnival’s 2027 booking curves are at all-time highs, and despite widespread worries, industry demand signals have continuously been robust. After being left for dead during the pandemic shutdowns of 2020 and 2021, the cruise industry has spent the years rebuilding capacity, paying off debt, and observing that customers are still willing to spend money on travel experiences. The valuation dislocation in some of these names is new news, but the recovery itself is no longer.
The Bank of America cruise stock buy call on Royal Caribbean ultimately boils down to a simple wager: that the strengths, such as margins, demand, and the Sandals deal, are not fully priced in, while the concerns driving the selloff, such as fuel costs, Caribbean capacity growth, and macroeconomic uncertainty, are. Over the next twelve months, a number of factors that no analyst can completely control will determine whether or not that reading turns out to be accurate. However, the bank appears at ease with that uncertainty at about 36% implied upside to the $330 price target. Investors will have their own opinions when determining whether or not to agree. The underlying business’s numbers, at the very least, make the case compelling.