Clorox Q1 Earnings Beat Masks a GOJO-Sized Catch
Clorox Q1 earnings beat Wall Street forecasts on EPS and sales, but the GOJO acquisition did almost all the heavy lifting.
In this article 3 sections
Clorox Q1 earnings cleared Wall Street’s bar this week, but the headline beat owes almost everything to September’s acquisition of hand-sanitiser maker GOJO Industries, not underlying demand for bleach and bin bags.
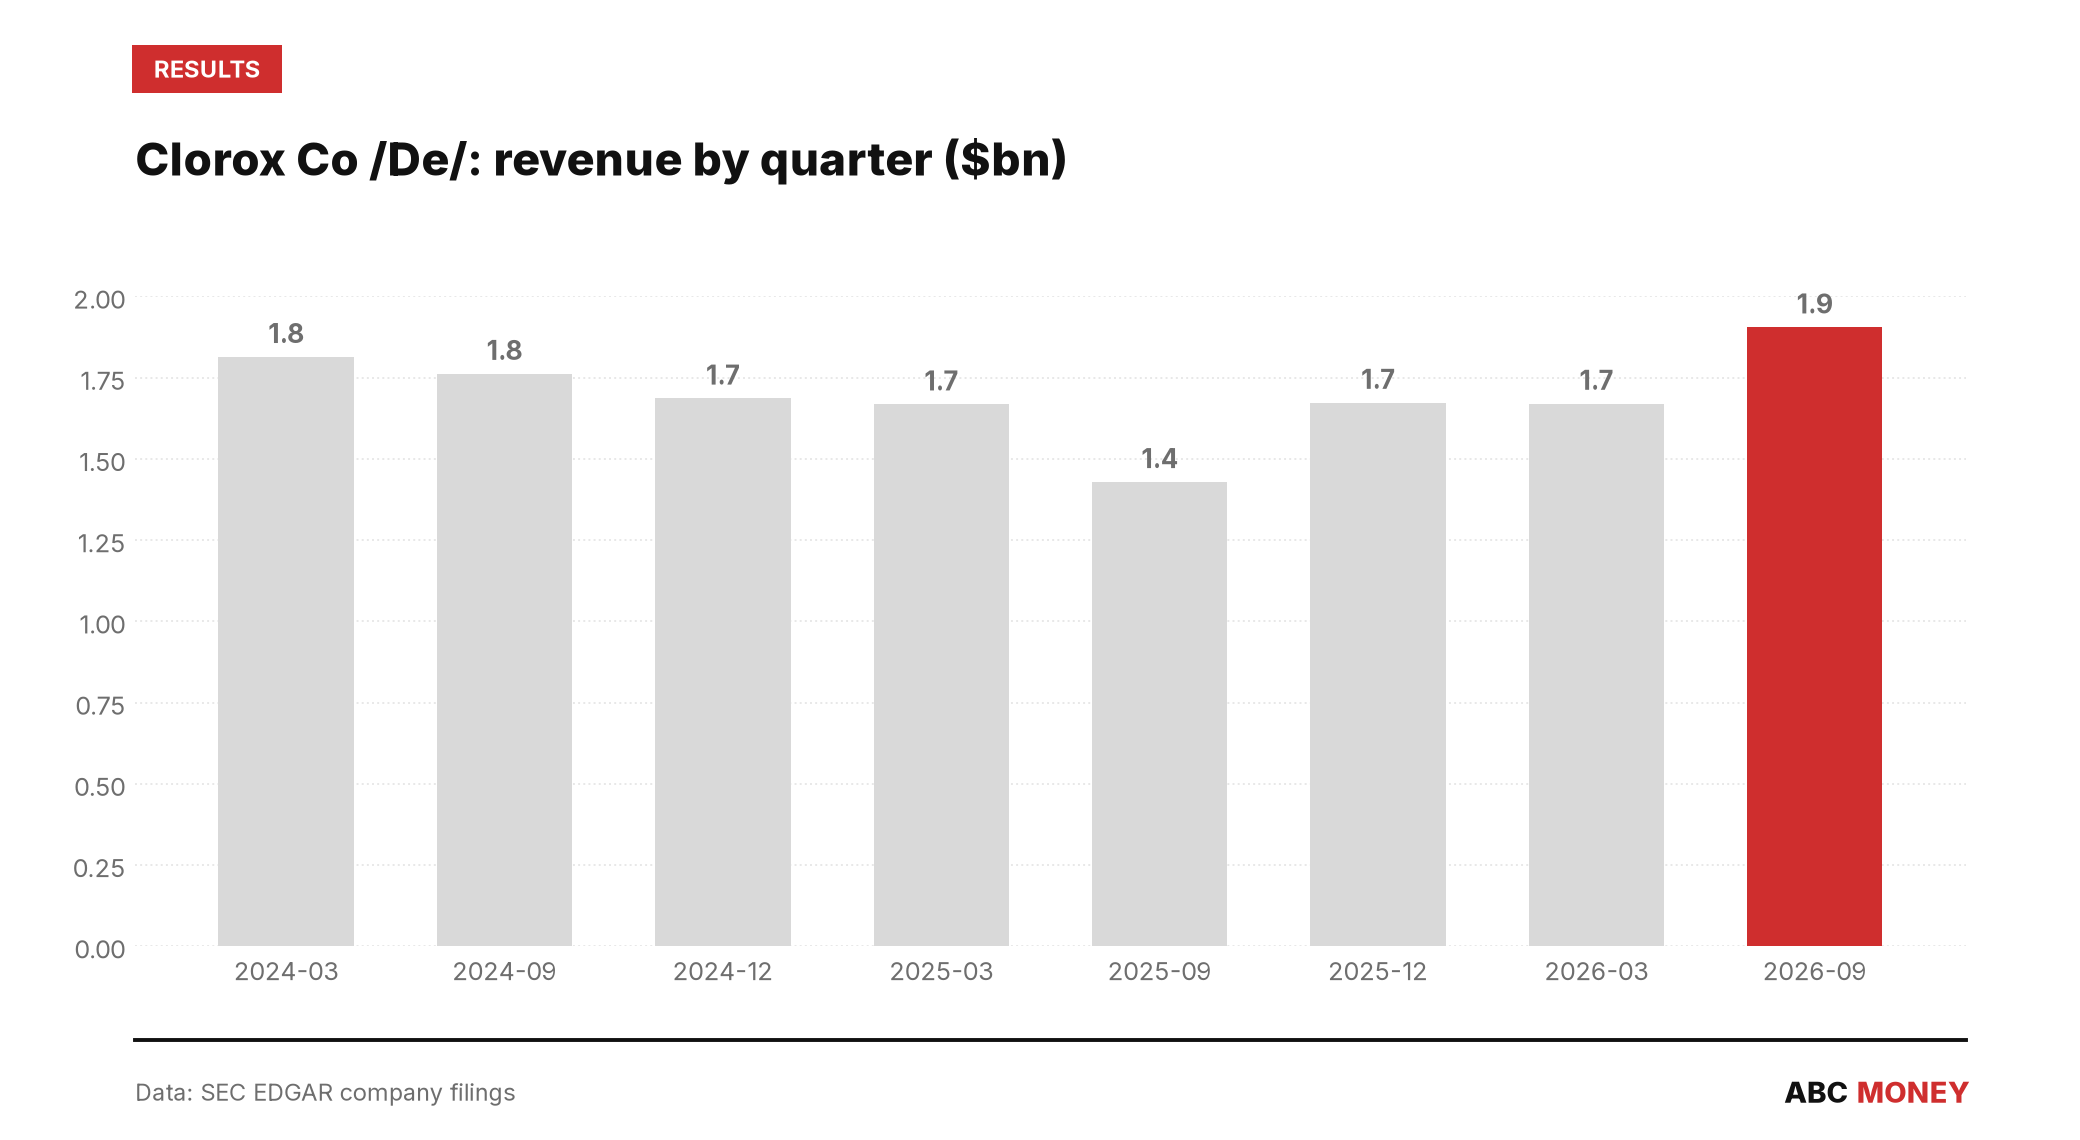
The maker of Clorox wipes, Pine-Sol and Burt’s Bees reported diluted earnings per share of $1.39 for the quarter ended 30 September 2026, more than double the $0.65 it posted a year earlier, according to its quarterly filing with the SEC. Net sales rose 33% to $1.905bn, edging past the roughly $1.89bn analysts had pencilled in, while net income attributable to shareholders came in at $170m, up from $80m a year earlier.
Strip out one-off items and the picture looks even punchier: adjusted earnings per share rose 82% to $1.55, comfortably ahead of the roughly $1.07 consensus tracked by MarketBeat’s FiscalAI data – a beat of 48 cents a share. The Associated Press, via wtop.com, independently confirmed the $170m net income and $1.39 GAAP figure, and Reuters’ feed on Investing.com likewise flagged shares rising on the back of the adjusted-EPS beat.
Where the Clorox Q1 earnings growth actually came from
Here is the part the “beat” framing tends to skip. Of that 33% net-sales growth, roughly 39 percentage points came from the GOJO acquisition alone, according to Clorox’s own release carried by Stockhouse. Do the arithmetic and that implies the pre-existing business – the bleach, the wipes, the cat litter – actually shrank in the quarter. An acquisition can be a perfectly good reason for a company to grow faster; it is a different thing entirely from organic demand picking up, and investors pricing the stock on the latter assumption are working from the wrong model.
Margins told a similarly mixed story. Gross margin fell 130 basis points (a basis point is one-hundredth of a percentage point) year-on-year to 40.4%, which GuruFocus attributed to rising commodity and logistics costs. That is the kind of input-cost squeeze that has dogged consumer-staples names through this cycle, and it sat alongside the sales growth rather than being offset by it.
Clorox’s own release, carried via PR Newswire, held its full-year guidance in place – net sales growth of 13% to 14% and adjusted EPS of $5.70 to $6.00 for fiscal 2027 – but the company flagged it now expects to land nearer the bottom of that range given the cost pressure. That is a notably more cautious tone than the headline EPS and revenue beats would suggest on their own.
A business still finding its footing
Context helps here. Clorox posted a net loss of $51m as recently as the quarter ended March 2024, before a run of positive quarters that included $193m in net income in the December 2024 quarter and $187m in March 2026, per its own filings. The swing back to profit has been real, but the quarter-to-quarter numbers have also been lumpy enough that a single clean beat doesn’t settle the question of whether the underlying business has turned a corner or is simply benefiting from deal-making timed well against tough comparisons.
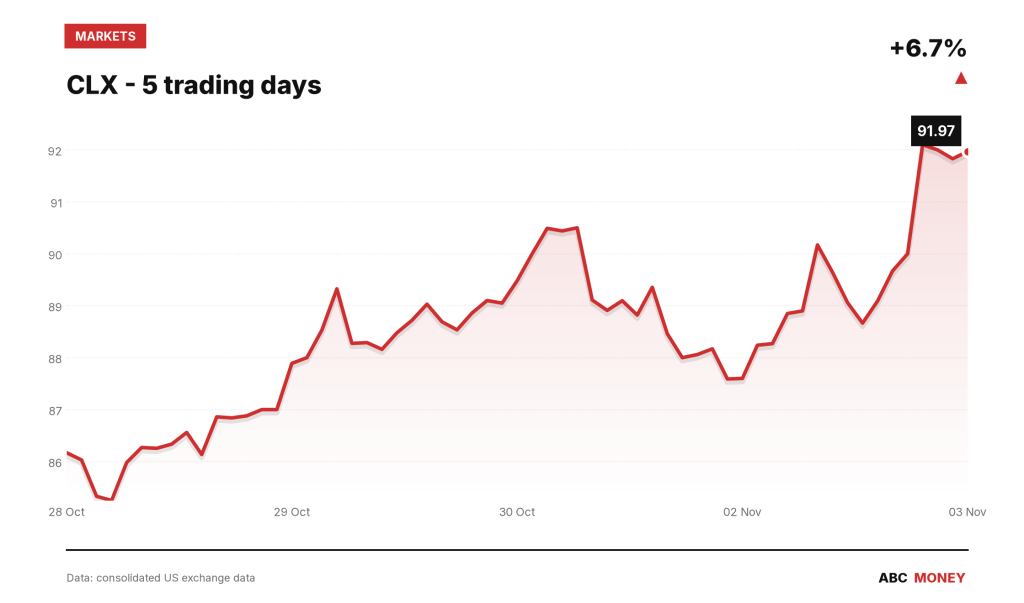
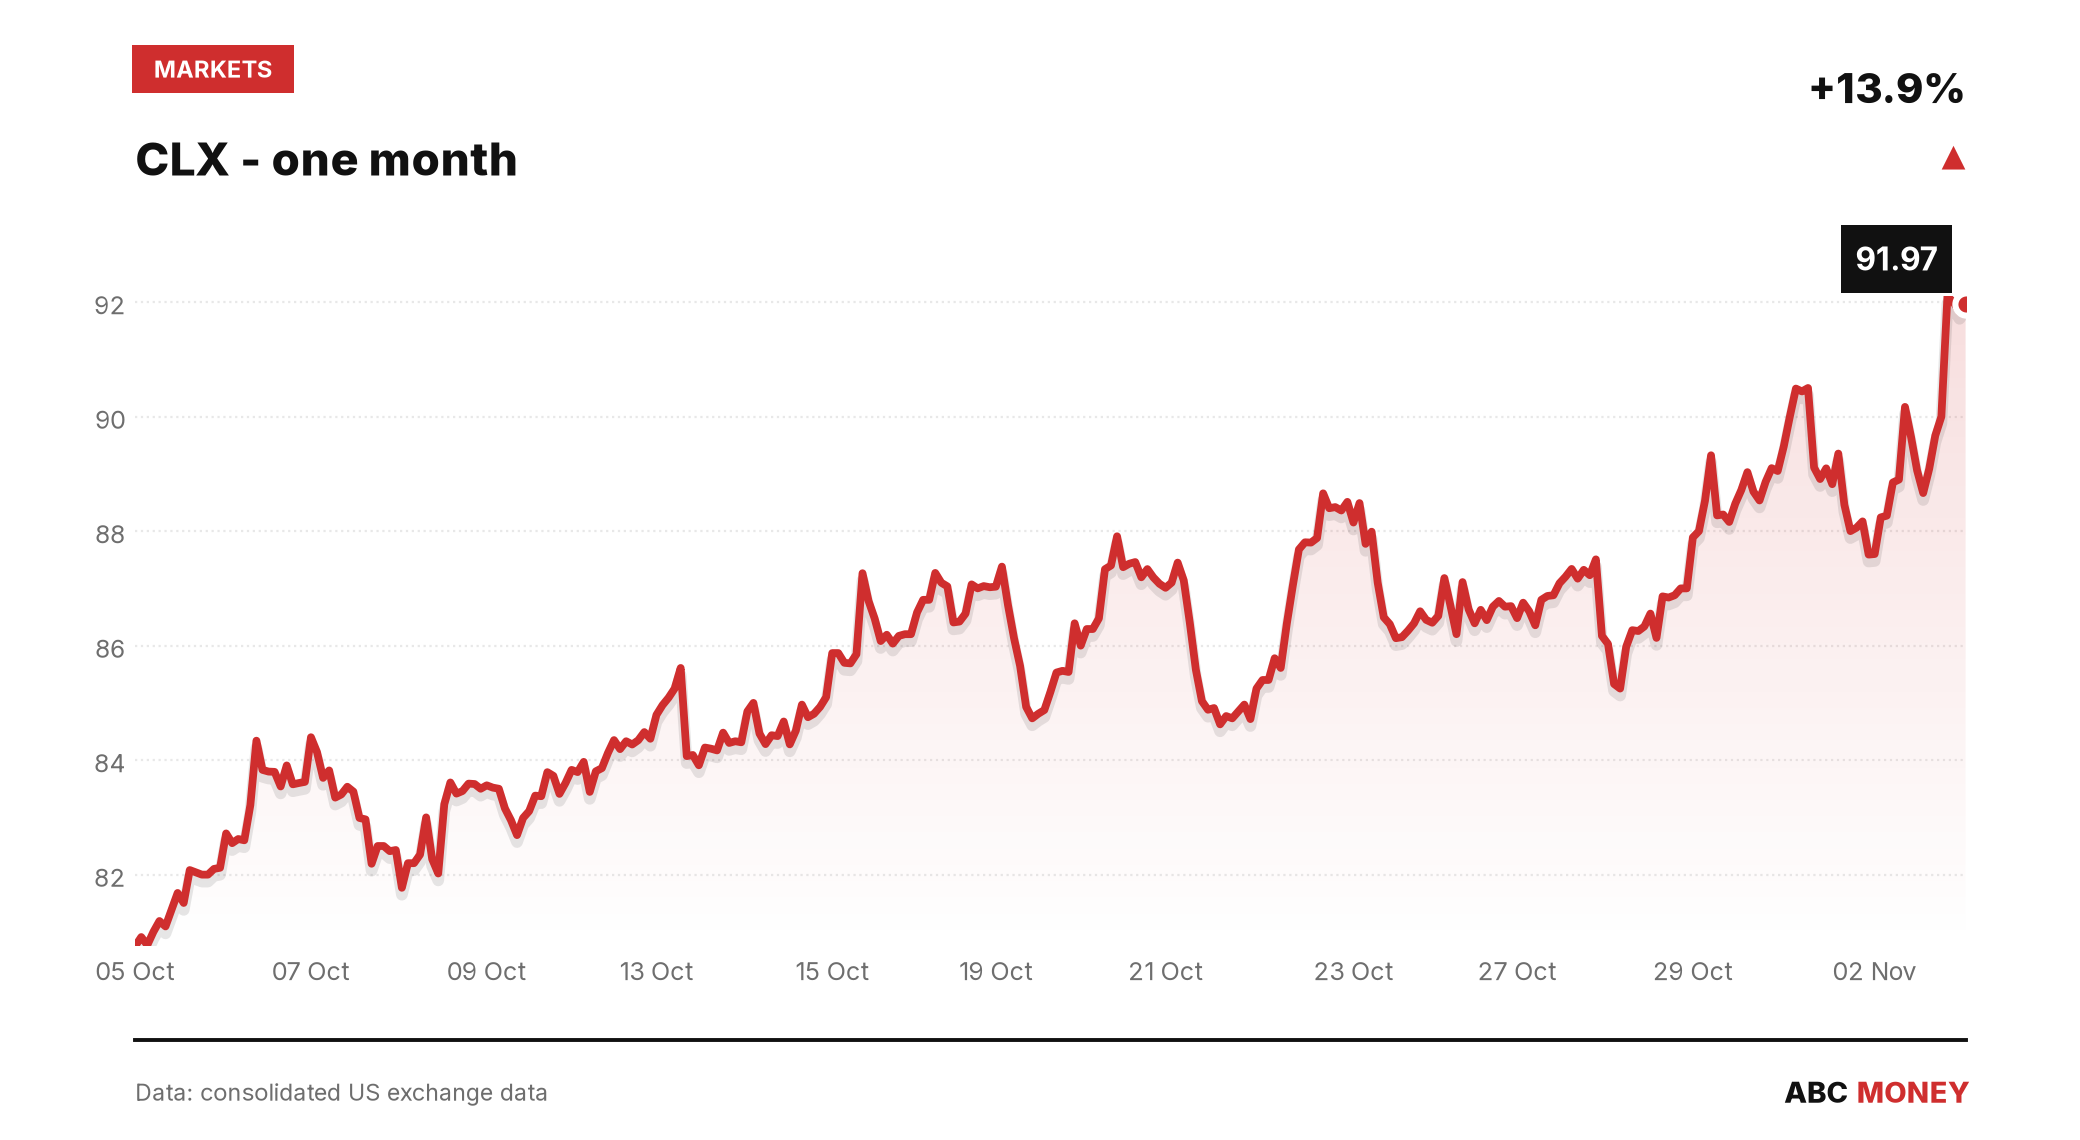
The market’s initial reaction was unambiguous regardless of the nuance: shares rose 3.73% to $91.97, near the top of their 20-day trading range of $83.91 to $92.10, on volume 1.77 times the 20-day average. The report landed against a macro backdrop of a 10-year Treasury yield at 4.94% and unemployment at 4.2% – a rate environment that is moderating but still leaves little room for error in how staples stocks like Clorox get valued on cash flow.
What the next quarter needs to show
The test for Clorox now is whether organic volumes stabilise once GOJO rolls into the base and the acquisition-driven growth rate normalises. Fiscal second-quarter results, due early February based on the company’s recent filing cadence, will be the first print where the comparison period no longer flatters the headline number quite so generously. Until then, the beat is real, but so is the asterisk next to it.
This article is for information only and is not investment advice or a recommendation to buy or sell any asset. Markets move quickly; figures are correct as sourced at the time of writing. Always do your own research before making financial decisions.