Live Nation Q3 earnings: record 61m fans, $10.1bn revenue
Live Nation Q3 earnings top forecasts with $10.1bn revenue and record 61m fans, but the EPS jump masks a far smaller profit gain.
In this article 3 sections
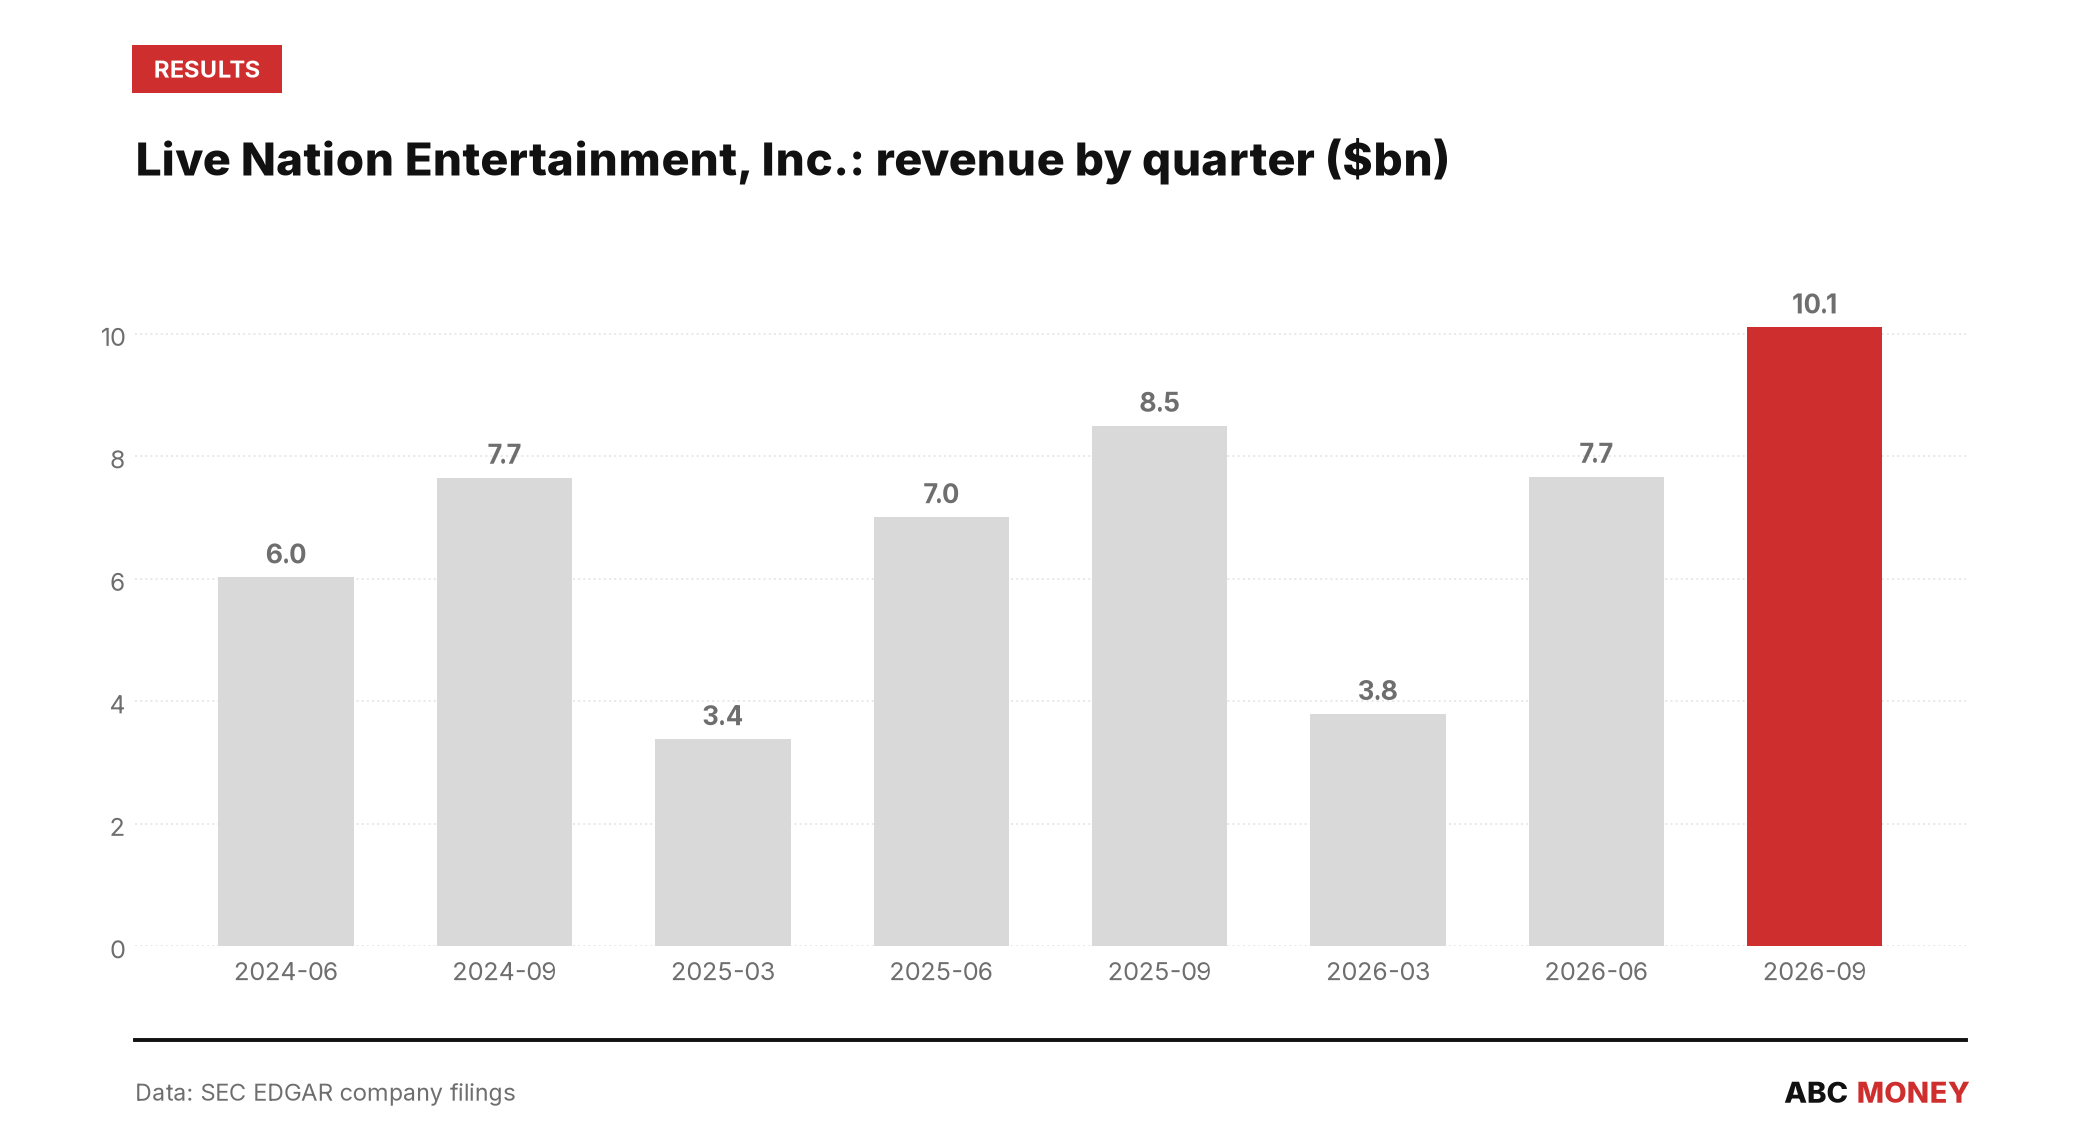
Live Nation Entertainment (NYSE: LYV) delivered its strongest quarter yet, and for once the superlatives in the press release held up against the filings. The concert and ticketing giant’s third-quarter results, published on 5 November 2026, showed revenue of $10.1bn, up 18.9% on the same quarter last year, with net income of $447.8m and diluted earnings per share (EPS – profit divided by the number of shares outstanding, including any that could be created from options or convertible securities) of $1.69.
Both figures beat what Wall Street was pencilling in. The Associated Press reported that revenue topped a consensus of roughly $9.57bn from analysts surveyed by Zacks, while EPS cleared the $1.50 estimate built from seven analyst forecasts. As the company put it in its results announcement, “in a world of endless screens and AI-generated everything, the one thing that can’t be replicated is being there” – and on the evidence of the quarter, fans agree.
Attendance did the heavy lifting
Global fan attendance hit a record 61 million in the quarter, up 19% year-on-year, according to the company’s own results statement. Adjusted operating income (AOI – Live Nation’s preferred profit measure, which strips out items like depreciation and one-off costs) rose 14% to $1.18bn, with double-digit growth across all three segments: Concerts AOI up 17%, Ticketing up 10%, and Sponsorship & Advertising up 12%, per the financial highlights table filed alongside the results. Operating income rose 13% to $892.0m.
The company also disclosed it had sold roughly 170 million tickets through October, up 13% and already ahead of the whole of 2025, and raised its full-year attendance guidance to nearly 180 million fans, according to the exhibit filed with its quarterly report. International markets have now overtaken the US in both concert attendance and sponsorship revenue on a year-to-date basis – a shift that underscores how much of Live Nation’s growth engine now sits outside its home market.
The EPS number flatters the underlying profit story
Here is the wrinkle worth sitting with. Diluted EPS of $1.69 is more than double the $0.73 reported in the same quarter last year – a 131% increase. Net income, the actual pool of profit the company generated, rose only 3.8%, from $431.5m to $447.8m. The gap between those two growth rates is almost entirely down to how much of that profit Live Nation has to hand to minority partners in its various ventures – the noncontrolling interest, or NCI, deduction that sits between consolidated net income and the earnings attributable to ordinary shareholders.
That NCI slice came to $119.0m in the third quarter, a far smaller bite than a year earlier, which mechanically inflates the per-share growth rate even though the business as a whole grew its bottom line far more modestly than the headline EPS figure implies. With roughly 233.1 million weighted average basic shares outstanding, investors reading only the EPS line could reasonably conclude profitability is compounding at a pace the underlying numbers don’t quite support. Revenue and attendance, by contrast, are unambiguous: both grew at rates that dwarf the net income increase, which is arguably the more honest gauge of how the quarter actually went.
A beat that the market shrugged off
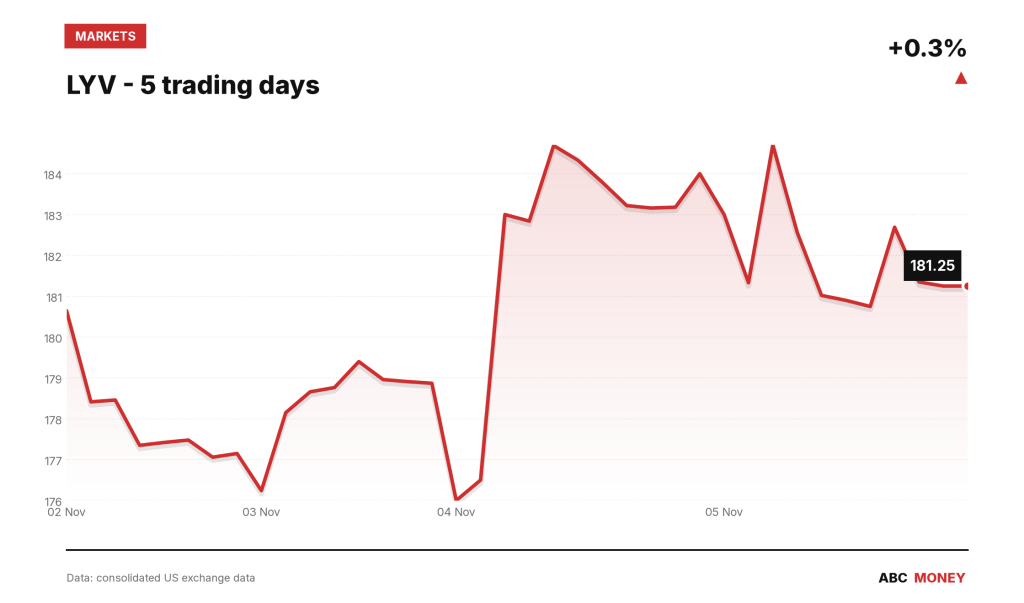
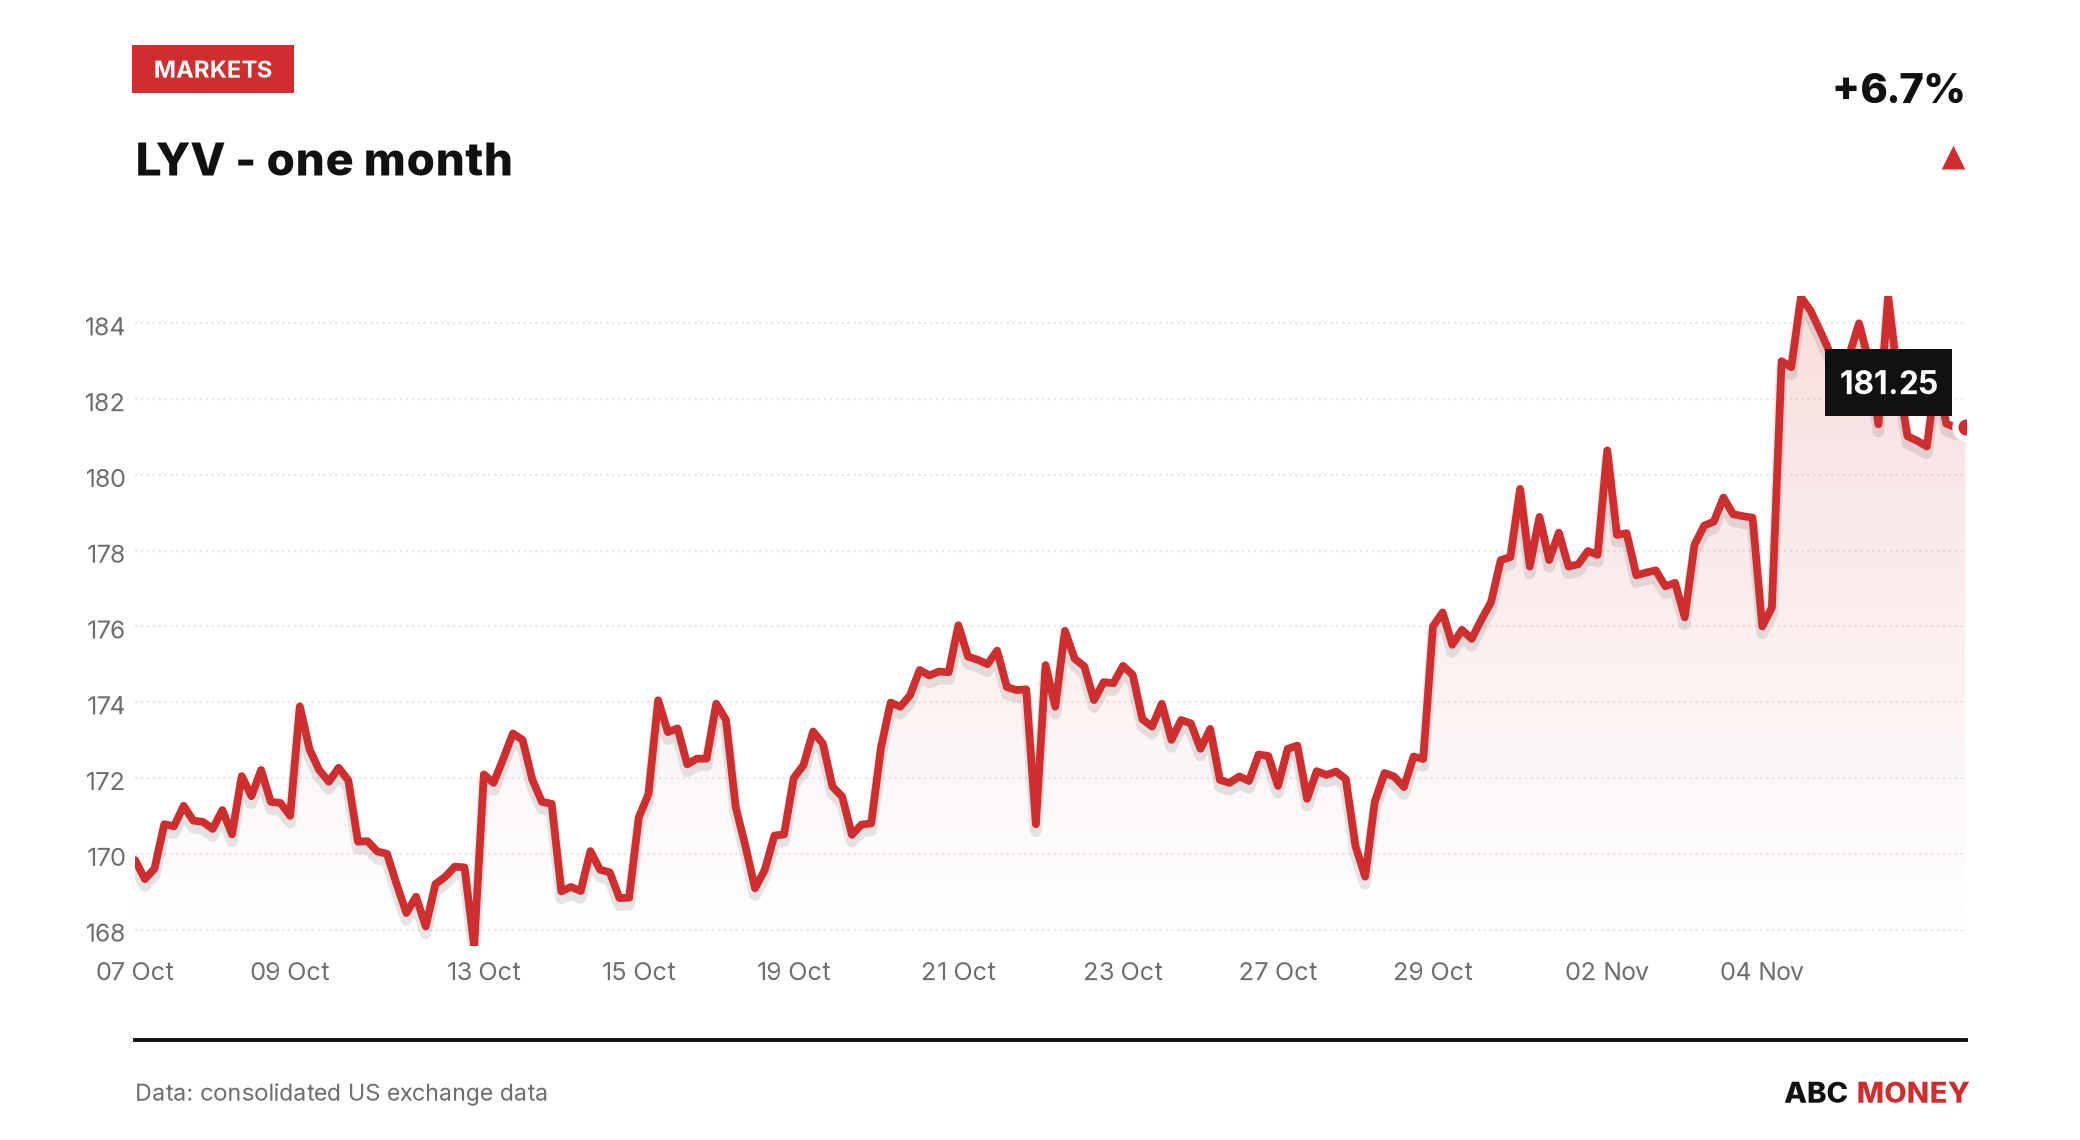
Oddly, none of this translated into an immediate share-price pop. LYV closed at $181.25 as of 22:00 UTC on 5 November, down 0.72% on the day, even as trading volume ran at nearly double its 20-day average. The stock remains up 4.2% over the preceding 20 trading days and within its recent range of $169.09 to $184.71.
There’s little in the positioning data to suggest traders were braced for disappointment. FINRA’s daily short-sale volume figures show the proportion of LYV trading tied to short sales (bets that the shares will fall) ran between roughly 0.56 and 0.77 in the two weeks before results – unremarkable by the stock’s own recent standards, and not the kind of build-up that typically precedes a sharp post-earnings reversal. The modest dip looks more like a case of a loud beat meeting a market that had already priced in most of the good news, rather than any crack in the underlying story.
A routine Form 4 filing on 4 November disclosed share dealings by a reporting individual named Hu Da-Wai, though the filing itself carried no share or dollar figures and isn’t tied to any stated executive role, leaving it as background noise rather than a signal either way. For now, the numbers that matter are the ones in the filing: record attendance, a double-digit AOI beat, and a profit line that grew far more slowly than the per-share figure would have you believe.
This article is for information only and is not investment advice or a recommendation to buy or sell any asset. Markets move quickly; figures are correct as sourced at the time of writing. Always do your own research before making financial decisions.