Charles River Labs beats Q3 estimates, shares fall anyway
Charles River Laboratories earnings beat forecasts with $982.7m revenue and raised guidance, yet CRL shares slid on 4 November 2026.
In this article 3 sections
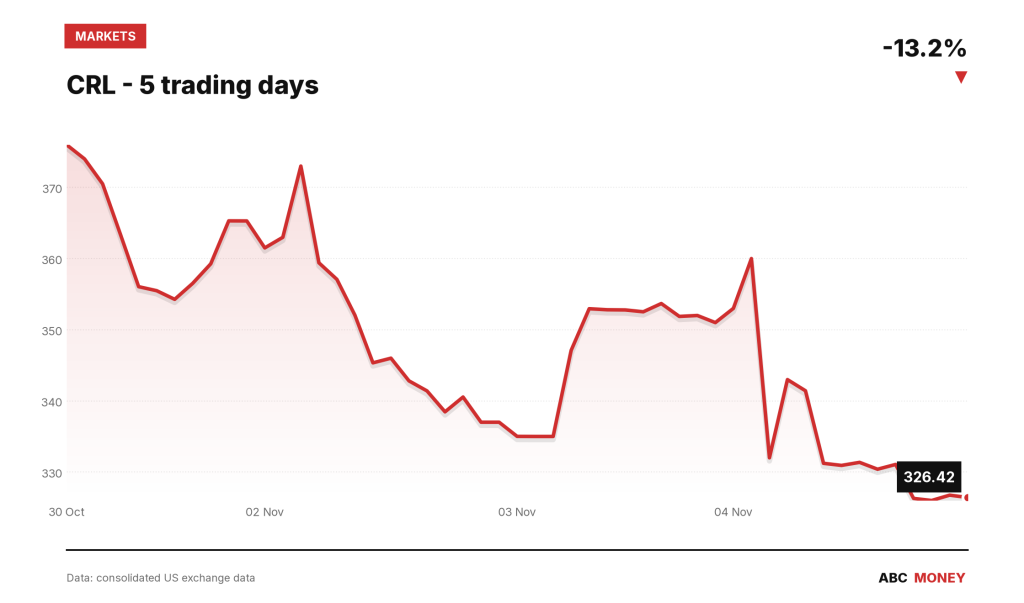
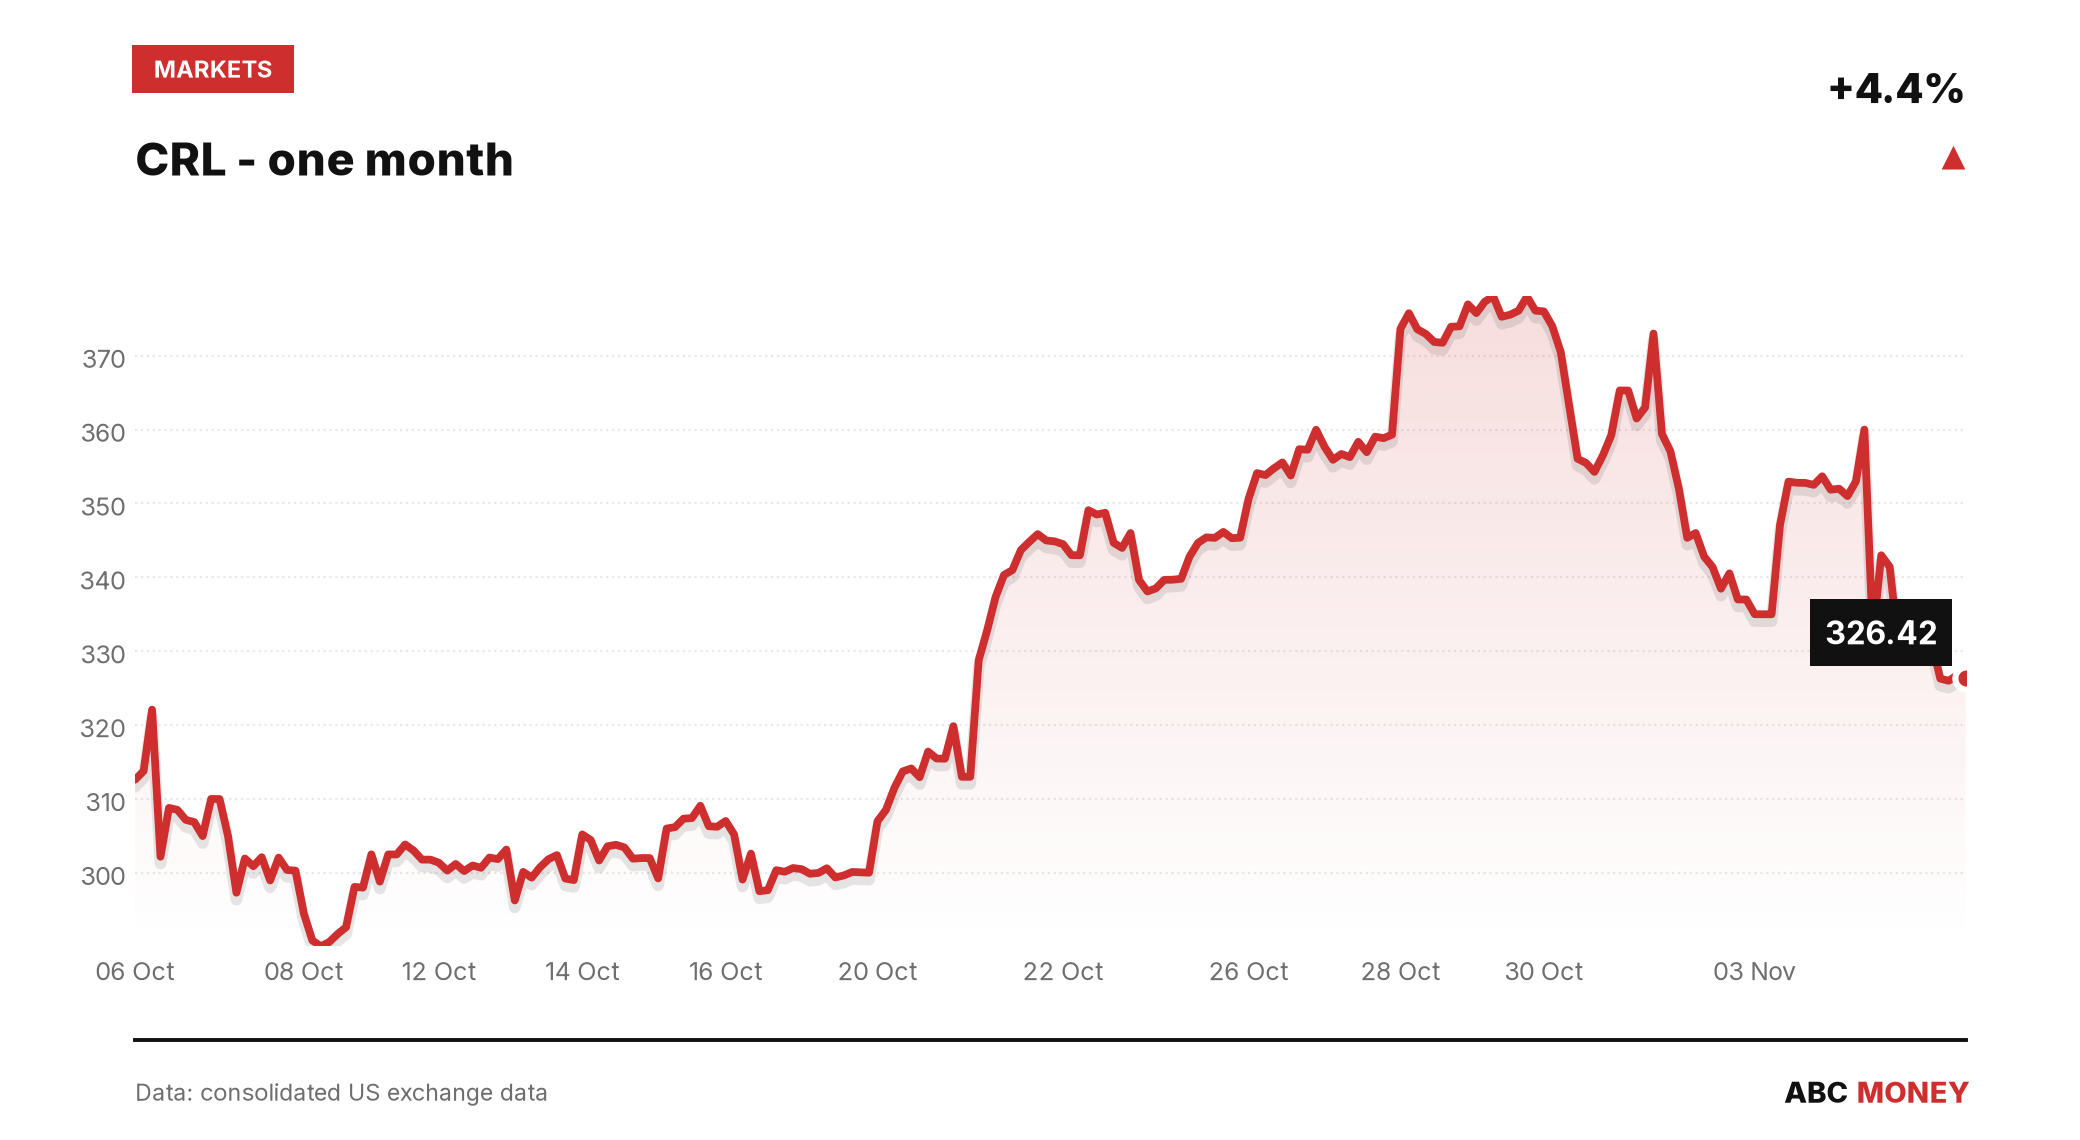
Charles River Laboratories (NYSE: CRL) delivered a Q3 2026 that, on paper, had everything a bull could want: revenue and earnings ahead of Wall Street forecasts, a second straight quarter of organic growth, and raised full-year guidance. The shares fell anyway, closing at $326.42, down 1.36% on the day, according to MarketBeat, with some measures of the move running as steep as 6%.
The preclinical and drug-testing services group, best known for supplying lab animals and contract research to pharmaceutical developers, reported revenue of $982.7 million for the quarter ended 26 September 2026, per its 10-Q filed with the SEC. That topped analyst estimates of roughly $956.8m-$960.2m cited by the Associated Press via WTOP. Organic revenue growth – stripping out the effect of acquisitions, divestitures and currency moves – came in at 4.7%, the company’s second consecutive quarter of organic expansion after a stretch of declines.
The headline EPS number needs a footnote
The eye-catching figure is GAAP diluted earnings per share of $6.86, against $1.10 a year earlier – a jump that looks almost too good to be true, and in a sense it is. Net income attributable to shareholders came to $333.1 million, more than six times the $54.4 million booked in the same quarter of 2025. But the company itself flags that the swing is overwhelmingly down to one-off items: a gain on the divestiture of its CDMO (contract development and manufacturing) business, a gain on the sale of its Wilmington site, and a non-income tax benefit, rather than any step-change in underlying operations.
That is why both the company and analysts lean on non-GAAP EPS of $3.09 – up 27.2% year-on-year – as the cleaner read on performance, and that figure also beat the Zacks consensus of $2.98 from seven analysts polled ahead of the release.
A volatile year up close
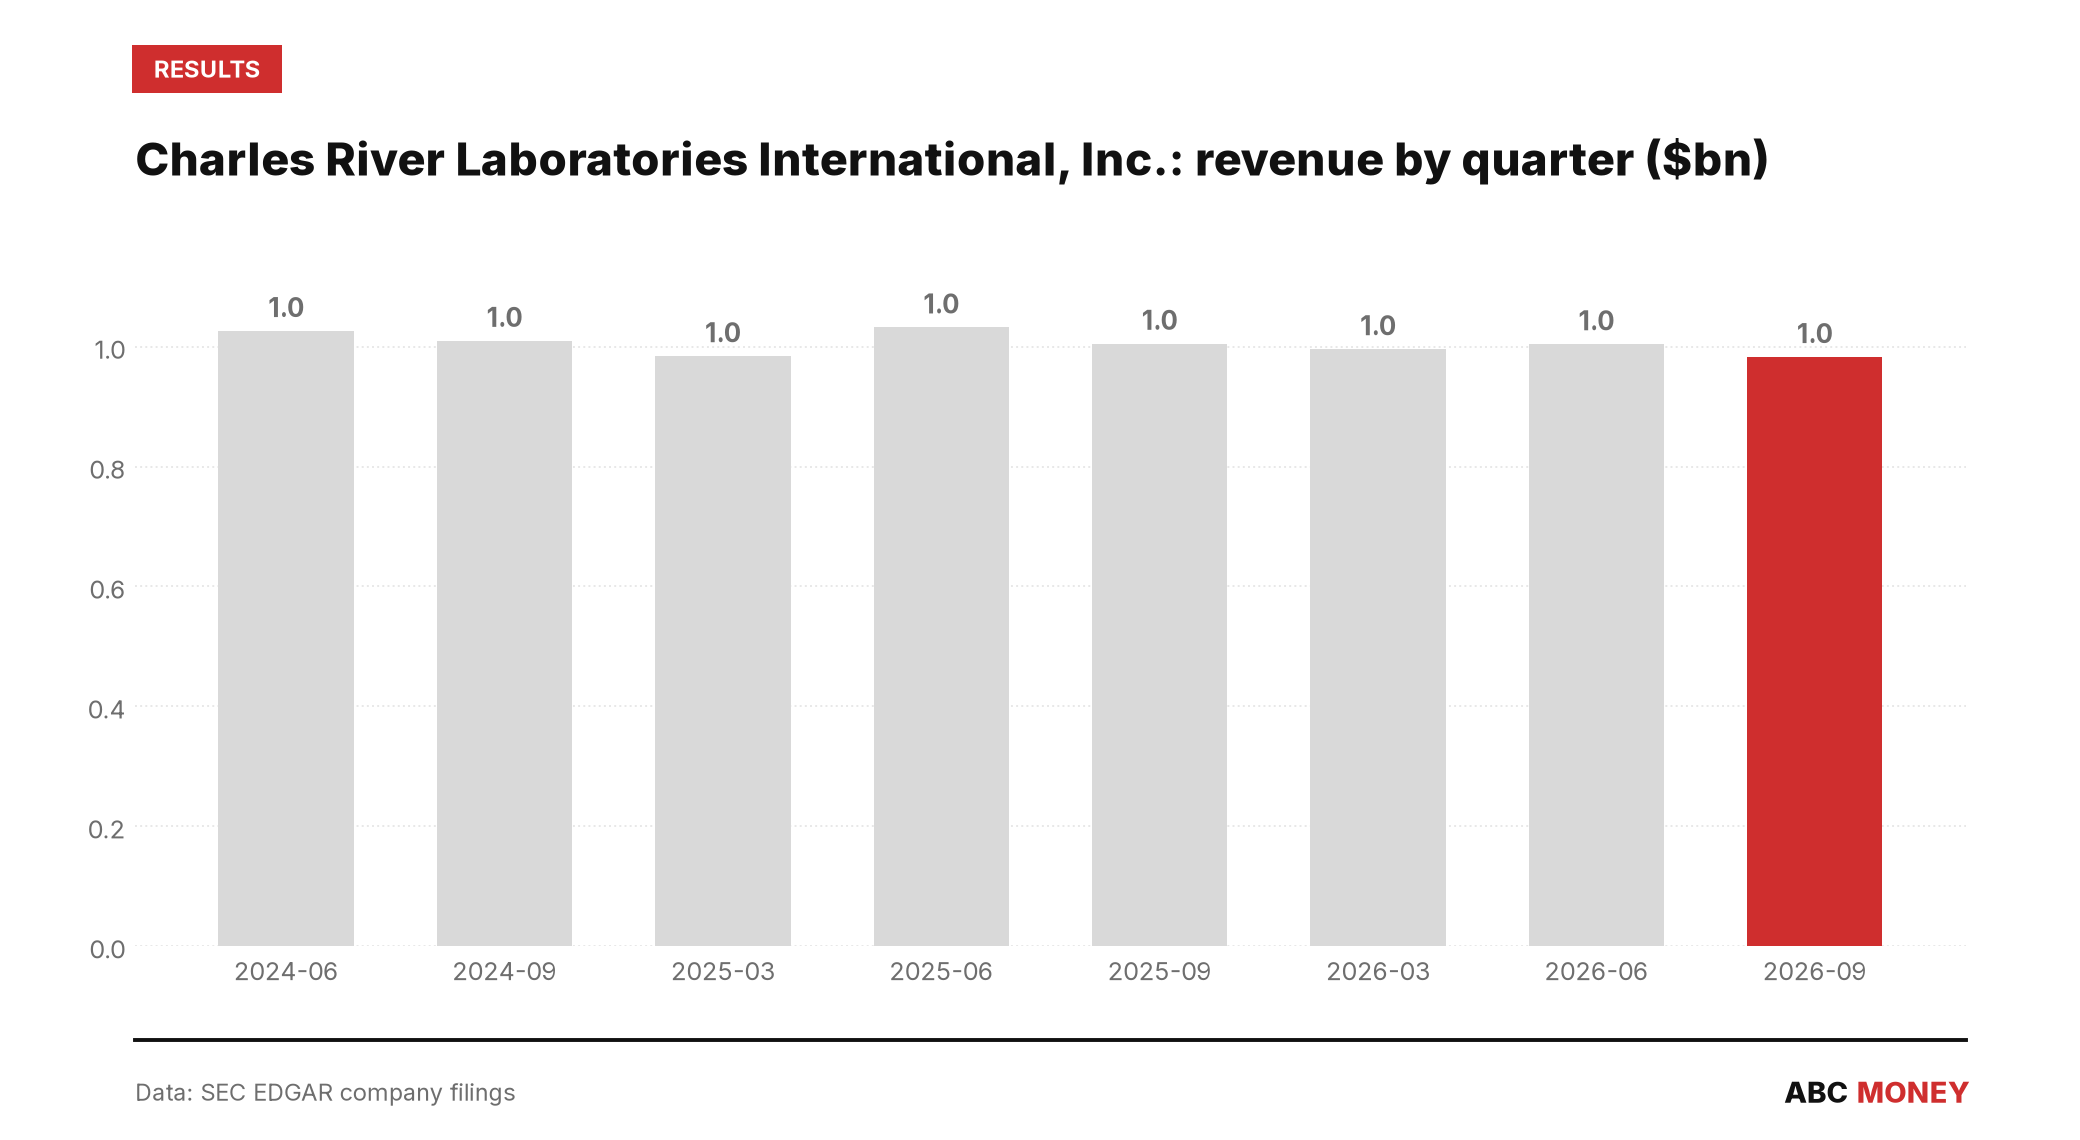
Zoom out to the last two quarters and the scale of the swing looks even starker. Charles River posted a GAAP net loss of $14.8 million in the first quarter of 2026 and a smaller loss of $1.5 million in the second, according to its first-quarter 10-Q and subsequent second-quarter filing. Revenue in those quarters ran close to $1 billion each time – $995.8 million and $1.004 billion respectively – so the losses were not a function of a shrinking top line but of the costs and charges tied to the divestitures now working their way through the books. Seen against that backdrop, Q3’s net income print of $333.1 million is less a sign of a business suddenly firing on all cylinders than the one-off benefits finally landing in a single quarter.
Revenue itself has been remarkably stable through the cycle: $1.026 billion in Q2 2024, $1.010 billion in Q3 2024, dipping to $984.2 million in Q1 2025 before recovering to the low-$1 billion range through 2025 and into 2026. The segment-level declines that show up in the latest quarter – across the Discovery and Safety Assessment (DSA), Manufacturing and Research Models and Services (RMS) divisions – are, per the company’s own filings, attributable to the European Discovery Services site sales, the CDMO exit and the Cell Solutions divestiture, rather than weakening demand in the businesses that remain.
Guidance raised, bookings firmer
Management used the release to lift full-year 2026 guidance, pointing to organic growth above 1.5% and non-GAAP EPS now expected in a $11.35-$11.55 range, a $0.15 increase at the midpoint, according to the company’s earnings call transcript carried by the Motley Fool. The DSA segment, which covers safety testing for drug candidates, posted net bookings of $652 million in the quarter, up 32% year-on-year, with a book-to-bill ratio of 1.09x – a sign that new orders are outpacing revenue recognised in the period, often read as a forward indicator for a services business like this one.
Positioning data add a wrinkle to the sell-off. The proportion of daily trading volume attributable to short sales – bets that the shares will fall – had climbed as high as 0.766 on 22 October, per FINRA’s daily short-sale data, before easing back to 0.327 on the day results landed. That pattern suggests the stock was not primarily the victim of a short squeeze unwinding; if anything, bearish positioning had already cooled into the print, leaving the post-earnings decline to be explained more by investors digesting the gap between the headline GAAP profit and the more modest underlying improvement.
The stock remains up 8.09% over the preceding 20 trading days even after the latest move, having ranged between $297.51 and $378.03 in that window, consolidated exchange data show. Alongside the numbers, Charles River also used the update to unveil what it calls a “Pathway to Purpose” strategic vision and a platform partnership with Autolomous, details that will likely feature more prominently once the company’s next quarterly filing clarifies how much of the current cost base is now behind it.
This article is for information only and is not investment advice or a recommendation to buy or sell any asset. Markets move quickly; figures are correct as sourced at the time of writing. Always do your own research before making financial decisions.