Mosaic third quarter results show $72m loss despite revenue beat
Mosaic third quarter results reveal a $72.1m net loss and a deeper-than-expected adjusted loss, even as revenue topped forecasts at $3.1bn.
In this article 3 sections
Mosaic’s third quarter results, released on 3 November 2026, showed a company selling more fertiliser than analysts expected but making considerably less money doing it. The Mosaic Company (NYSE: MOS) swung to a net loss of $72.1m, or $0.23 a share, for the quarter ended 30 September, against consensus estimates that had pencilled in a loss of roughly three cents a share, according to the Associated Press, which cited a Zacks-surveyed panel of five analysts. The figures were furnished to US regulators via an 8-K filing on the same day.
Revenue told a different story. At roughly $3.1bn, Mosaic’s top line came in ahead of the approximately $3.05bn analysts had modelled, a beat that would ordinarily cushion a results day. It didn’t. The adjusted loss per share – the figure stripped of one-off items that investors tend to weight most heavily – came in at $0.19, well below a consensus clustered near breakeven to a three-cent loss, as Newsquawk noted in its summary of the print.
Mosaic third quarter results: a margin story, not a demand one
The gap between a revenue beat and an earnings miss is the clearest signal in this set of numbers: Mosaic is selling fertiliser just fine, but what it costs to produce and ship phosphate and potash is eating the difference. GuruFocus put the operating loss at $97m and adjusted EBITDA – earnings before interest, tax, depreciation and amortisation, a rough proxy for underlying cash profitability – at $324m, a figure that leaves little room for the fixed costs of running phosphate rock mines and ammonia plants.
Context from Mosaic’s own filing history sharpens the point. A year earlier, in the third quarter of 2025, the company posted net income of $411.4m, or $1.29 a share diluted, a near six-fold swing from profit to loss in twelve months. The prior quarter, Q2 2026, brought a net loss of $272.8m, or $0.86 a share. Measured purely in dollars, the latest loss is actually the smallest of Mosaic’s last three quarters – Q1 2026 lost $257.6m and Q2 2026 lost $272.8m – but it missed Wall Street’s far more optimistic expectations by a wider margin, which is what moved the share price.
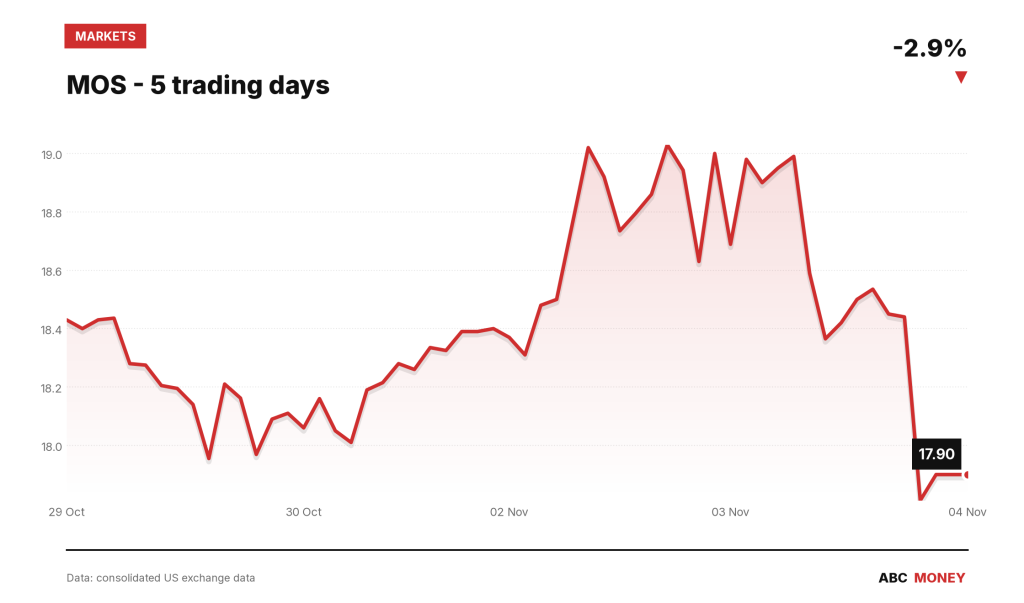
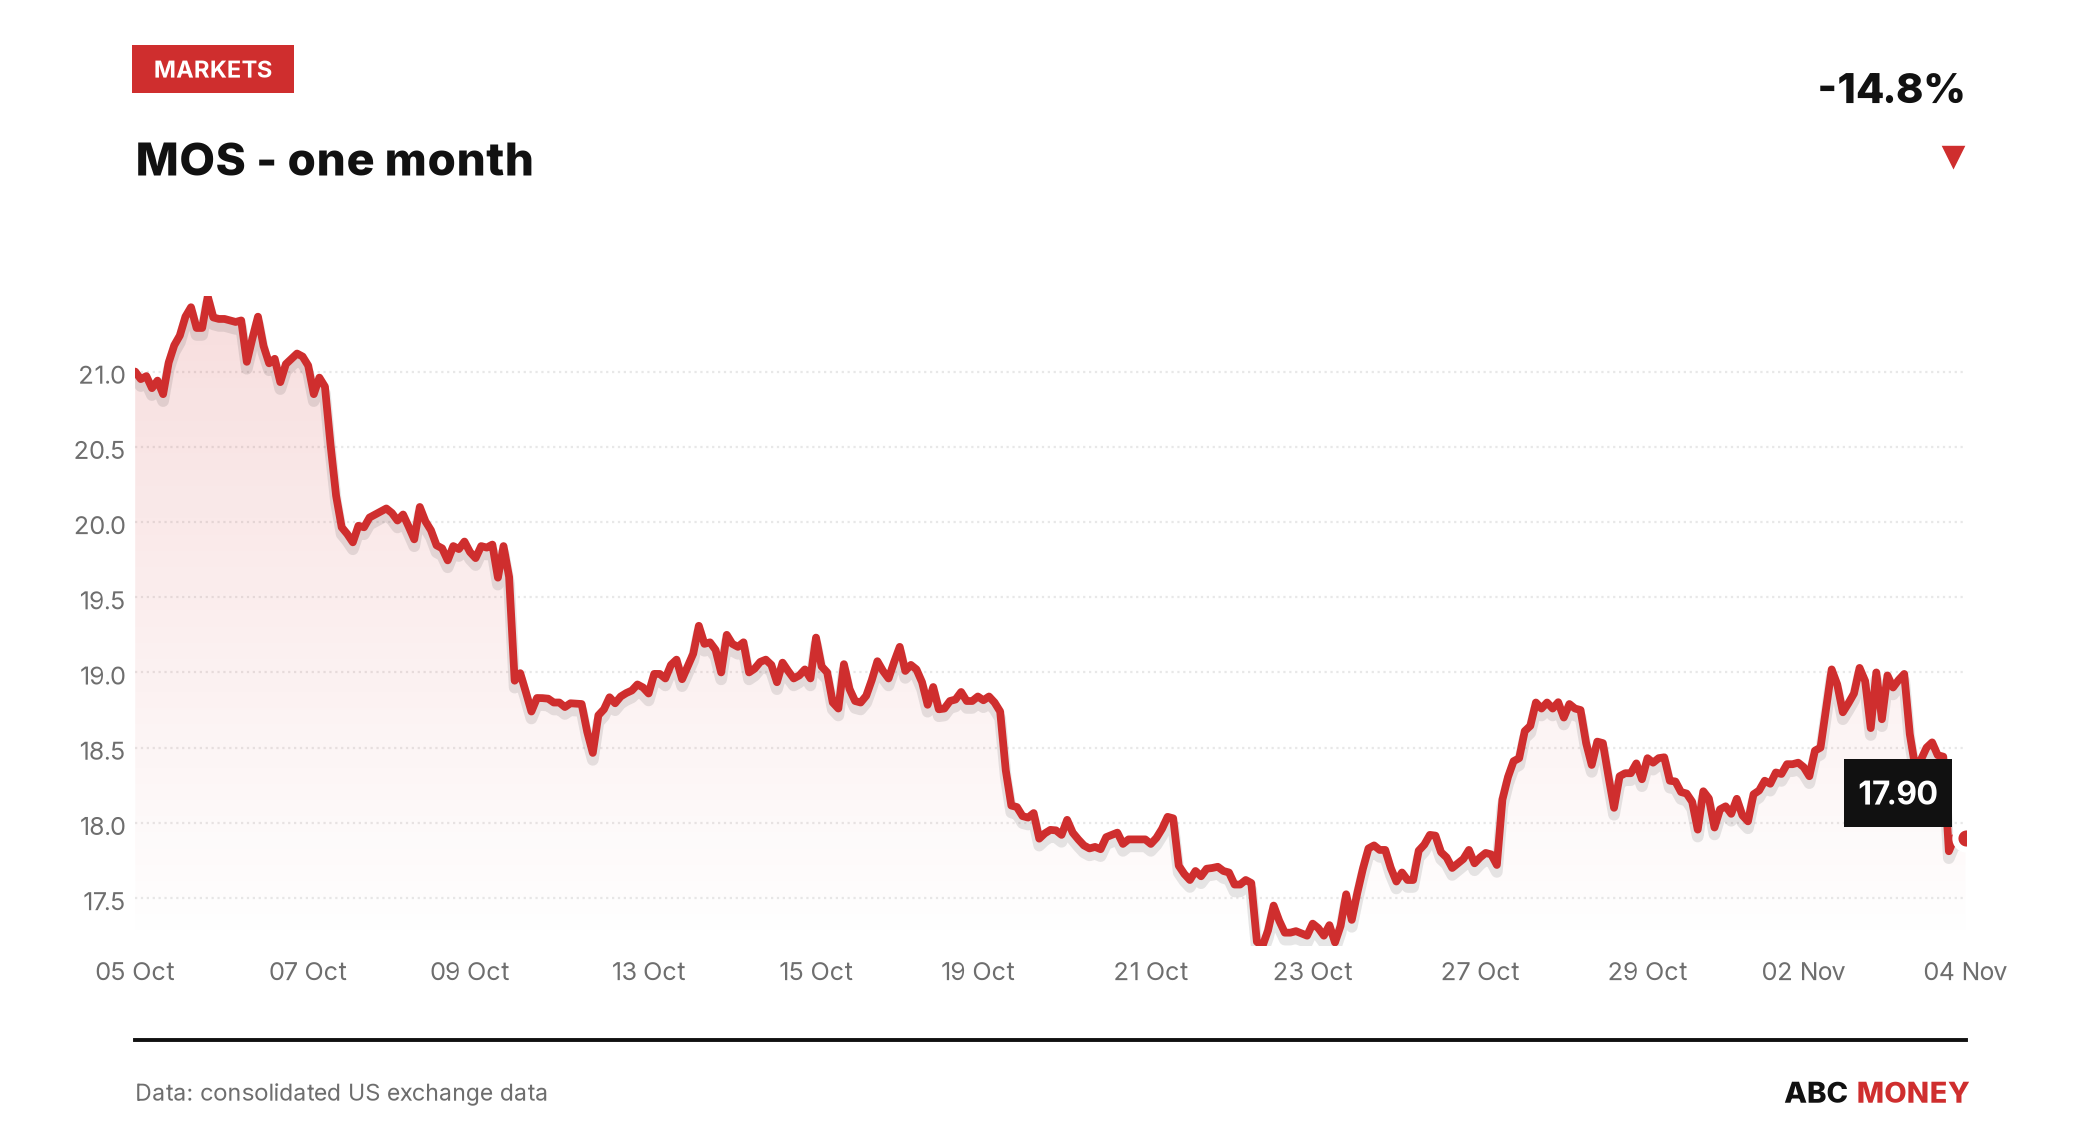
That reaction was immediate. Investing.com reported shares falling as the loss topped estimates, consistent with the stock closing at $17.90, down 2.82% on the day and 6.72% over the preceding 20 trading sessions, with volume running at 1.23 times its 20-day average – the kind of elevated turnover that typically accompanies a result investors weren’t braced for.
Positioning was already turning bearish
The move didn’t come from nowhere. FINRA’s daily short-sale volume data – the share of a stock’s trading that comes from investors betting on a price fall – showed the ratio for Mosaic climbing from 0.438 on 21 October to 0.578 on 3 November, the day of the filing itself, according to FINRA’s short-sale data. That steady build suggests some traders had already concluded the quarter would disappoint before the numbers landed.
Separately, an insider at Mosaic, Karen A. Swager, filed a Form 4 with the SEC on the same day as the earnings release, though the filing did not specify share counts or transaction value, leaving no way to read direction or size into the timing.
What the trend line says
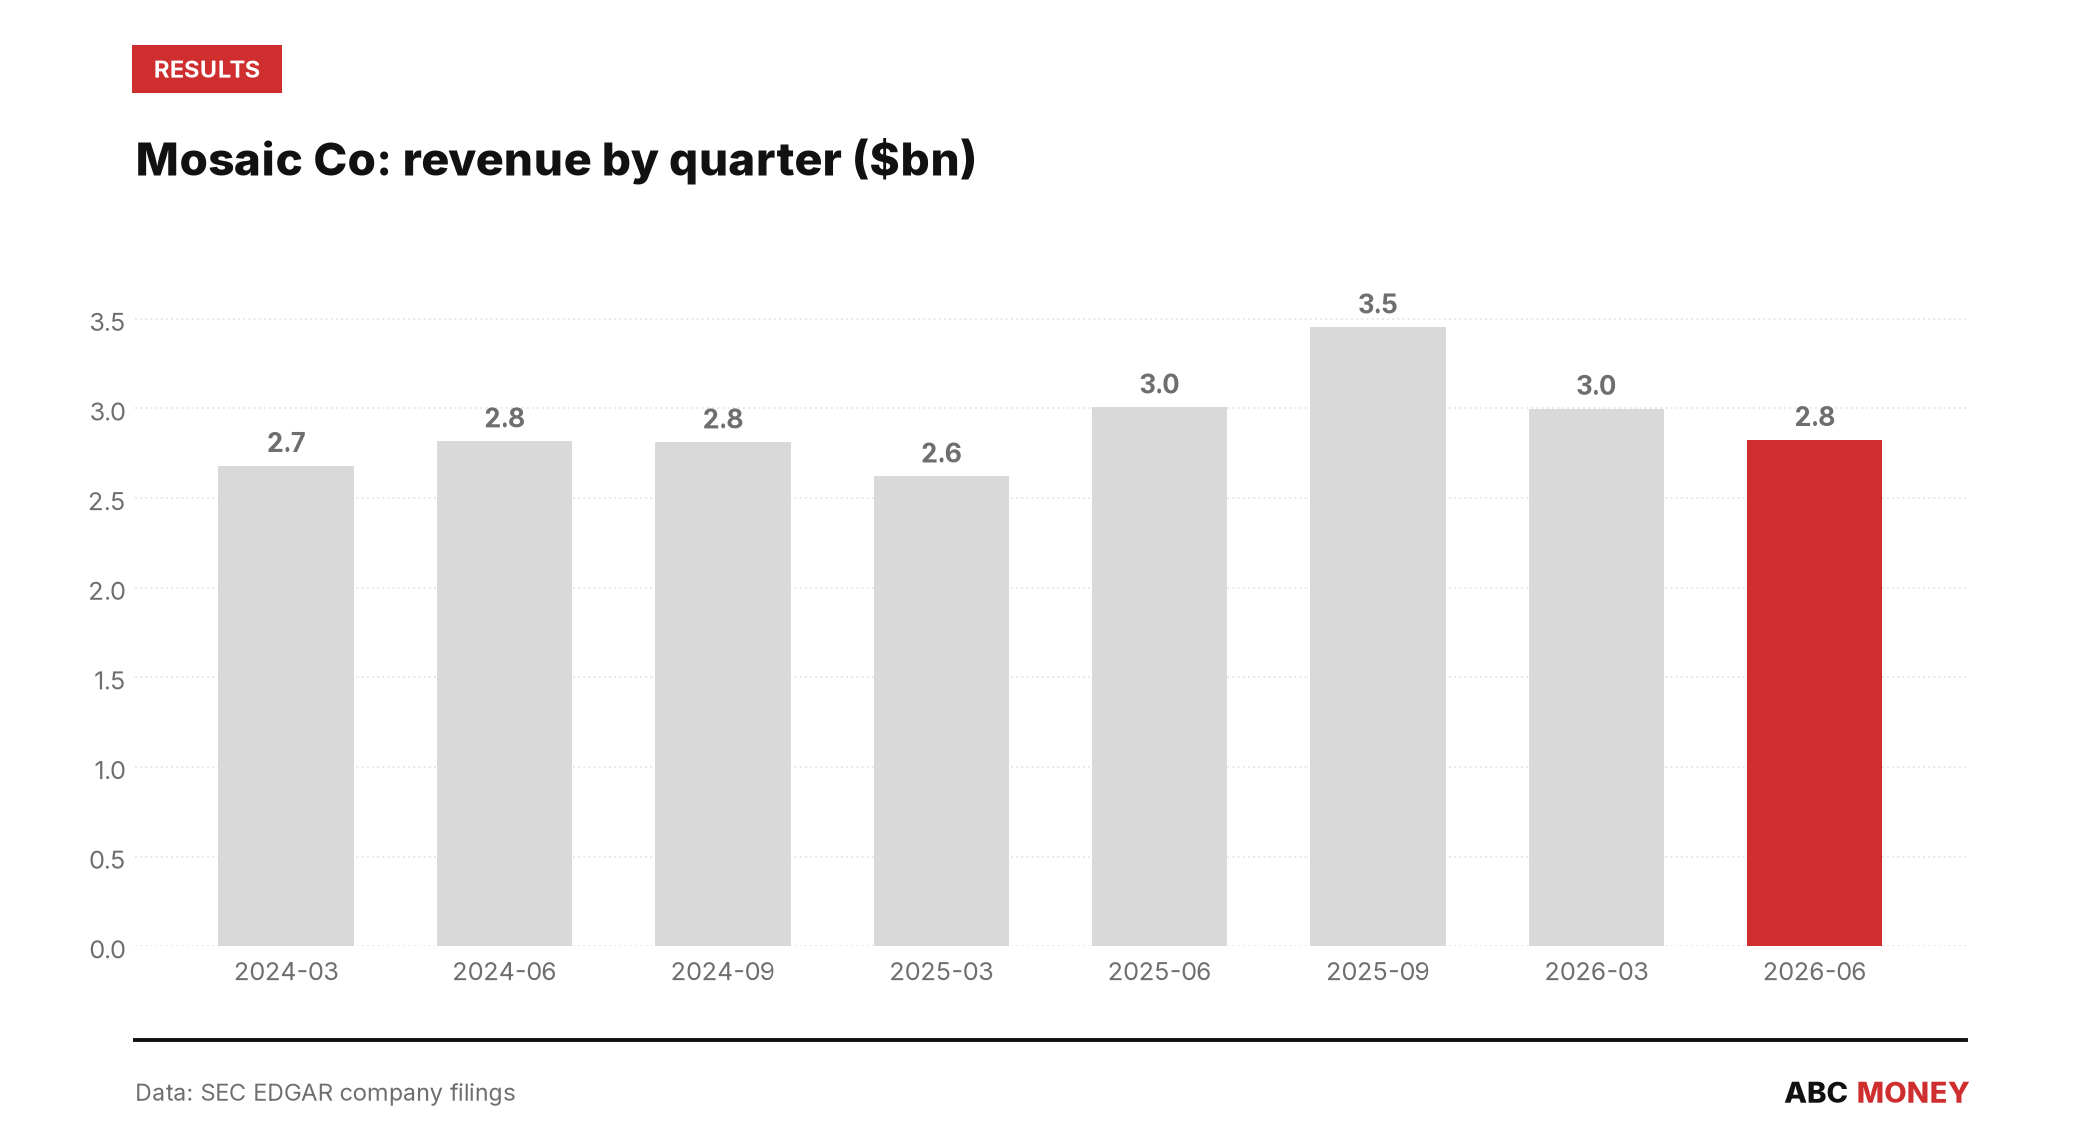
Three consecutive loss-making quarters is now the live pattern at Mosaic, a reversal from a 2025 in which every quarter from Q1 onward was profitable – $238.1m, then $410.7m, then $411.4m. The deterioration lines up with a period of broader macro caution: the 10-year US Treasury yield sat at 4.91% on 2 November, against a two-year yield of 4.59%, leaving the 10-year/2-year spread – a closely watched gauge of how markets price near-term versus long-term risk – at a still-thin 0.34 percentage points, according to Federal Reserve data. Capital-intensive miners like Mosaic, which carry heavy fixed costs and long investment cycles, tend to be judged harshly by markets when financing costs stay elevated and demand visibility narrows.
Whether the fourth quarter brings relief will hinge on potash and phosphate pricing trends and on whether the cost pressures visible in this quarter’s operating loss prove temporary or structural – detail that should emerge when Mosaic reports again and files its next 10-Q with the SEC.
This article is for information only and is not investment advice or a recommendation to buy or sell any asset. Markets move quickly; figures are correct as sourced at the time of writing. Always do your own research before making financial decisions.