Aehr Test Systems Revenue Hits Record $33m, Guidance Triples
Aehr Test Systems revenue hit a record $33m in Q1 FY2027, prompting a raised $150m outlook that would triple fiscal 2026's total.
In this article 3 sections
Aehr Test Systems revenue climbed to a record $33.0 million in the first quarter of fiscal 2027, roughly triple the $11.0 million the burn-in test equipment maker posted in the same quarter a year earlier and up 75% from the $18.8 million it booked in the final quarter of fiscal 2026, according to results released on 2 November 2026. The company also raised its full-year outlook to $150 million, which it said would triple fiscal 2026 revenue outright.
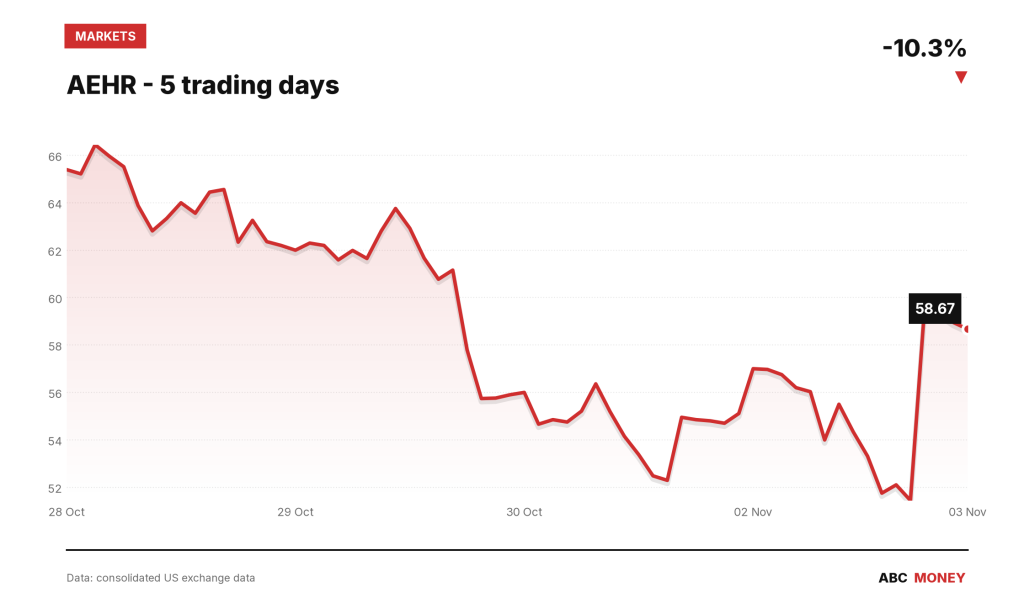
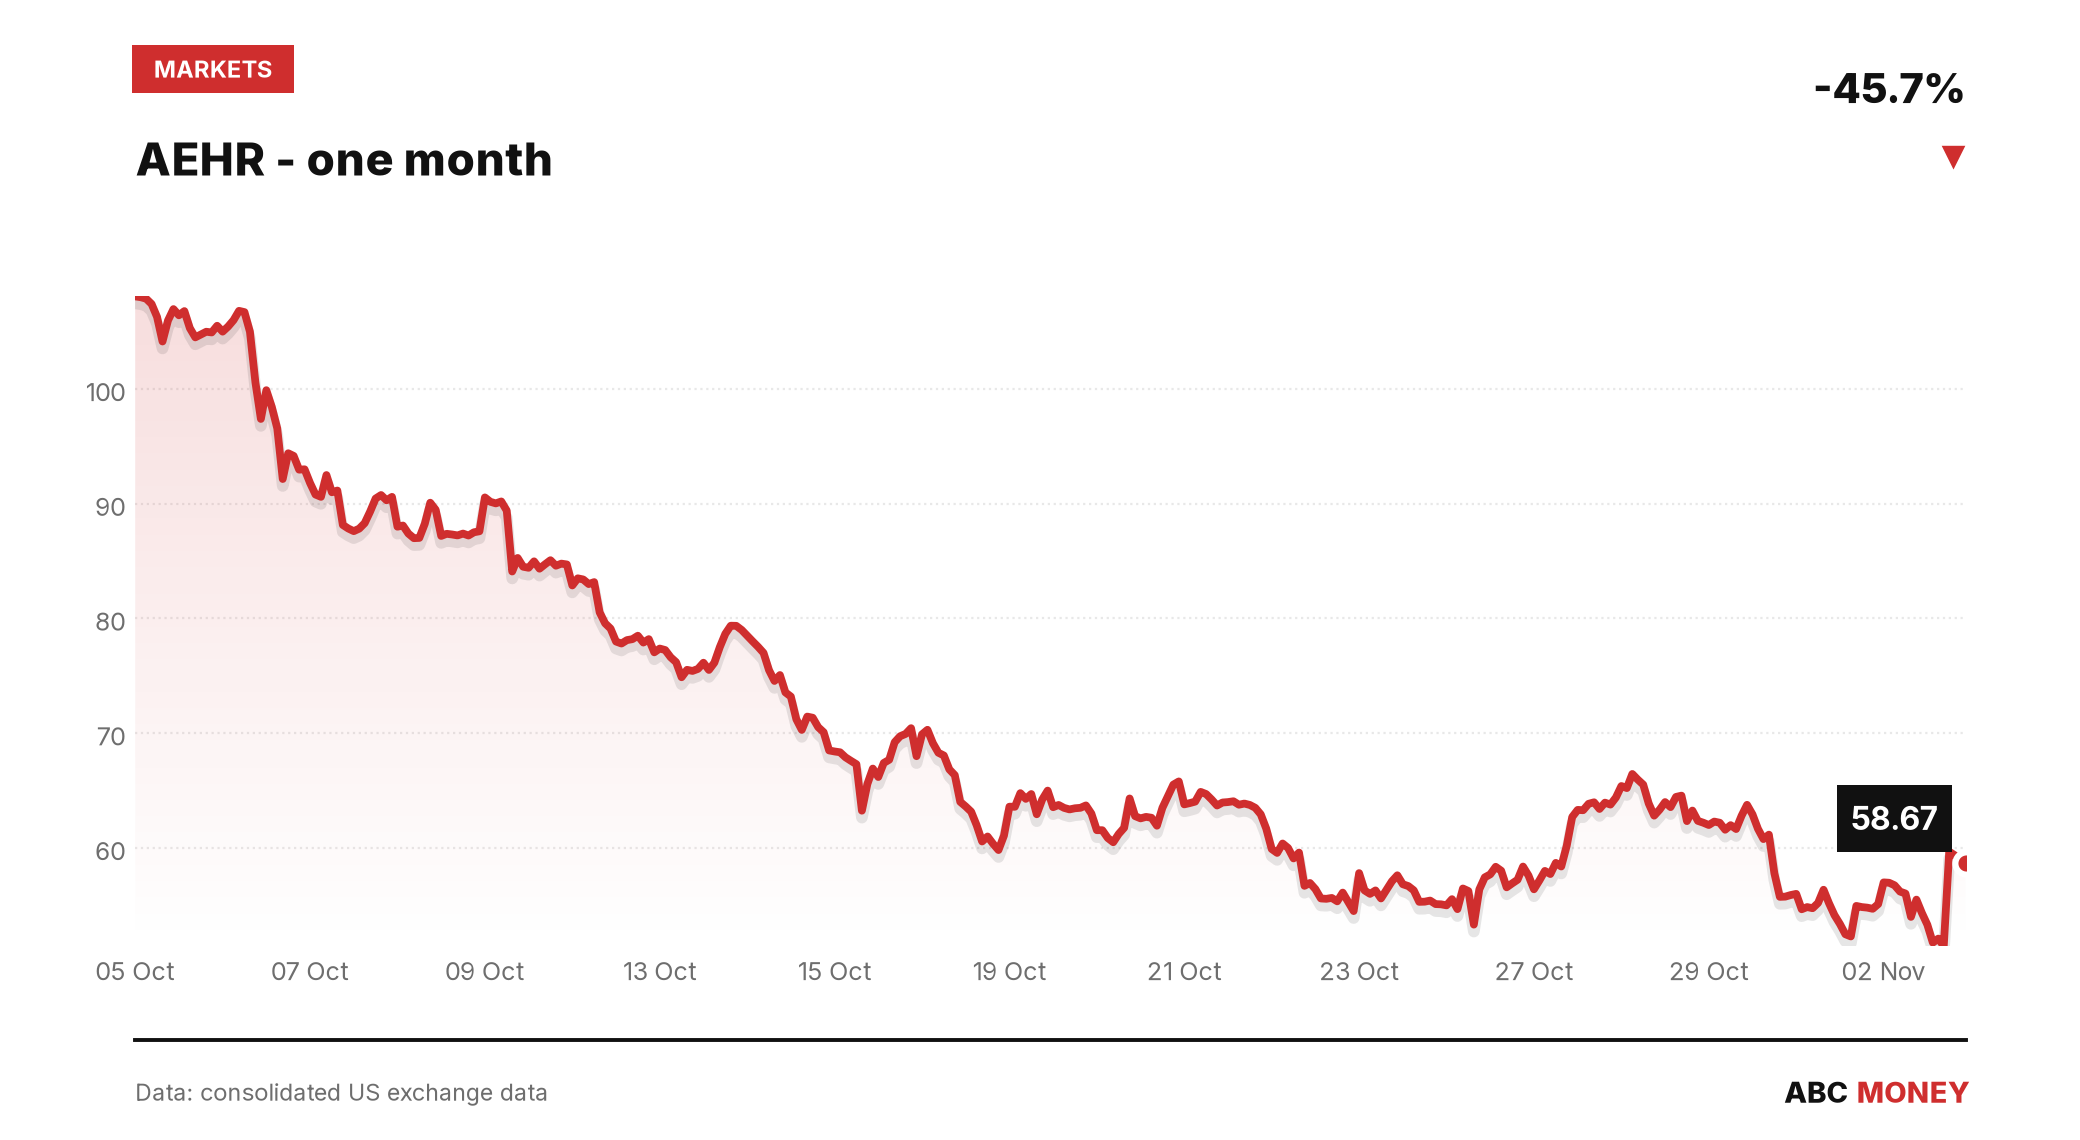
Shares of Aehr (AEHR) rose 10.06% over the following 24 hours, as Benzinga reported, though that bounce only partly repairs a rough patch: the stock had fallen 24.18% over the prior 20 trading days, from a high of $79.37 to a low of $51.44, before closing at $58.67. Trading volume ran at more than double its 20-day average, a sign the move was driven by real money repositioning rather than thin-market noise.
The tripling claim checks out
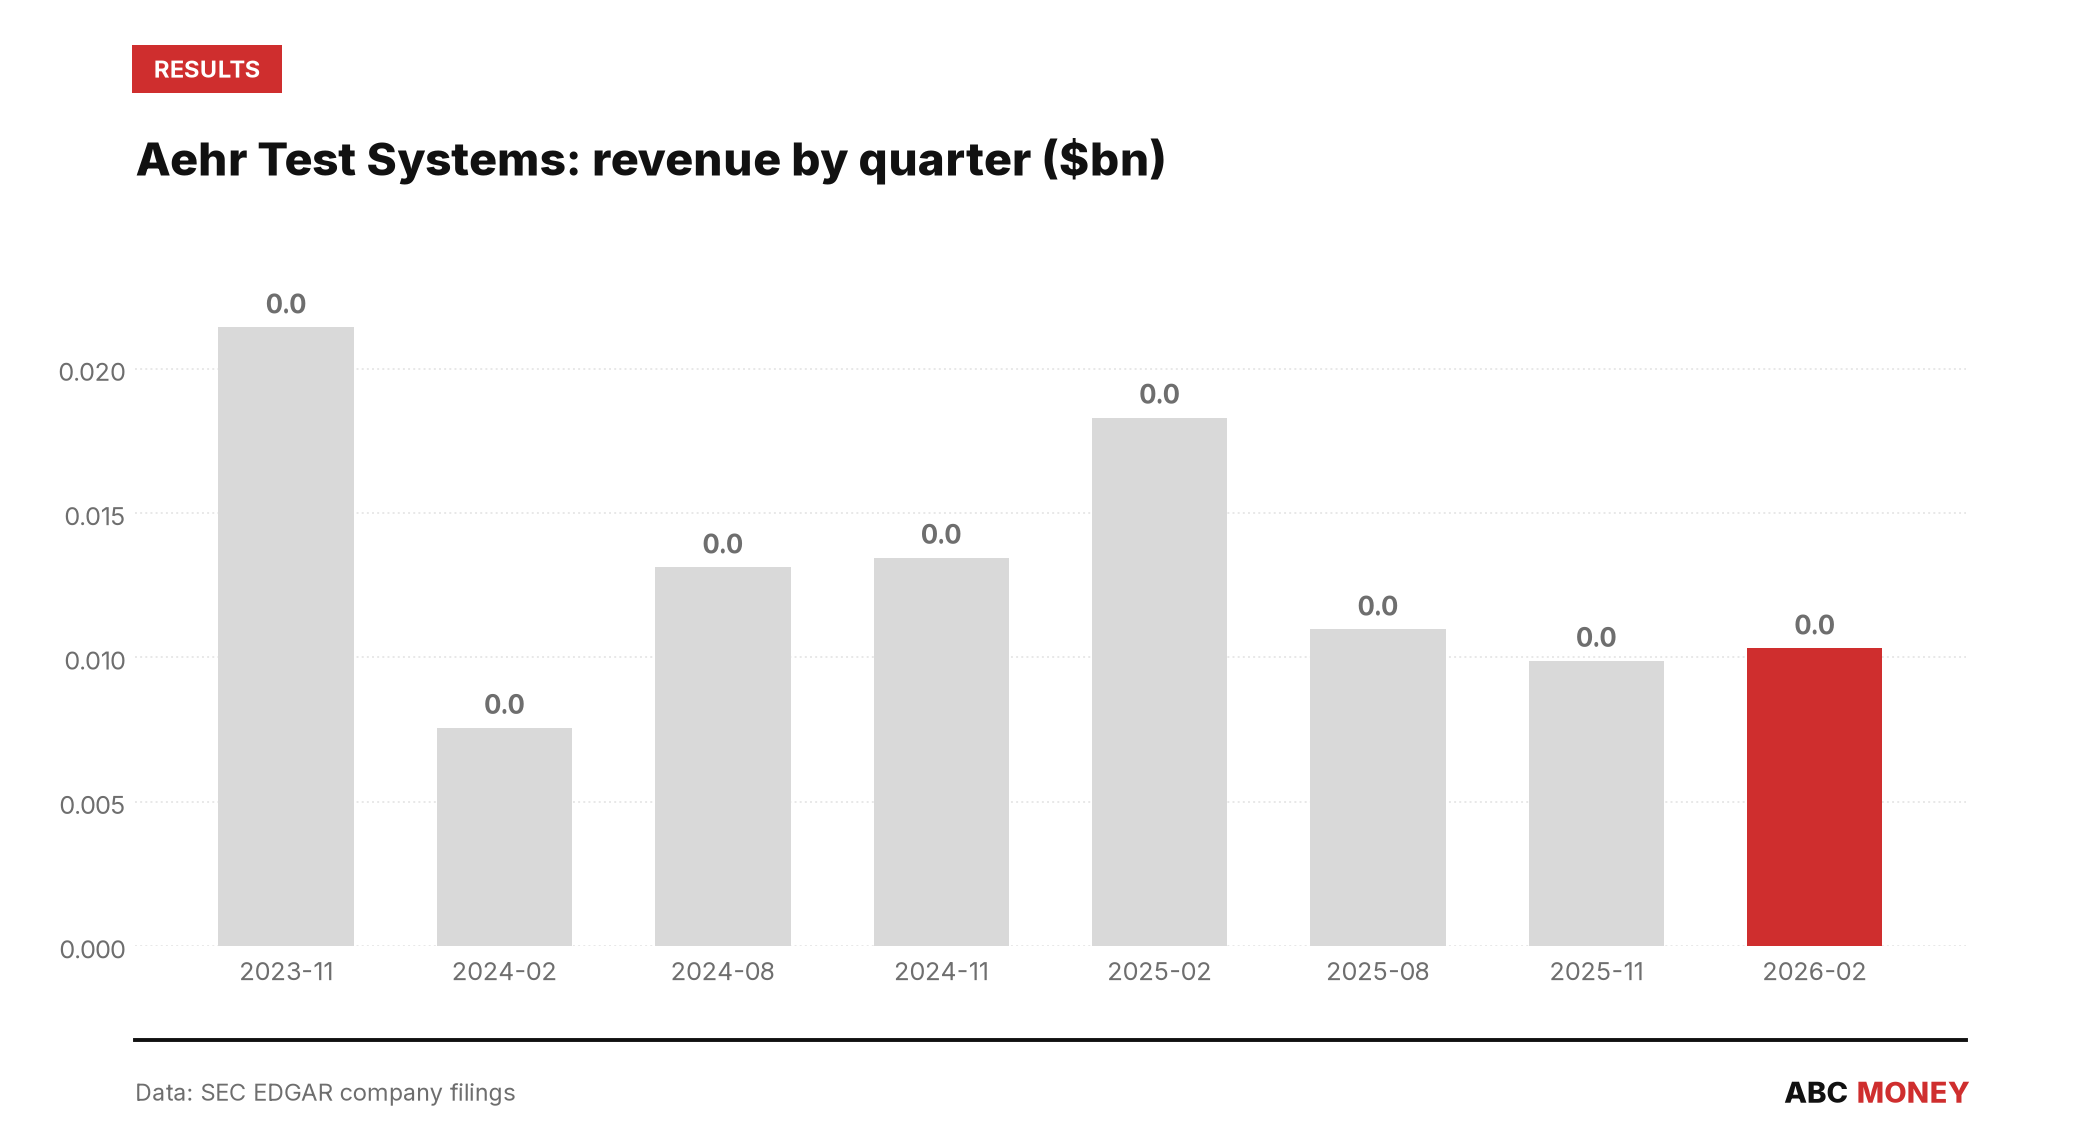
Aehr’s framing of the $150 million guide as a tripling of fiscal 2026 is not loose rounding. The company’s own quarterly filings put revenue for the first three quarters of fiscal 2026 at a combined $31.17 million – $10.97 million, $9.88 million and $10.31 million respectively, a stretch in which the burn-in testing specialist was working through a lull in demand from its biggest customers. Add the roughly $18.8 million fourth-quarter figure cited alongside this release and fiscal 2026 lands close to $50 million for the full year. Three times that is almost exactly $150 million, which means the new guidance is not a stretch target dressed up in marketing language – it is the arithmetic the company is pointing investors toward.
What makes the number notable is how front-loaded the improvement already is. A single quarter of $33.0 million is nearly two-thirds of what Aehr managed in the first nine months of fiscal 2026 combined. The quarterly history shows just how compressed the ramp has been: from $21.4 million in the second quarter of fiscal 2024, revenue fell as low as $7.6 million the following quarter, recovered unevenly through 2025, and spent most of fiscal 2026 bouncing in a narrow $9.9 million-to-$10.3 million band before this quarter’s jump.
Bookings running ahead of revenue
Behind the headline number, bookings in the quarter reached $46.7 million – more than 40% above revenue recognised in the period, according to coverage of the release. That gap between orders taken and revenue booked is the detail management will need to keep delivering on if the $150 million target is to hold up, since it implies demand for Aehr’s wafer-level and package-level burn-in systems, used to stress-test chips before they ship, is still building rather than levelling off. The company also reported adjusted earnings per share of $0.28 for the quarter, as Benzinga reported, a marked turn from the net losses Aehr posted across fiscal 2026, when quarterly results ranged from a $2.08 million loss to a $3.23 million loss on a GAAP basis.
The scale of the ask is worth sitting with. Analyst consensus for full-year fiscal 2027 revenue had stood at $137.06 million before this report, according to figures cited in coverage of the results – meaning Aehr’s own $150 million guide is asking the market to accept a number above where Wall Street had already pencilled it in. Getting there requires the remaining three quarters of the fiscal year to average roughly $39 million each, well above anything the company has yet produced in a single quarter.
A rate backdrop still weighing on growth names
The results landed against a macro backdrop that has not been especially forgiving to richly rated growth stocks. The 10-year US Treasury yield stood at 4.94% on 30 October 2026, only narrowly above the 2-year yield of 4.56%, leaving the gap between the two at 0.32 percentage points and narrowing, according to Federal Reserve data. With unemployment ticking up to 4.2% in September, investors have had reason to stay selective about which growth stories they are willing to pay up for – which may explain why Aehr’s post-earnings rally recovered only a fraction of its prior slide rather than erasing it outright.
One footnote from the filing record: an insider, Alberto Salamone, filed a Form 4 with the Securities and Exchange Commission on the same evening the results were released, though the filing does not disclose the size or direction of the transaction in detail. It is the kind of filing worth watching for a follow-up once the underlying transaction becomes clearer, rather than a signal in itself.
For now, the test is execution. Aehr has shown it can turn a stretch of flat, low-single-digit-million quarters into a $33 million one. Whether it can repeat that scale three more times this fiscal year is the question the company’s own guidance has now put squarely on the table.
This article is for information only and is not investment advice or a recommendation to buy or sell any asset. Markets move quickly; figures are correct as sourced at the time of writing. Always do your own research before making financial decisions.