ADM Q3 Results Beat Forecasts, Yet Shares Fall 5.5%
ADM Q3 results beat on earnings and lifted FY26 guidance for a third time, but shares fell 5.5% on a revenue miss and soft top line.
In this article 3 sections
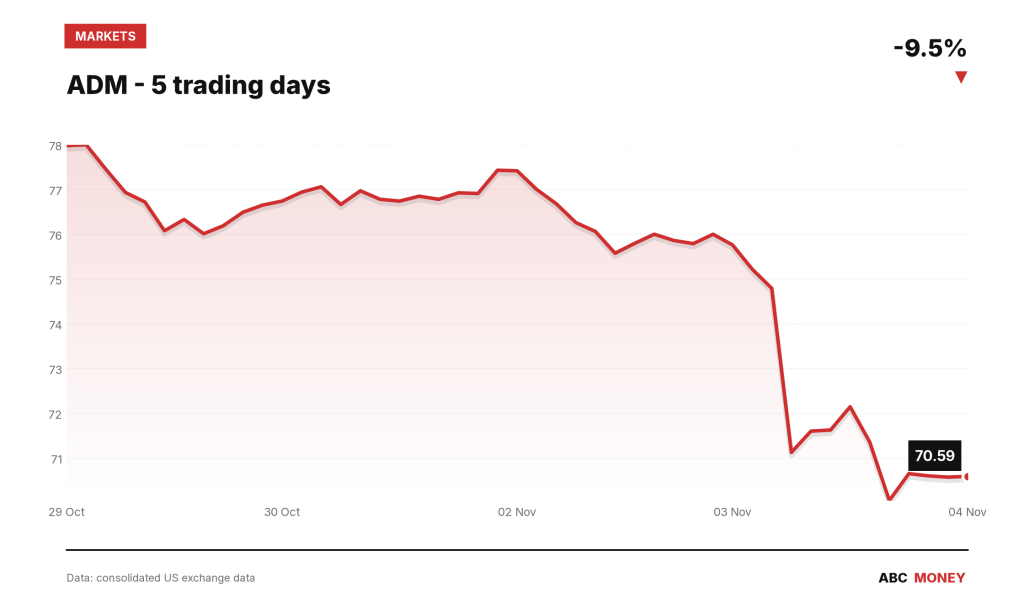
Archer-Daniels-Midland’s third-quarter results told two stories at once: adjusted earnings per share of $1.77, well ahead of the $1.60 analysts had pencilled in, and a third guidance upgrade of the year. Yet Archer-Daniels-Midland (NYSE: ADM) shares still fell 5.5% on the day, a reminder that in a trading house of ADM’s scale, the top line can overrule the bottom line.
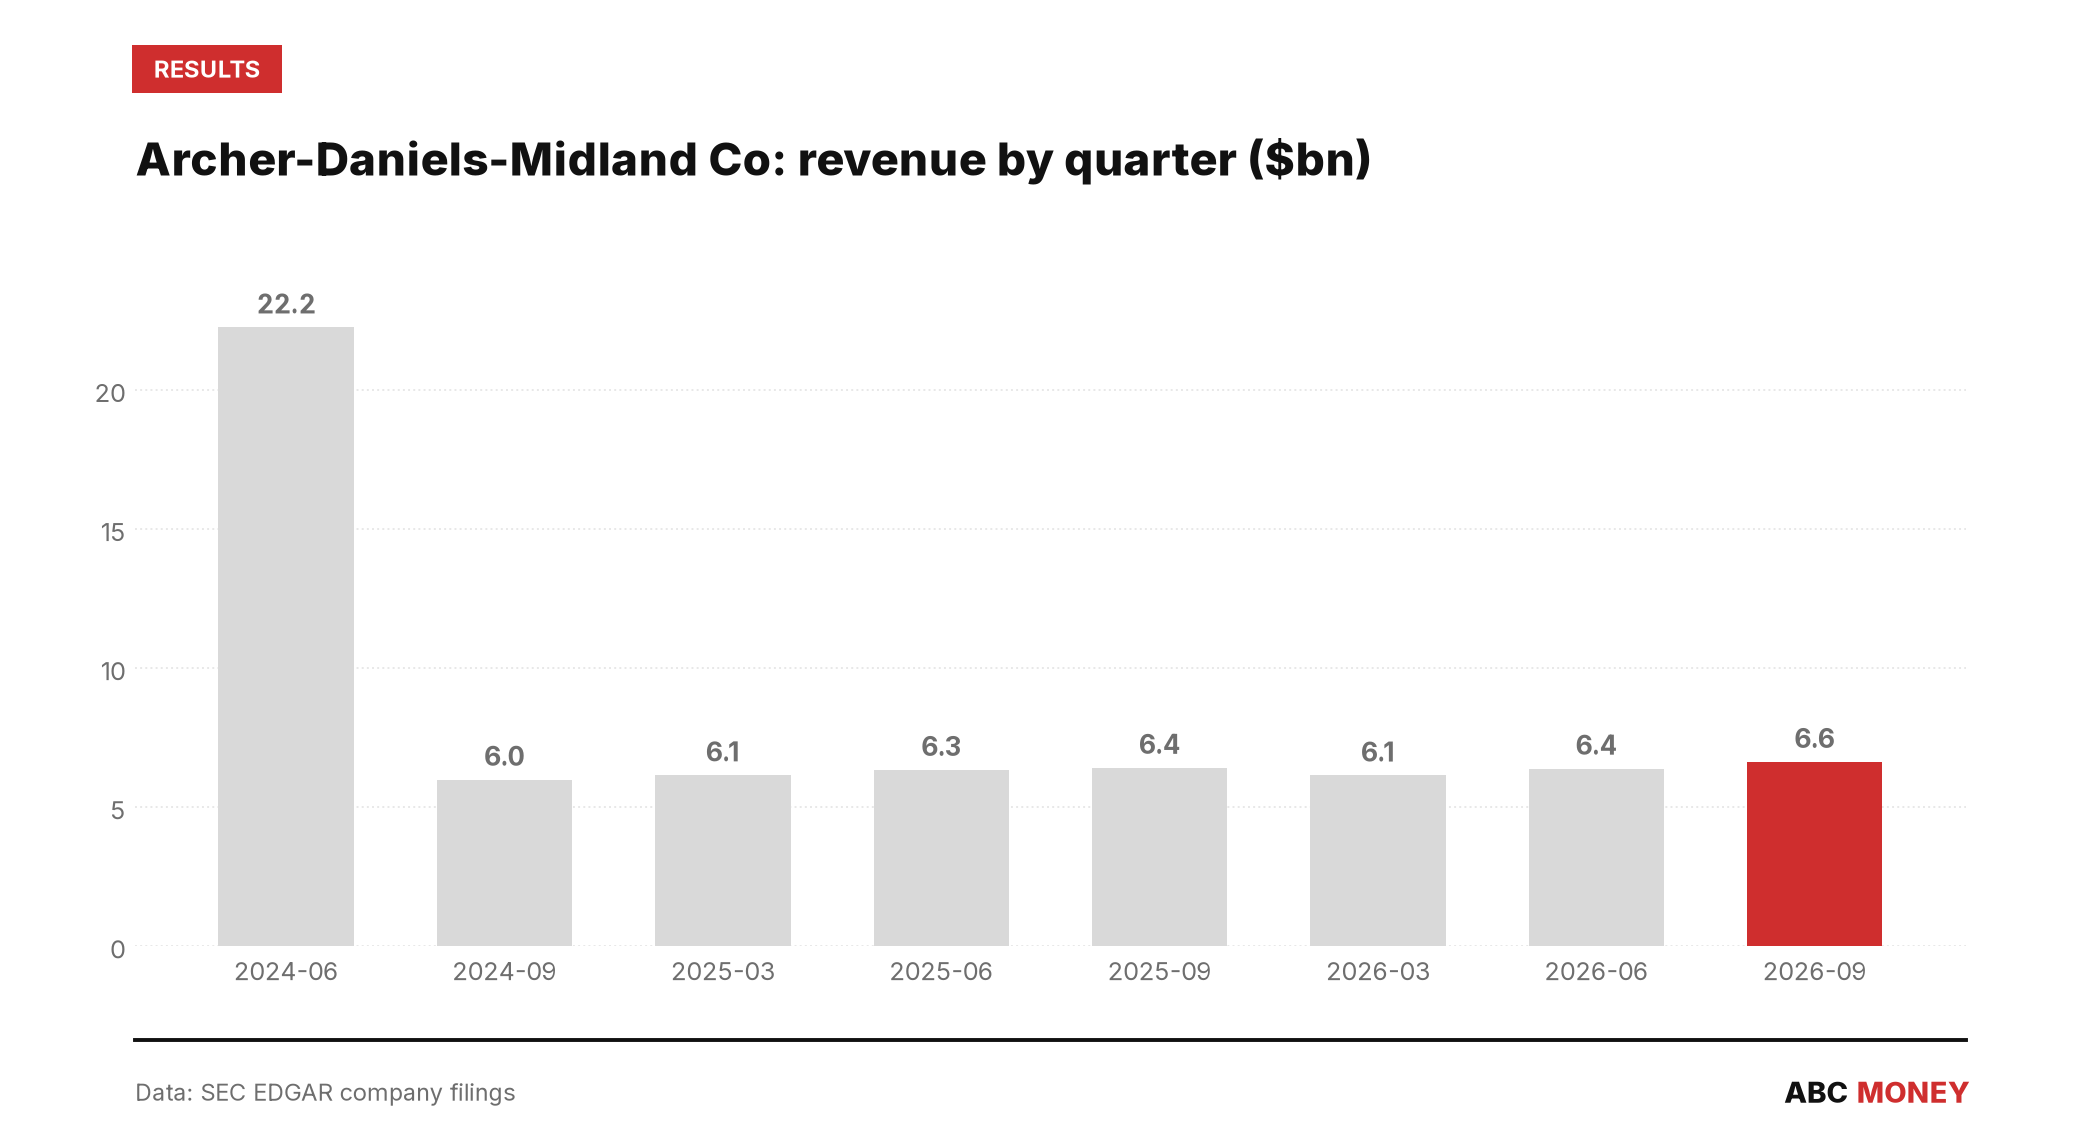
The headline numbers were solid. GAAP earnings per share came in at $1.70, with net earnings of $821 million, up sharply from the equivalent quarter a year earlier, according to the company’s SEC filing. Total revenue rose 9.6% year-on-year to $22.34 billion, from $20.37 billion, driven by what ADM described as strong performance across its grain, oilseed and nutrition segments plus a favourable biofuels market.
Why ADM Q3 results still sent the stock lower
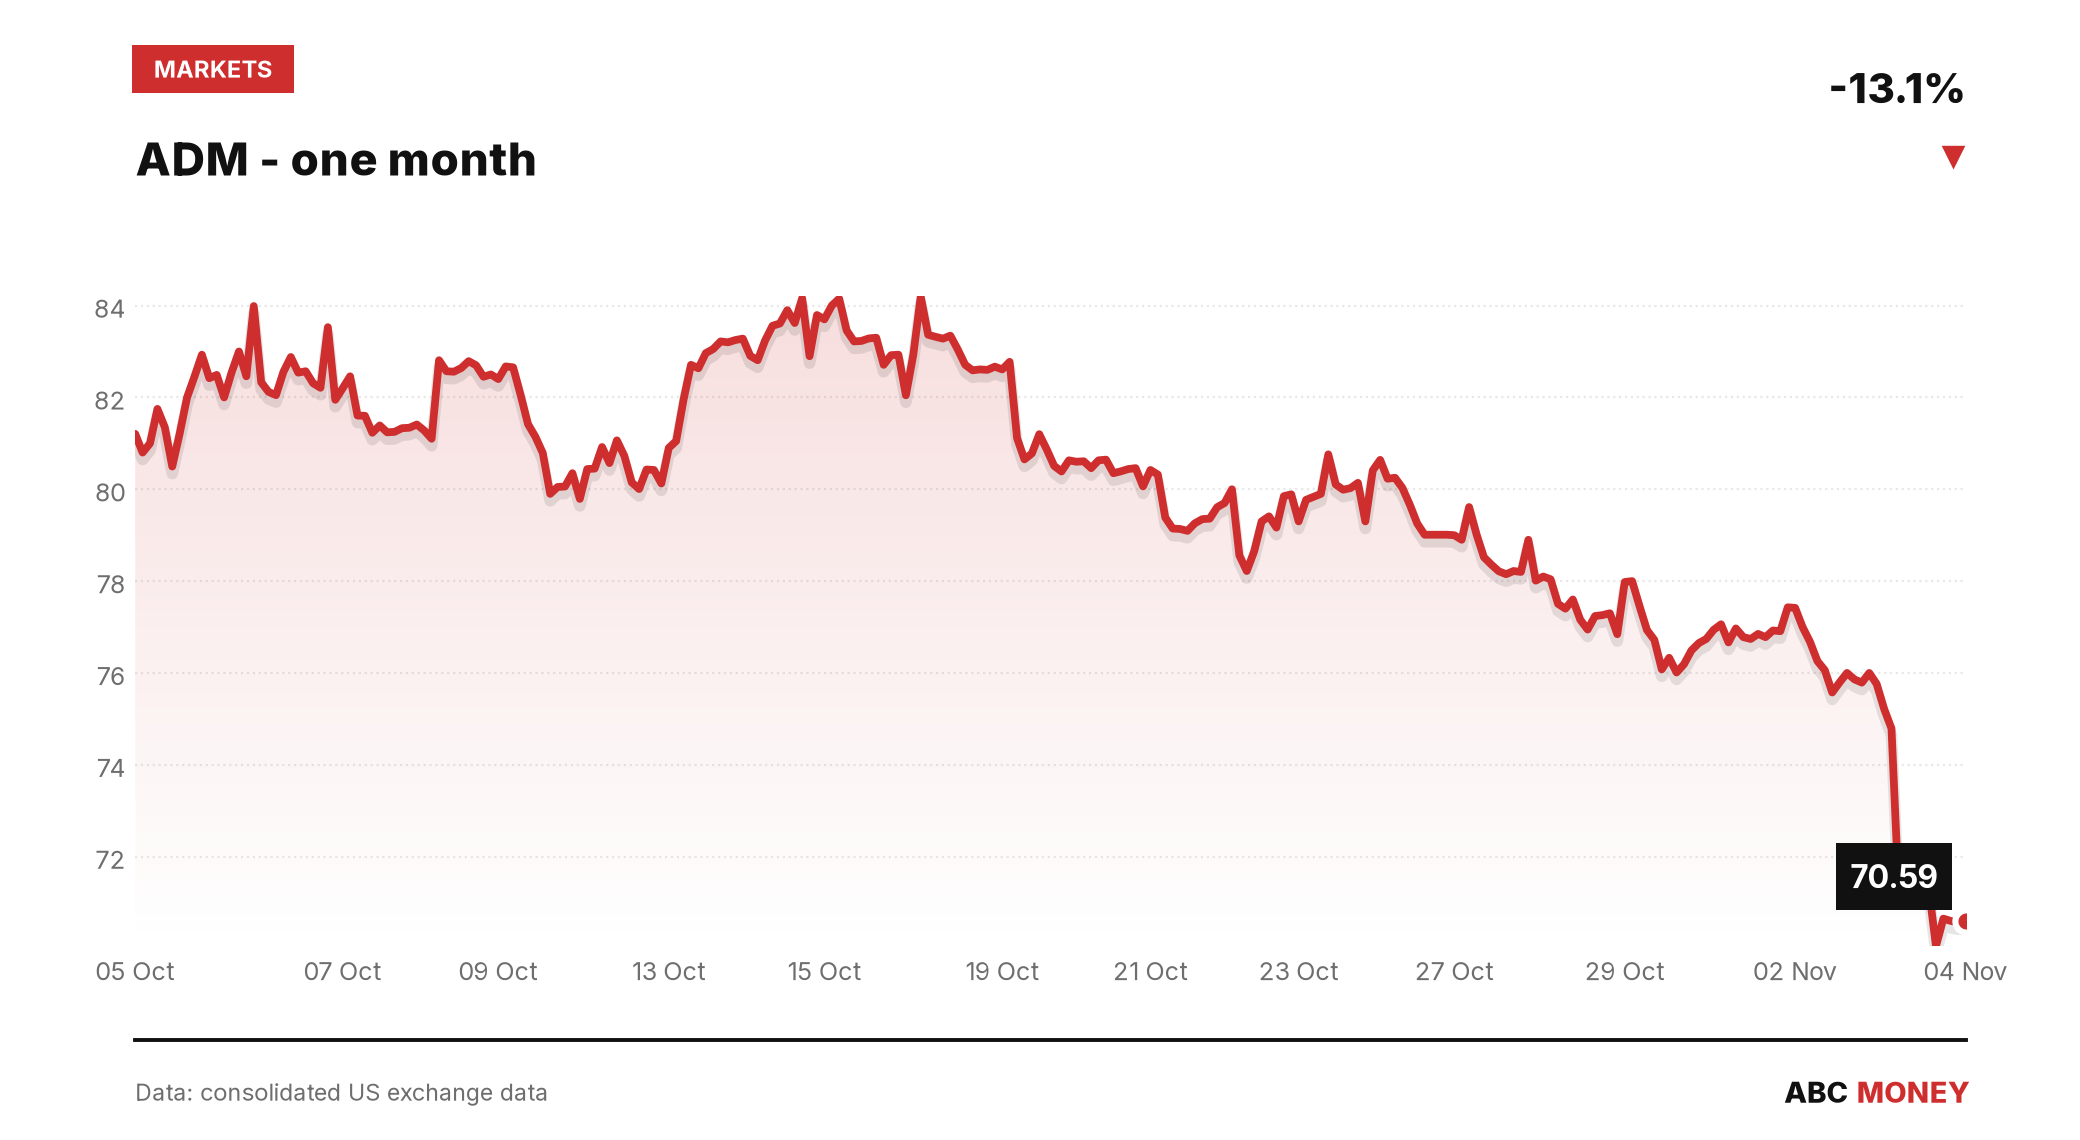
The snag was that $22.34 billion, while up nearly a tenth on the year, still landed short of the $23.27 billion Wall Street had modelled, according to MarketBeat. For a company whose margins are thin and whose earnings swing on volume and crush spreads rather than pricing power, a top-line shortfall of that size outweighed the earnings beat in investors’ eyes. The stock’s 20-day range tells the same story: shares have fallen 15.2% over the past month, touching a 20-day low of $70.05 before closing at $70.59, on volume nearly three times the 20-day average.
MarketBeat’s analyst consensus on the stock was a “Hold” going into results, with an average price target of $81.75 and a dividend yield of roughly 2.9% – a combination that suggests the Street had already priced in a cautious view of ADM’s near-term trajectory even before the revenue miss became apparent.
A third guidance raise in a bumpy year
What makes the reaction notable is that ADM has now lifted its full-year outlook three times in 2026, having already raised guidance alongside its first- and second-quarter results, according to GuruFocus. The new fiscal 2026 adjusted earnings-per-share range sits at $5.50 to $5.80, up from the previous $5.15 to $5.60. Chief executive Juan Luciano told investors that year-to-date performance and the fourth-quarter outlook supported the increase, pointing to operating-profit growth across all segments, per the company’s filing.
Alongside the earnings upgrade, ADM trimmed its capital-spending plans. Full-year capital expenditure guidance now runs from $1.2 billion to $1.3 billion, down from $1.3 billion to $1.5 billion previously, with management citing a sharpened focus on high-return investments rather than a pullback driven by weaker demand. That is a meaningfully different signal from a revenue miss: a company tightening its spending discipline while still raising its profit outlook is not obviously the same animal as one struggling for growth, even if the share-price reaction on the day didn’t draw that distinction.
Positioning and the read into Q4
Trading activity around the report hints at a market that had grown more cautious even before results landed. The proportion of ADM’s daily volume accounted for by short sales – bets that the shares will fall, measured as a ratio of shorted shares to total volume – climbed to 0.641 on results day, up from 0.403 just a week earlier, according to FINRA data. That is not an extreme level in absolute terms, but the steady climb through late October suggests some investors were already leaning against the stock ahead of the print, which may help explain why a genuine earnings beat still met a sharp sell-off.
The net earnings swing across ADM’s recent quarters underlines how lumpy this business can be: net income ran from $108 million in last year’s third quarter to $908 million in this year’s second quarter, before settling at $821 million now, figures drawn from the company’s own quarterly filings. Investors will be watching whether the fourth quarter, and ADM’s next update, can close the gap between an earnings story that keeps improving and a revenue line the market is less convinced by.
This article is for information only and is not investment advice or a recommendation to buy or sell any asset. Markets move quickly; figures are correct as sourced at the time of writing. Always do your own research before making financial decisions.