Cencora Q4 earnings beat lifts FY2027 outlook
Cencora Q4 earnings beat Wall Street forecasts on both profit and revenue, with a 10% dividend rise and bullish 2027 guidance.
In this article 3 sections
Cencora (NYSE: COR) delivered fiscal fourth-quarter results on 4 November that beat Wall Street on every headline measure, with revenue of $88.4bn and adjusted earnings per share of $4.66 clearing analysts’ forecasts and prompting the pharmaceutical distributor to raise its dividend and lift guidance for the year ahead.
The quarter capped a strong year for the Pennsylvania-based group, one of the largest handlers of prescription drugs in the United States, as it rides a wave of demand for specialty medicines – including the GLP-1 weight-loss and diabetes drugs that have reshaped pharmacy economics over the past two years.
A beat built on specialty growth
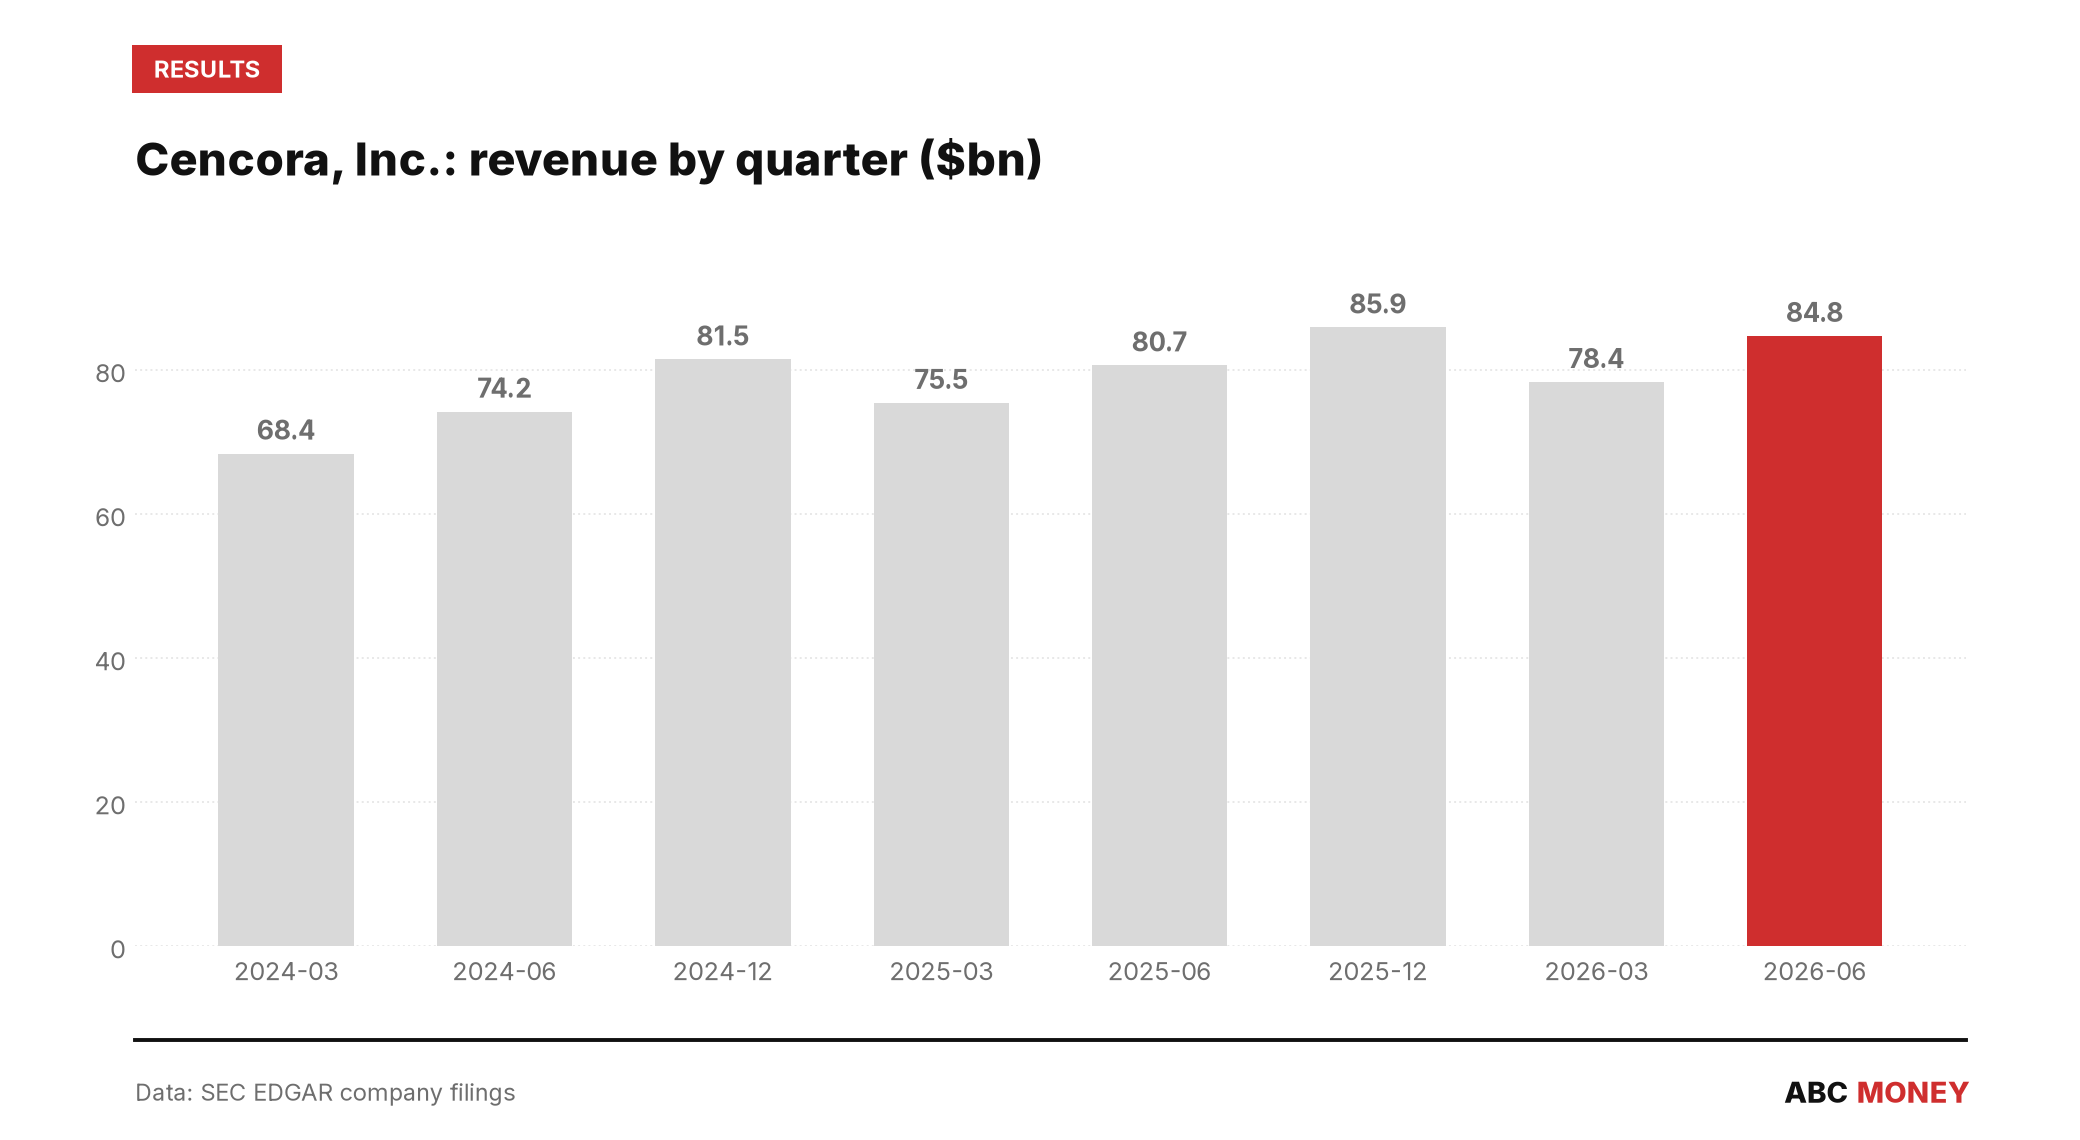
Revenue rose 5.5% year-on-year to $88.4bn in the quarter, according to Cencora’s own filing. GAAP diluted earnings per share came in at $2.71, while the adjusted figure – which strips out one-off items and is the number analysts track most closely – reached $4.66. That topped the Zacks Consensus Estimate of $4.56, a beat of roughly 2.2%, as Zacks reported. A separate read from GuruFocus put the beat at $0.09 a share, with revenue exceeding forecasts by roughly $490m.
For the full fiscal year, Cencora posted revenue of $337.4bn, up 5.0%, with GAAP diluted EPS of $17.95 and adjusted diluted EPS of $17.97 – a reminder of just how thin the gap between reported and adjusted profit has become for a business that runs on wafer-thin distribution margins and makes its money on volume.
Alongside the results, the board raised the quarterly dividend by 10% to $0.66 a share, payable on 30 November 2026, as Investing.com noted. A double-digit dividend increase delivered in the same breath as an earnings beat is usually a fairly clear signal that management is confident the growth is durable rather than a one-quarter blip.
Guidance raises the bar for 2027
More telling than the quarter itself was what Cencora said about the year ahead. The company guided fiscal 2027 adjusted diluted EPS to a range of $19.40 to $19.75, implying growth of 8-10% from this year’s base, and introduced a reorganised set of reportable segments – a structural change that typically signals management wants investors to value the business differently, in this case leaning harder into specialty and biopharma distribution rather than the lower-margin, high-volume generics business that has defined the sector for decades.
That shift matters because specialty drugs, including costly injectable and biologic treatments, carry better economics for distributors than traditional small-molecule generics, even though they add less to headline volume growth. If Cencora’s segment overhaul sticks, it would mark a deliberate pivot away from the commodity end of drug logistics.
Market reaction and the noise around it
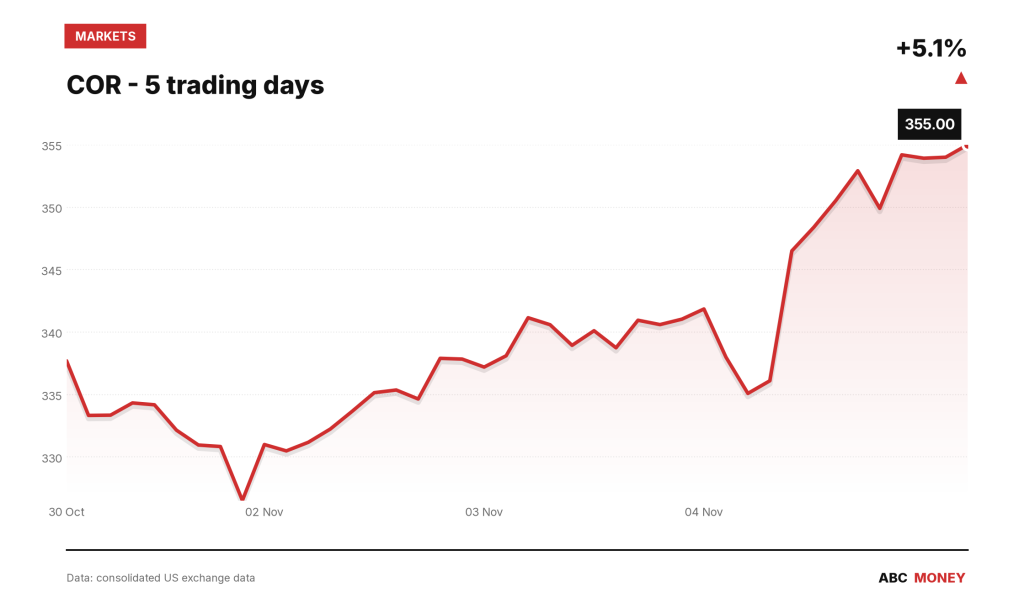
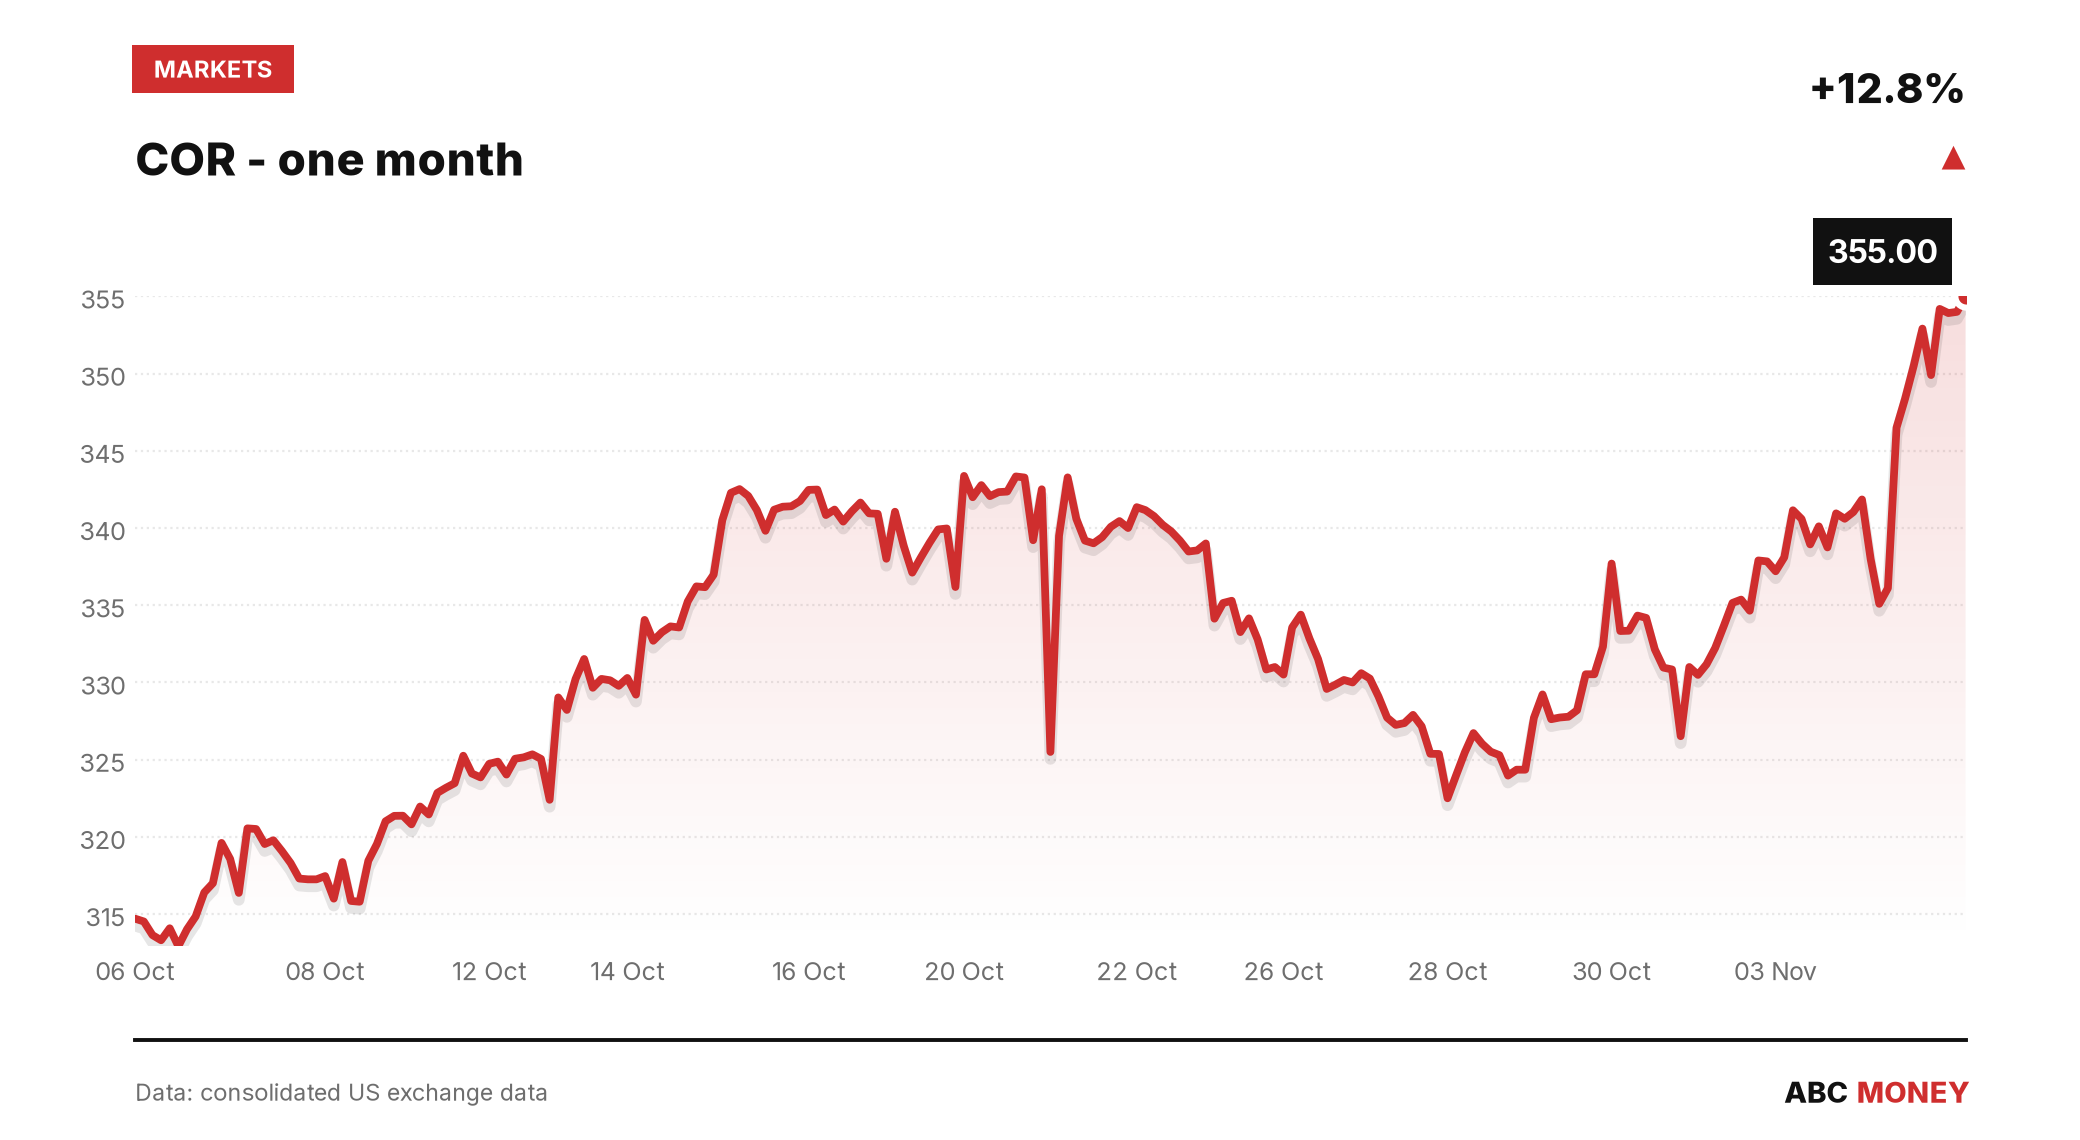
Shares closed at $355.00 on 4 November, up 1.9% on the day and 5.35% over the preceding twenty trading sessions, with trading volume running at 2.3 times the twenty-day average – a sign that the beat drew more attention than a typical quarterly print. The stock’s twenty-day range of $322.50 to $355.00 means Wednesday’s close also marked a fresh high for the period.
One data point worth flagging for anyone trading around the print: daily short-sale volume on COR, tracked by FINRA, rose from a ratio of 0.303 on 2 November to 0.591 on 4 November, the day of the earnings release. That measures the share of daily trading volume attributable to short sales – bets that the price will fall – rather than the stock’s total short interest, so it says more about positioning churn around the announcement than about any broader bearish view building against the stock.
Separately, five Section 16 insiders – executives and directors required to disclose their trades – filed Form 4s with the SEC on 3 November, the day before results, including Dennis Nally, Lauren Tyler, Ellen Cooper, Lazarus Krikorian and Pawan Verma. The filings themselves did not specify share counts or dollar values, so they offer no reliable read on whether insiders were buying or selling ahead of the news.
For investors, the more durable question than this quarter’s beat is whether Cencora’s new segment structure and the specialty-led growth story behind its 2027 guidance hold up as the GLP-1 boom matures and reimbursement pressures on drug distributors evolve. The company’s next scheduled update, its fiscal first-quarter 2027 results, will be the first test of whether the freshly reorganised segments deliver the growth management is now promising.
This article is for information only and is not investment advice or a recommendation to buy or sell any asset. Markets move quickly; figures are correct as sourced at the time of writing. Always do your own research before making financial decisions.